Leveraged and inverse single-stock ETFs attracted a record $30.8bn in net inflows globally between January and July 2026, already surpassing the $22.6bn recorded for the whole of 2025, according to Morningstar data.
Yet Morningstar argues that these products frequently fail at their primary task: delivering their stated multiple of an underlying stock’s daily return.
In a research note titled “These ETFs Had One Job. They Didn’t Do It, Costing Traders Billions,” the data and research provider said that leveraged single-stock ETFs “don't deliver as advertised.” Its analysis found that these products often fell short of their daily return targets even before fees—not merely of the two- or threefold gains that some traders might expect over longer holding periods (see Chart 1).
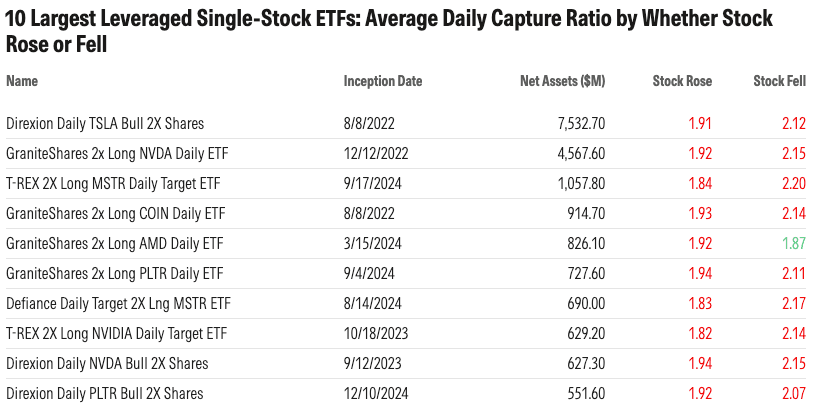
Chart 1: 10 largest leveraged single-stock ETFs: Average daily capture ratio by whether stock rose or fell Source: Morningstar Direct, author's calculations. Data as of Oct. 24, 2025. Average capture ratios based on ETF's daily returns from inception indicated through Oct. 24, 2025; red denotes underperformance of target; green indicates outperformance.
Morningstar measured the shortfall using a “capture ratio”, comparing each ETF’s daily return with its stated multiple of the underlying stock’s return. The firm estimated that persistent tracking shortfalls had cost traders billions of dollars in forgone gains. Swap financing costs have remained high or even worsened despite rising demand, further eroding performance.
The rapid growth of prediction markets such as Polymarket and Kalshi reflects a wider appetite for speculative, event-driven trading. Against that backdrop, it is perhaps unsurprising that some individuals are also drawn to leveraged products linked to volatile, much-hyped stocks in the hope of spicing up their returns.
Kenneth Lamont, principal, manager research at Morningstar, said leveraged and inverse products—which seek to magnify gains or profit from a stock’s decline—are closer to gambling than investing for most people.
Designed primarily for short-term speculation or tactical hedging, these products amplify losses as well as gains. Given retail investors’ poor record of timing markets, they can quickly magnify mistakes and are rarely suitable for building long-term wealth.
Why has the adoption of single-stock ETFs been slower in Europe than in the US and other markets, and do lower European ETF assets and flows accurately reflect retail investors’ appetite for leveraged single-stock exposure?
Kenneth Lamont. - “There are multiple reasons why we have seen less adoption of single-stock ETFs in Europe than in the US and some other markets (see Chart 2).
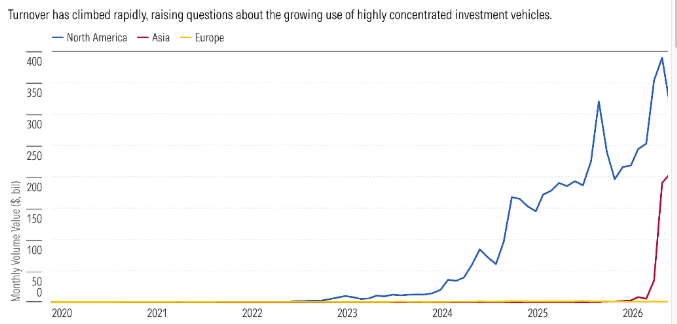
Chart 2: Single-stock ETFs draw record trading activity Source: Morningstar data as of July 31, 2026
However, the data should be interpreted with some caution: lower assets and flows in European-domiciled products do not necessarily mean European retail investors have proportionately less appetite for leveraged single-stock exposure. Some of that activity takes place through other instruments and therefore may not be captured in European ETF datasets.
There are three main reasons for the lower adoption of single-stock ETFs in Europe:
1) A less developed self-directed retail trading market. The US has a much larger ecosystem of retail brokerage platforms and a stronger culture of trading individual stocks, options and, increasingly, leveraged ETFs. Self-directed investing is growing in Europe but remains less developed in many markets.
2) Existing alternatives. European retail investors have long had access to contracts for difference (CFDs), spread betting in the UK, warrants, certificates and other leveraged products that can provide similar exposure. Single-stock leveraged ETFs therefore solve a problem for which established alternatives already exist.
3) Regulation and product structure. Leveraged single-stock ETFs generally cannot satisfy Ucits diversification requirements, which prevents them from being structured and distributed as conventional Ucits ETFs. European investors can access similar exposures through ETPs, ETNs and other debt securities, but these sit outside the mainstream Ucits ETF framework. The answer is partly both: Europe genuinely has a smaller single-stock ETF market, but looking only at ETF assets and flows is likely to understate the amount of leveraged single-stock trading undertaken by European retail investors.
Could the rise of mobile brokers and commission-free trading trigger a surge in European adoption comparable to the growth seen in South Korea?
“Yes. Europeans are also susceptible to the siren call of leveraged bets. Gamification, commission-free trading, etc. could all boost popularity in Europe.
If Morningstar applied its US methodology to Europe’s largest single-stock leveraged ETPs, what gap would emerge between the promised and realised daily multiple after financing, swap costs, taxes, currency movements, and market-closing mismatches?
“I haven’t done the evaluation – but certainly yes. European ETPs also have the same costs.
There are already disclosure requirements covering these products in Europe

Do European disclosures reveal the products’ true costs and risks? “It’s not a ‘scandal’ in the sense that the fees are disclosed – but the reality is that these costs are difficult for most investors to fully interpret and can add up to notable shortfalls in performance.
Where should Europe draw the line between market access and investor protection without driving retail traders toward foreign-listed, potentially less-regulated products?
“There are already disclosure requirements covering these products in Europe. The question is whether the information is presented in a way that allows retail investors to understand the true economic cost and risk of holding a leveraged ETP.
In particular, investors need to understand not only the headline management fee but also financing costs associated with the leverage, trading costs, and the impact of daily resetting and compounding over holding periods longer than a day.
These costs and risks are disclosed in product documentation, but that does not necessarily mean they are equally visible or well understood at the point at which an investor makes a trade.
I therefore think there is a reasonable case for making the all-in cost and the consequences of holding these products for longer periods more prominent and intuitive.”