Despite the ongoing energy supply shock, inflation hasn’t been majorly problematic in the Eurozone so far this year. Inflation expectations, as measured by market break-evens, have remained relatively contained and investors initially treated the Middle East energy shock as a temporary event. However, the inflation backdrop is becoming increasingly challenging. A combination of higher energy prices, fading fiscal support, rising food prices and resilient economic activity suggests inflation could remain sticky above the ECB’s target for longer than many anticipate.
The starting point is energy. The effective closure of the Strait of Hormuz following the Iran conflict triggered a sharp rise in oil and gas prices. While investors initially expected energy prices to normalize quickly, fading hopes for a diplomatic breakthrough have pushed oil prices higher once again, with Brent currently trading around $105 per barrel. The key concern is not only the level of prices today, but the growing recognition that oil may not return to pre-Iran war levels any time soon. Natural gas prices have risen even more sharply, and unlike oil, the impact on households and businesses typically appears with a significant lag as wholesale prices gradually percolate into utility bills. As a result, the full inflationary impact of the energy shock is likely still ahead of us rather than behind us.
A crucial difference versus the 2022-23 energy crisis is the limited fiscal response given already-elevated core deficits. At the height of the 2022 energy crisis, total EU energy subsidies reached €457bn. By contrast, in May, the European Commission estimated that the budgetary cost of measures announced in response to the Middle East energy shock amounted to €14.5bn, rising to €38.6bn if all measures were extended through the end of 2026. Today, these estimates have proven quite conservative, but absolute spending relative to 2022-23 is still much more modest.
A thinned-down fiscal cushion comes at an inopportune moment. Europe must continue replenishing energy inventories while commodity prices remain elevated. Notably, underground gas storage facilities across the EU are only around 71% full, the lowest level recorded for this time of year since data collection began in 2011. Rebuilding inventories at elevated prices could place additional upward pressure on energy costs heading into winter, increasing the risk that headline inflation remains stubbornly high well into 2027.
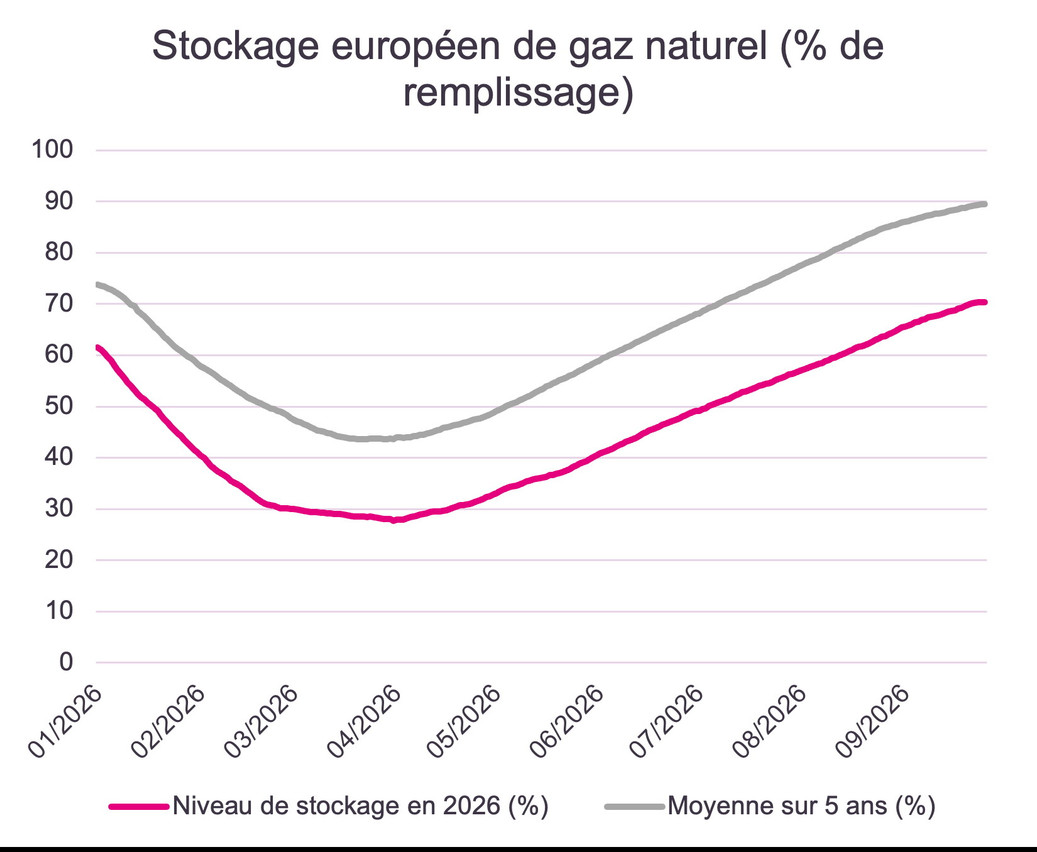
European natural gas storage (% full) Sources: Bloomberg, Bil
Inflation risks are also extending beyond energy. Food prices have already experienced a substantial increase in recent years, and further upward pressure is emerging. The Iran war has lifted energy and fertiliser costs, while adverse weather conditions linked to El Niño are creating additional pressure on agricultural production. The combination of higher fertiliser, transport and energy costs is likely to feed through into food prices over the coming quarters.
Encouragingly, there is still not a strong case to suggest that these shocks have generated significant second-round effects. ECB President Christine Lagarde has repeatedly stated that the central bank does not yet see convincing evidence that energy prices are feeding into higher wages across the economy.
However, it is our view that the risk of a broadening out in inflation pressures should not be dismissed. As the chart shows, wages are already beginning to creep up in the bloc’s largest economies.
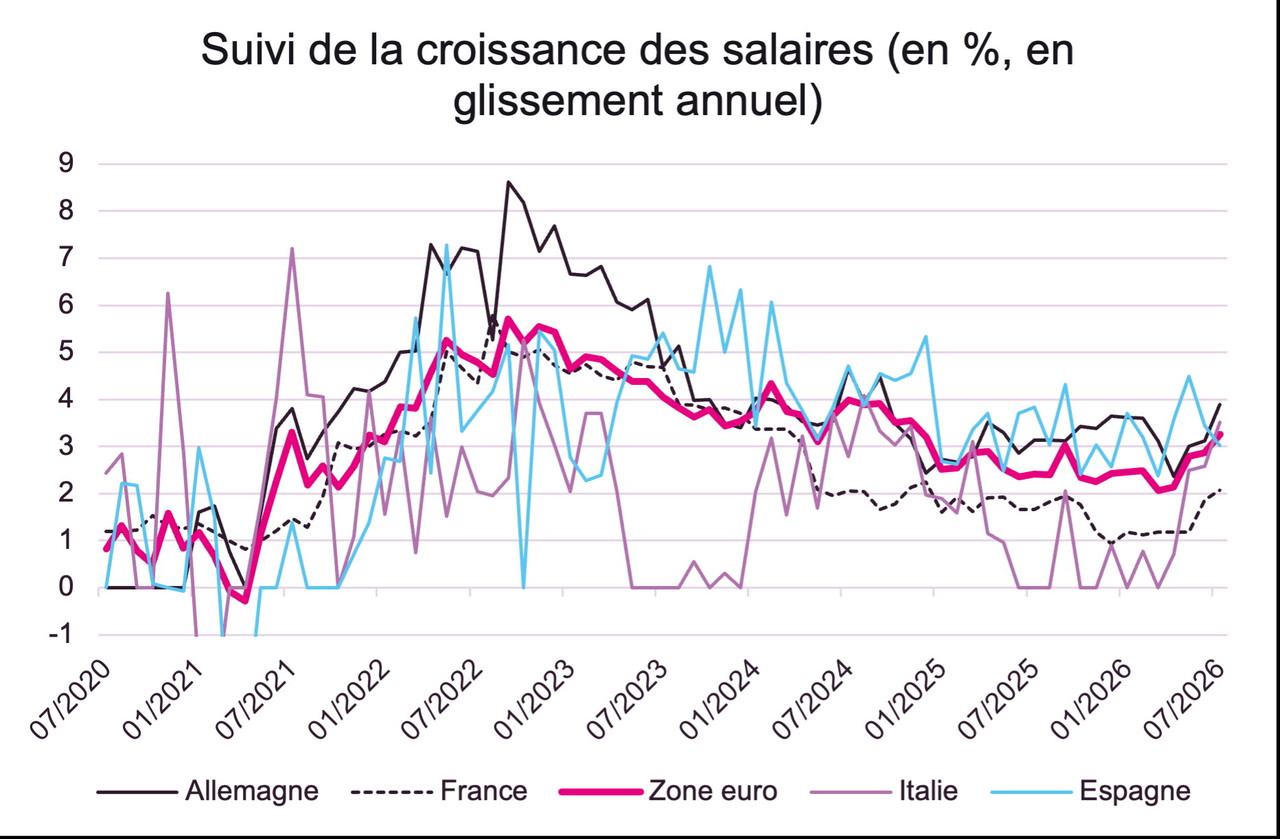
Tracking wage growth (as a percentage, year-on-year) Sources: Indeed, Bloomberg, Bil
The risk is that a prolonged period of above-target inflation ultimately influences wage negotiations, particularly given that labour markets remain relatively resilient across much of the Eurozone.
Recent economic data offer little comfort on the inflation front. Survey evidence suggests that Eurozone activity continues to hold up relatively well despite higher commodity prices. The composite PMI remains consistent with ongoing expansion and points to accelerating price pressures. According to the latest flash readings, both input costs and output prices increased in September at the fastest pace in four months. This resilience is important because it reduces the likelihood that weaker demand will naturally bring inflation back towards target. Instead, it raises the possibility that the ECB will need to maintain a restrictive policy stance for longer.
Financial markets appear to be moving in that direction. Investors are already pricing almost four additional quarter-point ECB rate increases over the next year, on top of the two hikes already delivered.
Our base case is that inflation remains above the ECB’s 2% target throughout 2027. Higher oil prices should keep headline inflation elevated through year-end, while the delayed pass-through of higher natural gas prices is likely to sustain pressure on household utility bills. We expect the ECB to raise the deposit rate once more in December to 2.75%, which would take policy deeper into restrictive territory. Beyond that, the duration the energy crisis – and its ripple effects – will largely determine the policy pathway.
But overall, Eurozone inflation risks are skewed to the upside. Energy prices are higher, fiscal support is constrained, soft commodity prices are on the up, and economic activity remains surprisingly resilient. While inflation may not yet be embedded in wages and inflation expectations, the ECB’s fight against inflation is not over. Markets appear to recognise this, but there is a growing risk that participants are still underestimating how persistent the current inflation shock could become.