Robotics has rarely attracted so much money or raised so many questions about where it is going. Start-ups in robotics and physical AI secured a record $18.6bn of fresh new money in the second quarter of 2026, even as dealmaking slowed.
Behind the headline is a market split between a handful of capital-hungry platforms and proven automation businesses investors appear to be overlooking, noted Pitchbook in a report titled “Robotics & Physical AI: The Money Is in the Motion.”
A record built on three deals
Funding rose 25.3% from the first quarter and 47.9% year on year, according to Pitchbook. Yet three rounds — $5bn for US defence company Anduril Industries, $1.4bn for Germany-based NEURA Robotics and $1bn for Physical Intelligence — generated 39.8% of the total. Excluding those rounds, investment totalled $11.2bn, representing a more modest quarterly rise of 9.9%.
Deal numbers dropped 14.1% to 450, while venture-growth rounds absorbed $7.7bn. Excluding Anduril, early-stage funding would still be the largest category. The record was less a broad surge than proof of how much cash a few leaders can consume.
Software learns to touch the world
Investors are shifting towards the intelligence and machinery that make robots move. Funding for AI and autonomy platforms climbed 437.9% over the trailing 12 months reaching $7.7bn, while unmanned ground vehicles rose 609%. Actuators and motion systems grew 103%, and tooling advanced 425.8%.
Robots cannot rely on an internet-sized training corpus. They need data from simulation, teleoperation and real deployments. Skild AI’s purchase of Zebra Technologies’ former Fetch Robotics operation brought installed warehouse fleets, customer workflows and a stream of physical-world information.
The factory floor tests the hype
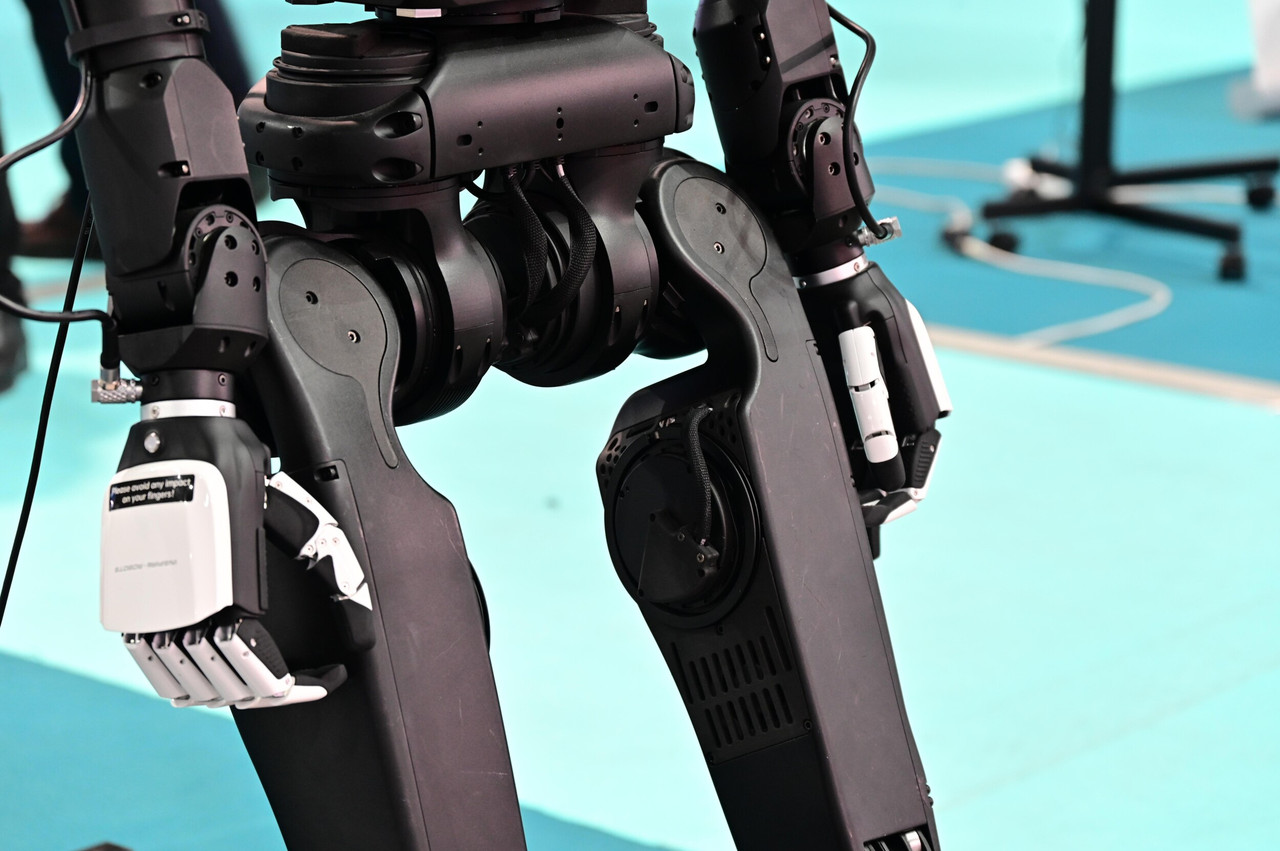
AGIBOT said its G2 robots completed 64,828 tasks over more than 64 hours on a tablet production line, with a 99.99% success rate. Figure reported that its BotQ plant had accelerated output from roughly one robot a day to one an hour.
These are steps beyond choreographed demonstrations, but the figures are company-reported. Most humanoid developers still reveal little about fleet size, uptime, human interventions or cost per task. Those are key measures that determine whether automation pays.
Demand hides in plain sight
The clearest commercial signals came from conventional automation in sectors such as warehouse automation, data centres, semiconductors and energy. Symbotic reported $721m in quarterly revenue, up 22% year on year, with 77 systems in deployment. Rockwell Automation’s quarterly sales rose 12% to $2.2bn, while Teradyne’s robotics revenue reached $100m.
Yet venture funding for logistics and warehousing robotics fell 68% from the previous quarter. Investors appear to be paying for long-term platform potential while customers buy technologies with measurable returns today.
Capital becomes the product
Scaling robotics is not only an engineering challenge. Factories, inventory, installation and maintenance must often be financed before revenue arrives. Robotics-as-a-service pushes more of that burden on to suppliers, which fund machines upfront and assume the uptime risk.
A large raise may reflect demand, industrialisation costs, an ambitious price tag — or all three. The report argued that investors must distinguish between financing a repeatable machine and subsidising bespoke integration.
Motion wins before the machine
Public markets delivered a similar message. Six listings accounted for almost all the quarter’s $2.9bn in exit value. China’s SEER Robotics listed at $1.5bn and Nanchang Sanrui Intelligence Technology at $1.3bn. Both sell navigation or motion technology rather than complete robots.
For now, value is accumulating in less glamorous layers: software, sensors, actuators, integration and operating data. The money is in motion, but the business case still has to catch up.