Investors are betting that the global economy can defy gravity. Cash is scarce, equity exposure is at a near five-year high, and recession fears have almost vanished. Yet beneath the exuberance lies an awkward contradiction: the artificial intelligence boom powering the rally is also seen as its greatest threat.
Bullishness breaks the dial
Bank of America’s August Global Fund Manager Survey is the third most bullish reading since 2022 (see Chart 1). Conducted from 7 to 13 August, it drew 203 panellists overseeing $581bn in assets.
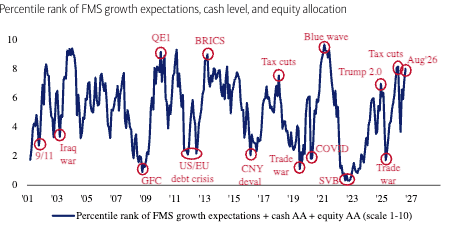
Chart 1: BofA Global FMS investor sentiment very bullish in August Source: BofA Global Fund Manager Survey
Cash holdings slipped to 3.5 per cent of assets from 3.6 per cent, the sixth-lowest level since the survey began in 1998 (see Chart 2). That keeps BofA’s contrarian “sell” signal active, triggered at 4 per cent or less. A net 56 per cent are overweight global equities, the highest since November 2021. Investors have favoured equities for 14 consecutive months.
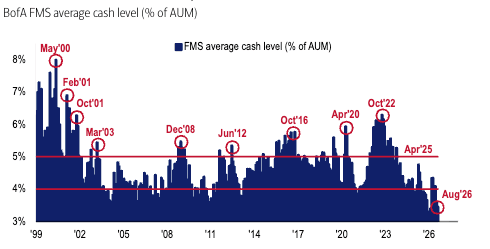
Chart 2: FMS cash level falls to 3.5%, the 6 th lowest level since 1998 Source: BofA Global Fund Manager Survey
No landing, no bears
The optimism rests on an unusually confident macroeconomic view. A record 56 per cent expect “no landing” for the global economy over the next 12 months, up from 54 per cent in July (see Chart 3). Another 34 per cent foresee a soft landing, while only 4 per cent anticipate a hard one.
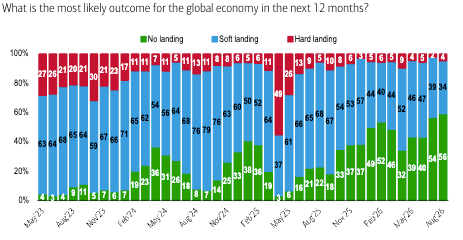
Chart 3: "No landing" consensus rises further to new 56% high Source: BofA Global Fund Manager Survey
A net 37 per cent believe global earnings will grow by at least 10 per cent in the coming year, the most since August 2021. And 43 per cent forecast an economic boom, the highest share since February 2022.
Some 72 per cent do not expect the US Federal Reserve to raise rates before November’s midterm elections. Political risk looks less benign: if Democrats take both chambers of Congress, 37 per cent expect bond yields to rise and shares to fall.
The AI contradiction
Technology remains both the market’s engine and its fault line. Long global semiconductors were named the world’s most crowded trade by 53 per cent. That is below July’s record 82 per cent, but far ahead of short Japanese yen positions at 12 per cent and long Magnificent Seven bets at 11 per cent (see Chart 4).
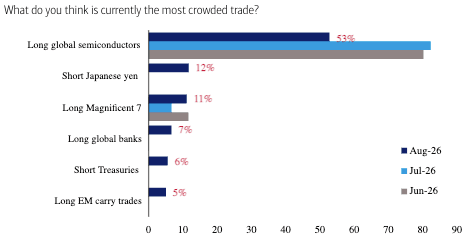
Chart 4: Most crowded trade = "long global semiconductors" Source: BofA Global Fund Manager Survey
An AI bubble was the leading tail risk for a second month, cited by 32 per cent, while 38 per cent identified hyperscaler spending as the likeliest source of a systemic credit event. Net 19 per cent regard corporate balance sheets as overleveraged, the most since March 2023.
Nevertheless, 71 per cent expect no hyperscaler to cut capital expenditure in 2026. Some 31 per cent do not believe AI will materially disrupt labour at all, while 27 per cent expect widespread job losses in 2028 or later. Investors see the danger but are not positioning for the boom to end.
Where the crowd is leaning
US equities remain a favourite: a net 27 per cent are overweight, the highest since December 2024. Emerging-market equities command an even larger net overweight of 34 per cent, while commodities stand at 24 per cent. Bonds, by contrast, are net 39 per cent underweight.
The neglected corners tell a different story. UK equities are net 33 per cent underweight, consumer discretionary stocks 12 per cent underweight and consumer staples 19 per cent underweight. A net 16 per cent also judge gold to be undervalued, its strongest showing since March 2023 (see Chart 5).
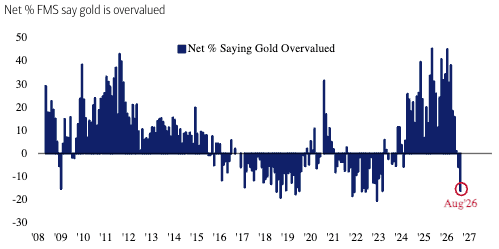
Chart 5: Net 16% say gold is undervalued, most since March 2023 Source: BofA Global Fund Manager Survey
That leaves a clear contrarian map. BofA suggests retreating or rotating within risk assets rather than adding more: favour bonds over commodities, staples over technology, discretionary shares over banks, and UK stocks over their US counterparts. When almost everyone expects gravity to remain suspended, the cheapest insurance may sit precisely where the crowd is least willing to look.