The global economy has proved unexpectedly resilient in recent months, but the buffers protecting it from a severe downturn are diminishing. Lower energy prices during the summer, fiscal stimulus and investment in artificial intelligence have helped sustain growth.
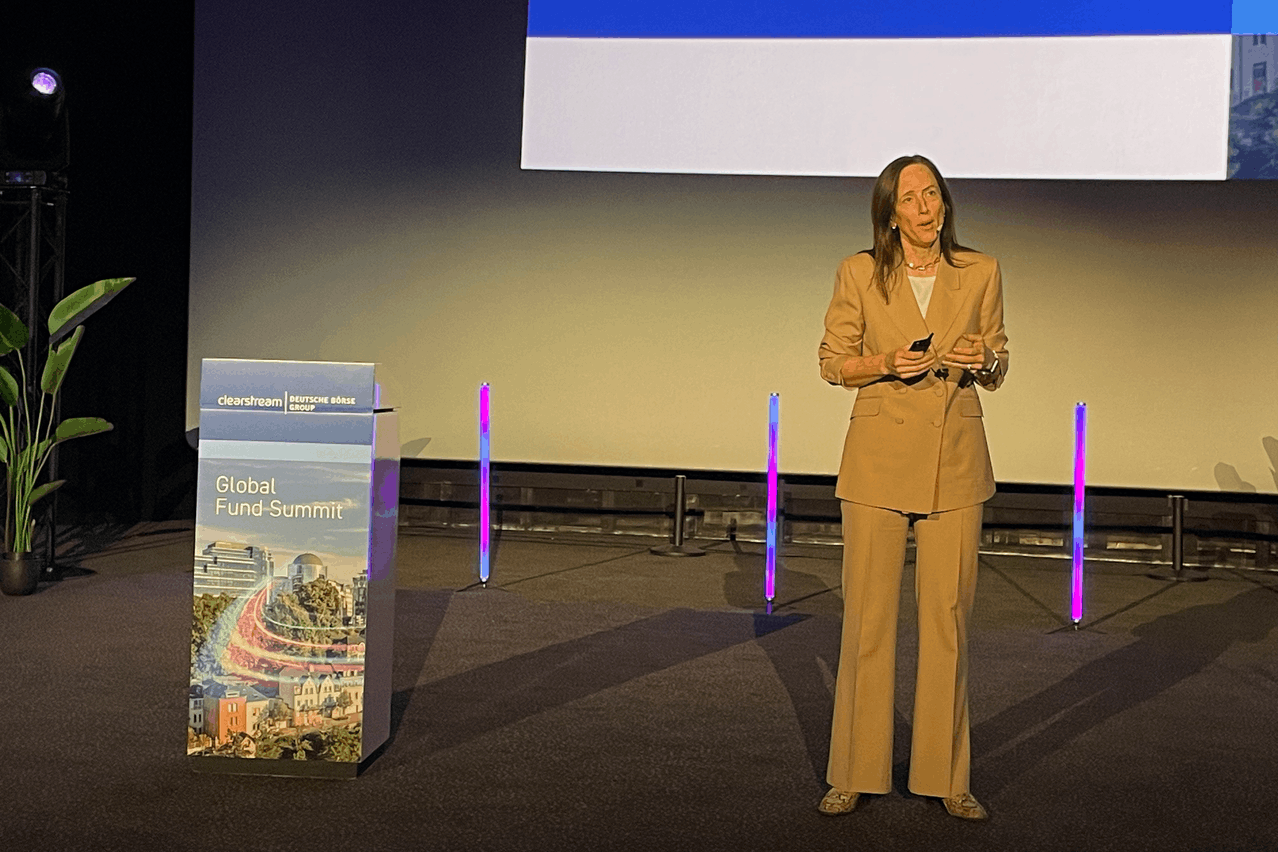
That resilience is now being tested. Disruption in the Strait of Hormuz, rising energy costs and persistent inflation have left central banks with limited room to manoeuvre. Speaking at Clearstream’s Global Fund Summit on 29 October 2026, HSBC global chief economist Janet Henry warned that these risks were increasingly reinforcing one another.
Energy costs and the squeeze on households
Geopolitical disruption in the Strait of Hormuz has reignited volatility in oil and gas markets. Surging prices for refined products such as diesel and petrol are reducing households’ disposable income across Europe and the UK, leaving consumers with less to spend elsewhere.
Highlighting the burden facing consumers, Henry said it had cost her £160 to fill her diesel car, illustrating the significant effect of fuel prices on household budgets.
Henry expects higher energy costs to continue feeding through to consumer prices in the coming months, intensifying the pressure on households and pushing inflation higher. Inflation could begin to ease if there is “some form of resolution” in the Strait of Hormuz, she said.
European consumer confidence fell sharply from October onwards. This matters because real wage growth is one of its key drivers—and real wages are projected to contract as inflation accelerates.
In the US, meanwhile, equity ownership remains concentrated among older households.
“Seventy-nine per cent of equities and mutual funds held by US households are in the hands of people aged over 55,” Henry said.
The wealth accumulated by this demographic has helped support the strength of US consumer spending. That concentration, however, also leaves household expenditure vulnerable to a pullback in asset markets.
Technology momentum and fiscal retreat
Fiscal stimulus helped sustain global growth through 2026, including US federal spending, the EU’s NextGenerationEU programme and Germany’s infrastructure package. Henry argued that this support would fade in 2027 and begin to weigh on growth. In the US, debate over the debt ceiling is also expected to dominate fiscal policy.
Corporate investment in AI has emerged as an important offset. Henry pointed to a stronger-than-expected increase in UK business investment, partly associated with the adoption of AI.
The crucial question is whether this momentum can continue as public spending slows. If corporate investment fails to compensate for the withdrawal of fiscal support, global growth could lose another of its remaining sources of resilience.
Central banks walk a high-inflation wire
Central banks face a difficult balancing act as supply shocks push inflation further above their targets. Henry noted that energy prices had already exceeded the levels considered in the European Central Bank’s adverse scenario in August.
Inflation is projected to peak at close to 5% in the UK and remain above 4% in the eurozone through early 2027. Higher energy and food inflation is also expected to become increasingly visible in consumer prices.
Policymakers remain focused on preserving their institutional credibility. Allowing inflation to remain above target for too long could weaken public confidence, but raising interest rates further would place additional pressure on already fragile growth.
Henry also highlighted a shift in the US labour market, describing it as a “‘no hire, no fire’ kind of world.” Companies are reluctant to expand their workforces, but widespread job losses have yet to materialise.
With inflation remaining elevated, further interest-rate increases are expected from major central banks. Such moves would reinforce their commitment to price stability while increasing the risk of a sharper economic slowdown.
Sovereign debt and the productivity gamble
Government debt exceeds 100% of gross domestic product in many advanced economies, leaving states facing higher interest costs in the coming years. Governments are effectively betting that stronger productivity growth, supported by automation and AI, will allow them to grow their way out of their debt burdens.
Whether that bet will pay off remains uncertain. “The story is unwritten on AI productivity,” Henry said.
The fiscal challenge extends beyond productivity. Current tax systems remain heavily dependent on employment income: taxes linked to workers generate about 80% of US government revenue, while corporate taxes account for only 10% to 15% of revenues across OECD economies.
“Under current tax structures, the vast majority of revenue growth comes from workers,” Henry warned.
If AI enhances workers’ productivity, it could strengthen economic growth, wages and government finances. If it replaces large numbers of jobs, however, states could face substantial revenue shortfalls at a time when debt-servicing costs and demands on public spending are already increasing.