Sylvain Barrette: On 5 June 2025, the European Central Bank cut interest rates to 2.00%. Inflation expectation for 2025 was reduced from 2.3% to 2.0% and to 1.6% for 2026. Is that reasonable? What should we expect in terms of the upcoming move from the central bank?
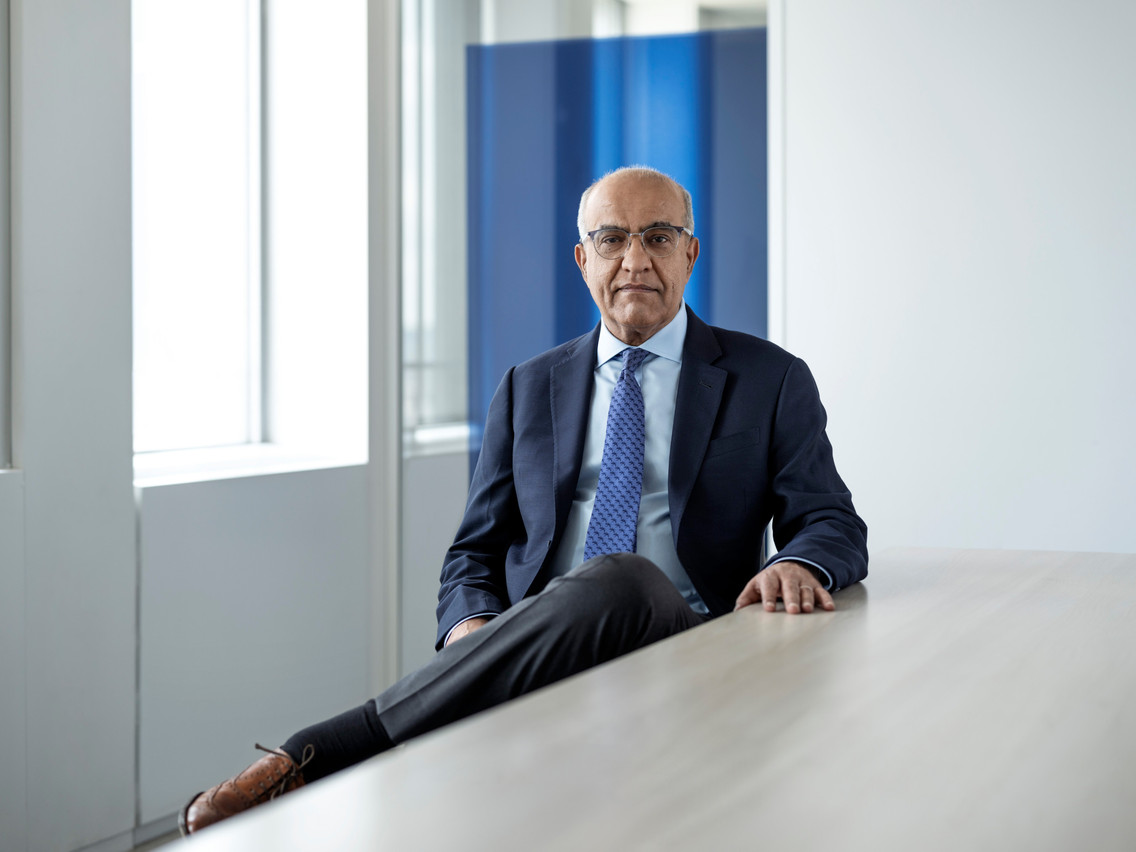
Mahmood Pradhan: It was inevitable and therefore also reasonable… because inflation pressures in Europe are very benign. Wage growth, in what they call the wage tracker, is coming in below where they were forecasting. In addition, they have favourable effects from our energy prices. Third, if you look at the last two years, growth in Europe has been very weak.
Before “Liberation Day” [tariffs that were announced by US president Donald Trump on 2 April, editor’s note], we were hoping this year would be a gradual and mild recovery in Europe… But then we had the trade tensions and the tariff war.
At the beginning of the gradual recovery, we were seeing a rise in real disposable income. Second, we saw the beginnings of credit growth in banks’ lending, both to households and the corporate sector. That’s always an early signal. When you can see credit growth, then there is a sign of economic activity picking up.
The aggressive stance of the US administration on tariffs--particularly on autos, steel and aluminium--and the expectation of something on pharmaceuticals [the second-largest export sector in Europe] have made the ECB and private forecasters reduce European growth forecasts, currently standing between 0.6% and 0.8%. We are at 0.9% at Amundi.
Read also
The thing that surprised me is [ECB president Christine] Lagarde’s statement. [The ECB] is weighing, on the one hand, the risk of trade tensions and tariff sanctions continuing and depressing growth, or, on the other hand, an expansion in European fiscal spending, infrastructure and defence that could start next year.
My reading is: if the ECB has reduced its inflation forecast to 1.6% [for 2026], then it could not be expecting very strong growth next year from the fiscal impulse. It’s a story for 2027--and maybe beyond.
I still think the ECB will go to 1.5% this year. I expect two more cuts by the end of this year.
Will infrastructure and defence spending offset the uncertainty related to tariffs?
My own view is that the US administration will eventually have to acknowledge, and the markets will put the right pressure on the US at some point [on] tariffs [that they consider] as too high, like the 50% tariff on steel and aluminium. It would be prudent not to assume that trade tension will subside quickly. I don’t believe it will be prudent.
Second, on the fiscal side--defence and in Germany, infrastructure--it will take Germany quite some time to raise expenditure because of [internal] constraints. Initially, some of that defence expenditure will go outside of Europe. It’s not easy for Germany to suddenly raise that much defence expenditure and spend money on its own defence industry.
If I look at fiscal plans across the EU, let’s just stay with the large countries: France, Italy, and Spain. I don’t see any aggressive fiscal expansion plans, even though the European Commission has allowed flexibility in the fiscal escape clause as part of the €650bn Rearm Europe plan.
Some European countries have submitted their budget plans with some allowance for using that, but we don’t know whether they will deliver that spending. We’re not going to see anything like €650bn over the next three to four years.
If you look at the commission’s latest forecast, which looks at the fiscal stance for the euro areas, it says that the fiscal stance is going to be neutral, which means that Germany’s expansionary stance is offset by some other negatives next year.
[The ECB] is saying, on the one hand, tariffs and trade put downward pressure on growth, but then it could be offset by German fiscal [accommodation]. I don’t see that, because German fiscal expenditures are just for Germany. It’s not going to have an effect on other countries. Historically, German spillover effects are very limited.
What’s your expectation on long-term interest rates (10 years) in Europe?
One must worry about public debt levels in advanced economies. [Indebtedness] is generally quite high. Not in Germany. It will rise on the back of this fiscal expansion. We could end up, in five years’ time, going from 60% debt-to-GDP to 75%.
There is, in this global environment, very strong demand for German debt… given what’s happening in the US. [Investors] are attracted to European fixed income, and compared to the last 10 years, German yields are now attractive. They’re giving you a reasonable return.
It may take a while, but France will have to consolidate because debt levels are rising. A political kind of resolution must come first. It will have to address its fiscal issues because they are way above their [own] targets or the Brussels recommendations. France always takes time.
Spain and Portugal are converging very strongly. Spain’s 10-year yields are below France’s. Italy overperformed fiscally last year. It’s going through a good period.
Any other factors to consider?
Demand for financing from the markets typically comes from investment, which is very much driven by demographics and productivity. Investments in Europe have been very low. So, there isn’t a huge demand for financing from private investment. [Also], if I just look at aging demographics and productivity, then I don’t see a risk of higher interest rates in Europe. We’ll see a bit of a turnaround in Germany now with infrastructure spending, but it’s small.
A strong demographic may be one of the reasons why the US has recently avoided a recession. How will that develop in Europe?
Given what happened in 2015-2016 and the large inflow of immigrants from various conflict countries, there’s a big backlash against immigration. It explains Brexit. It explains political change in Germany with regard to the AFD (Alternative für Deutschland), France, and also Poland and Hungary.
The promise for Europe is whether it will follow the recommendations in the Letta report, the Draghi report, and reforms.
Will China succeed in forcing president Trump to back down on tariffs thanks to behind-the-scenes threats to continue to sell US treasury bonds and by imposing cuts in the supply of rare earth to the US?
I don’t know how long it’s going to take. But at some point, tariffs will settle down [at levels] higher than when Trump started [his announcements in April 2025] for China, but lower than the current average tariff, standing at around 45% to 50%. You’ve got 20% because of fentanyl and then [a general] 30% agreement, 50% on steel and aluminium. It’s a complicated average.
Not much better than 45%?
It’s the fentanyl that's hard to predict, because that could drop quite a lot… [Overall] I think tariffs will stay high on China--higher than, say, eventually the European Union or the UK. But I think tariffs are here to stay, because that is very strongly in the Trump team’s ideology.
Despite the adverse economic impacts on the US?
Tariffs are far more adverse for growth in the US and globally than they are for inflation. Inflation is going to be a temporary problem. It will look ugly because the price level rises and then growth will slow down, [resulting in] lower inflation.
[The Federal Reserve] is expecting tariffs to raise prices so it can't move yet… Tariffs will affect growth, and the Fed will move. I think the Fed will cut three times this year.