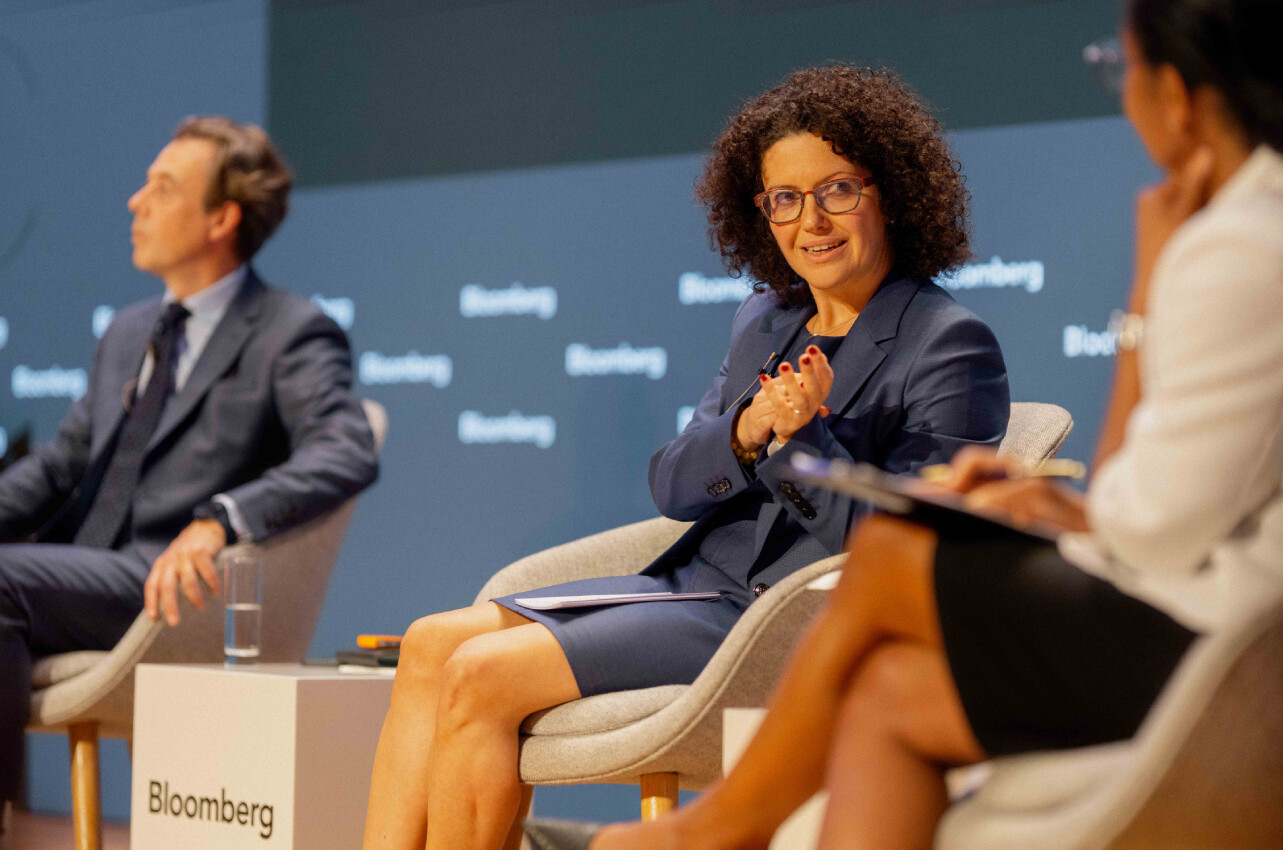
On your blog and during your speech at the Bloomberg Summit, you described a ‘two-way crowding-out effect’ in which governments and the private sector compete for the same savings. How does this competition drive up long-term interest rates?

Is this trend evident on a broad scale, or can it be quantified precisely?
“This is very clearly evident in the pricing and yields of government bonds, whether in the United States for 10- and 30-year maturities or in Europe. Long-term rates are currently much higher than inflation expectations suggest. If we look at inflation expectations over the next two or three years, we can assume that, thanks to the European Central Bank’s actions, inflation will return to normal. These rises in long-term rates therefore stem from a phenomenon far broader than mere economic shocks driven by inflation.
We are currently witnessing a fundamental transformation of the capital markets, driven by immense demand to attract savings. There are good reasons for this, but it comes at a price. In addition to the hyperscalers, there are the funding needs of social security schemes – such as US Medicare or healthcare systems in Europe. These are structural factors: the population is ageing, and the proportion of baby boomers is generating a growing need for healthcare, the costs of which are rising. Then there is defence, where governments must take on debt to rearm. Or the ecological and environmental transition.
As the Chinese proverb says: ‘The person who tied the bell round the tiger’s neck must be the one to remove it’.

In the private sector, hyperscalers must fund their development and research into artificial intelligence. But businesses themselves – whether banks or those in the real economy – must commit to massive capital expenditure and take on debt in order to equip themselves and implement AI. Finally, we must not overlook the issue of onshoring: the investments required to relocate businesses and reduce our dependence, particularly on China.
When it comes to seeking stable, long-term funding, everyone is competing for the same pool of savings. This is directly reflected in the pricing demanded for these maturities, for both sovereign debt and corporate credit. At present, this debt remains absorbable, even though we have seen some strains in the high-yield segment. But the key question remains: for how long, and will it be sustainable?
AAA-rated sovereign bonds are often regarded as risk-free assets, but this does not necessarily protect retail investors. Should we now analyse a country’s finances in the same way as we analyse those of a company?
“Public debt has never been without risk, as evidenced by the numerous defaults throughout economic history. The sustainability of public finances must be analysed in the light of specific indicators: interest rates, nominal growth and the country’s primary balance.
At present, we are seeing a marked widening of spreads for the most vulnerable countries within the eurozone. Investors are demanding a risk premium and a higher return on securities considered to be the most vulnerable. This is a market reality. Governments have a responsibility to take action to address these concerns. Refusing to face up to this reality would constitute a serious error of judgement, which, in our line of work as private bankers, would result in poor market analysis or even poor asset allocation.
Regardless of political or electoral upheavals, the key lies in the ability to set out a credible fiscal path and implement it consistently, signalling a strong commitment to deficit reduction. Even if the road ahead may be a long one for some countries, we must make a start. A strong ‘whatever it takes’ commitment – but this time driven by a government rather than a central bank – would make a real difference to investors and help to bring down this risk premium. As the Chinese proverb says: ‘He who tied the bell round the tiger’s neck must be the one to remove it’. Governments are masters of their own destiny; monetary policy can help, but it will not remove the bell for them.
As far as the financial markets are concerned, the message to governments is crystal clear: debt deemed excessive is penalised.
Politicians are making more and more pledges, but problems with budget implementation are a recurring issue. Is there not a disconnect between rhetoric and reality?
“I am not a politician and it is not my role to comment on political matters. However, as far as the financial markets are concerned, the message to governments is crystal clear: debt deemed excessive is penalised.
This observation no longer applies solely to the usual targets, but also affects the United States. Since US debt crossed the $40,000 billion threshold, the markets have reacted and yields on Treasury bills have sent a direct signal to the administration. It is for this reason that the US Treasury has had to announce a doubling of Treasury bill buybacks: not to inject liquidity, but to force yields back to acceptable levels. The ultimate responsibility therefore clearly remains with governments.
Many analysts are talking about a bubble in the artificial intelligence sector, criticising investment levels that are out of proportion to the recurring revenue generated. What indicators can be used to assess the true profitability of these projects and to distinguish between different technology companies?
“The monetisation of these capital expenditure programmes is a key driver of market dynamics. In practical terms, the key factor to monitor is cash flow generation. If the ability to generate cash flow is no longer sufficient to cope with current and planned capital expenditure levels, corrections will inevitably occur, both operationally and in terms of valuations.
Valuations are not driven simply by a rise in multiples, but by expectations of extremely high earnings. This euphoria is fuelling substantial net investment flows into the United States and underpinning growth. However, as soon as this earnings potential begins to wane, difficulties will arise.
Companies operating in the field of artificial intelligence are closely interconnected and may use highly sophisticated financing structures, particularly off-balance-sheet arrangements. This is characteristic of capital-intensive industries, which is not a problem in itself. However, the sector’s overall interconnectedness creates systemic risk. Like a house of cards, if the weakest link gives way, the whole structure could collapse. We are therefore monitoring credit risk metrics very closely. This vulnerability will first manifest itself in the credit market, which is why we are rigorously tracking the CDS (credit default swaps) and credit spreads of these issuers.”