Simply switching apps won’t be enough. Every Payconiq user will need to download Wero, link their bank account and create a new profile before the 1 October. On that date, Payconiq will cease operations in Luxembourg.
Wero has been officially available since 1 September. Its launch was announced on Wednesday 2 September by the European Payments Initiative (EPI), the company owned by European banks and payment service providers that is developing the service. Five Luxembourg banks are taking part in the launch: Spuerkeess, BGL BNP Paribas, Banque Internationale à Luxembourg, Banque Raiffeisen and Post Luxembourg. Others, such as Banque de Luxembourg, are expected to join the scheme shortly.
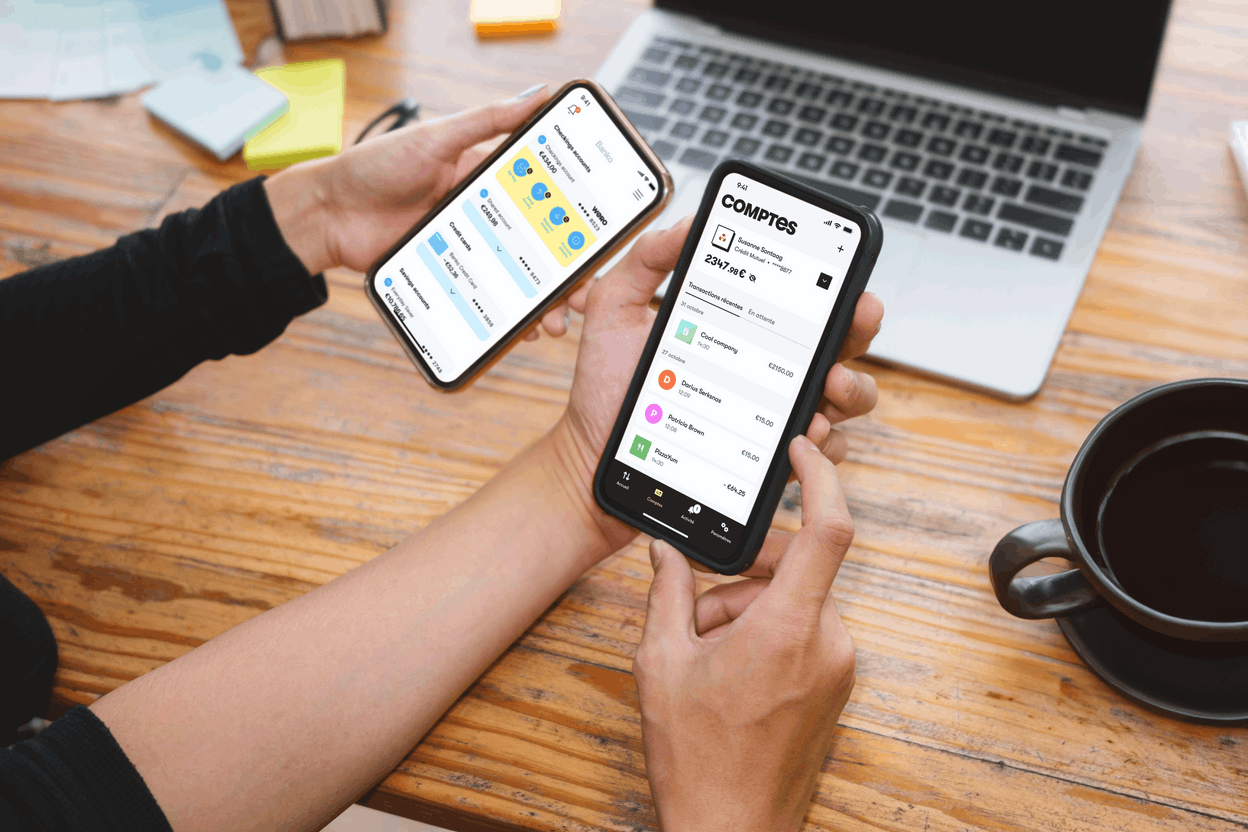
For the user, the principle is similar to Payconiq. Wero allows you to pay a retailer or settle a bill by scanning a QR code, as well as to send, request and receive money. The main difference lies behind the scenes: the payment takes the form of an instant transfer between two bank accounts. It does not go through a Visa or Mastercard, nor does it use the Apple Pay or Google Pay systems.
A bank transfer by reference number or email
The money should arrive in under 10 seconds. The service operates 24 hours a day, seven days a week, including Sundays and public holidays. You do not need to know the recipient’s Iban: their phone number, email address or a QR code can be used to find their Wero profile. The email address, in particular, offers an additional option for cross-border workers who may already have linked their phone number to a foreign bank account.
To get started, users must check that their bank offers the service, then download the Wero app for free from the App Store or Google Play. The app is also available from several international versions of these app stores. Depending on the bank, users can then log in to their account via their usual banking app or via LuxTrust. It is essential to have a phone lock enabled – whether a passcode, fingerprint or facial recognition.
This registration is not simply an automatic migration. Payconiq data and profiles are not transferred to Wero as they stand. A routine check is carried out when the account is opened, for both private individuals and businesses. Wero’s FAQs state that some accounts may be temporarily restricted whilst this verification is taking place, particularly during periods of high demand.
The transition will take place in two stages. Until 30 September, Payconiq and Wero will operate in parallel. The Wero app can scan the new Wero codes as well as eligible Payconiq codes used on bills and in shops. The reverse is not true: Payconiq cannot scan a Wero code. From 1 October, only the Wero app will remain available. However, it will continue to read Payconiq codes on invoices and in shops until 31 December. Personal Payconiq codes and certain codes used for online shopping are not supported. From 1 January 2027, only Wero codes will work.
10% of users were onboarded on the first day
This timetable directly affects the 300,000 Payconiq users in Luxembourg prior to the migration. At the launch, the EPI stated that nearly 10% of the Luxembourg community had already downloaded and set up Wero within a single day. However, the exact scope of this percentage – whether it refers to the general population, eligible bank customers or Payconiq users – still needs to be clarified in order to convert this rate into a figure for the number of users. Some banks acknowledge onboarding issues, albeit on a very small scale, which seems quite normal at the time of a launch.
The main change comes into play when a payment crosses a border. Payconiq was initially a Luxembourg-based solution. Wero allows users to send money to customers of participating banks in Belgium, France and Germany. However, this does not automatically mean that payments can be made to any account in these countries: both the bank and the recipient must also be connected to Wero.
A solution for cross-border workers too
The network continues to expand. According to the EPI, Wero had 56 million registered users in France, Germany and Belgium in July 2026, compared with 14 million users and 8 million transactions recorded at the time of its first review in November 2024. The Netherlands has begun migrating its iDeal system, whilst Austrian banks have joined the project. In spring 2026, the EPI claimed to have 45 European members. More importantly, it accounted for 64% of payments in Europe. Alongside other existing solutions in Spain, Portugal and the Nordic countries, this new generation of technology could finally ‘unite’ Europeans.
A cross-border worker can link several bank accounts from different countries to the Wero app, provided that the relevant banks are part of the service. This option is not necessarily available when Wero is directly integrated into a bank’s app: in such cases, only accounts accessible via that app can be used.
The telephone number or email address acts as an alias for receiving money. The same alias cannot be linked to two accounts at the same time. Anyone who is already using their number with a French bank will therefore need to unlink it before assigning it to their Luxembourg account, or choose their email address for this second account. However, no alias is required simply to send money.
Access to the address book remains optional. It allows the app to identify contacts already saved, but the user can enter a number or email address manually. Before confirming, Wero displays the recipient’s details: these must be checked carefully, as an instant transfer made to the wrong person cannot be cancelled as easily as a payment request.
Free to use and a dedicated point of contact
Wero sets a general limit of 100 payments and 100 payment requests over a rolling seven-day period. The theoretical limit is €100,000 per payment. However, these limits do not guarantee that a customer will be able to transfer such an amount: each bank may impose a standard or individual limit that is much lower. The limit applicable to the bank account takes precedence.
The service is free for private individuals, but Wero does have access to data. EPI states that it does not have direct, permanent access to the bank account. The standalone app does, however, receive the information necessary to provide the service. Its own FAQs specify that it can access the account balance and transaction history for the last 90 days. This access does not apply in the same way when Wero is used within the bank’s app. According to EPI, confidential banking data and login credentials remain held by the bank. From a technological perspective, LuxHub has taken on the role of coordinating the additional layer between Luxembourg banks and converting identities into new codes shared between the banks to ensure a seamless user experience.
The point of contact also depends on how the service is used. When a customer accesses Wero via their bank’s app, they should contact their bank’s customer service department. In the standalone Wero app, a chat function allows users to contact support for help with installation, configuration or payment issues. If a phone is lost or stolen, the user can request that the service be uninstalled remotely.
Retailers will have to pay for access to the technology, under terms that challenge those of Visa and Mastercard, the various representatives have promised, without disclosing the rates offered by the American giants, as the solution will be repackaged as part of intermediary services, which will remain free to set their own terms.
Further steps to be planned
Wero does not yet replace all the functions of a bank card or digital wallet. EPI is gradually rolling out online payments, in-shop payments, refunds and transactions with businesses. Recurring subscriptions, loyalty schemes, contactless payments and the use of the European digital identity are included in its roadmap, but not all are available in Luxembourg at the time of launch, and no specific national timetable has been announced for each of them.
Nor does the app replace the future digital euro. Wero is a private solution owned by banking institutions and relies on existing accounts and commercial euros. The digital euro would be a central bank digital currency issued by the European Central Bank. EPI envisages eventually being able to integrate it into its portfolio, should the European project come to fruition.
The issue therefore goes beyond simply replacing Payconiq. The banks are seeking to establish a European infrastructure capable of operating across national borders and reducing their dependence on US payment networks.
For users in Luxembourg, this ambition begins with a much more immediate step: installing a new app before the 1stis October and check that their usual payment methods will continue to work. For the owner of the Bâtiself shops,