Despite overwhelming military superiority and the swift elimination of numerous senior regime officials, the Israeli-American coalition is facing fierce resistance from Iran. The blockade of maritime traffic in the Strait of Hormuz, imposed by the Iranian authorities, has triggered an unprecedented supply shock. By controlling this strategic chokepoint through which around a fifth of the world’s oil and liquefied natural gas supply passes, Tehran wields a powerful lever capable of threatening global economic stability. In addition to oil and gas, other trade flows are currently being disrupted, notably fertilisers, aluminium and helium, with direct consequences for prices and production chains.
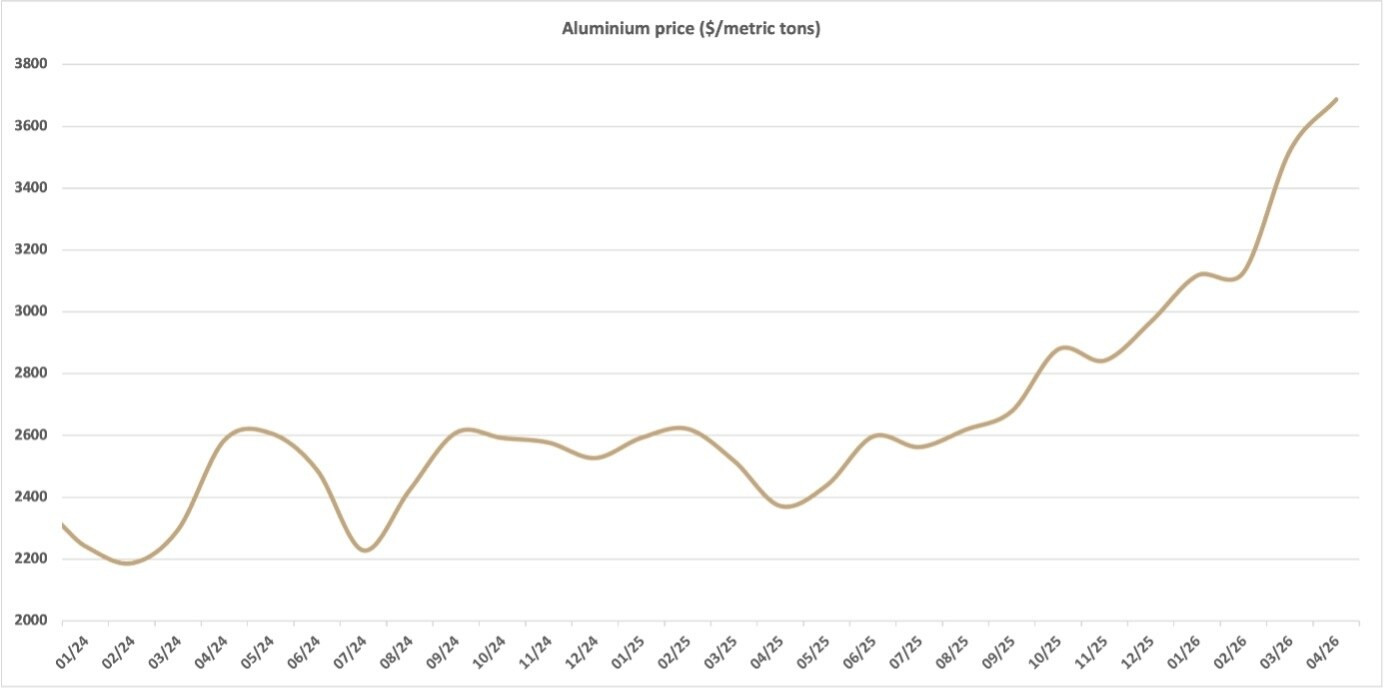
Aluminium price trends. (Source: Bloomberg, Banque de Luxembourg)
A very fragile ceasefire
The ceasefire agreement, valid for two weeks from 8 April, appears extremely fragile. Under Pakistan’s auspices, the first round of negotiations between the United States and Iran quickly ended in failure. The positions of the two sides are currently far apart. Iran’s attempts to impose a maritime toll for passage through the Strait, in violation of the principle of freedom of navigation, are causing particular tension. In response to this failure, Donald Trump has, once again, taken the world by surprise by ordering a US naval blockade of the Strait of Hormuz in an attempt to curtail Iran’s ability to fund its war effort through revenue from oil exports (amounting to some 2 million barrels a day destined for China).
The resumption of traffic in this area will inevitably be slow. The International Maritime Organisation estimates that around 3,000 ships are currently stranded in the Persian Gulf, awaiting authorisation to pass. Furthermore, it will take several months to normalise energy flows from the Middle East, given the significant damage sustained by various production sites, port infrastructure and refineries in the region.
Decline in leading indicators in the eurozone
As a net energy importer, the eurozone is economically highly vulnerable to an energy shock. We are seeing the first signs of an economic slowdown in the region, currently reflected mainly in sentiment surveys. The composite PMI, although still in expansionary territory, fell by 1.2 points in March following a sharp decline in the services sector (-1.6 points).
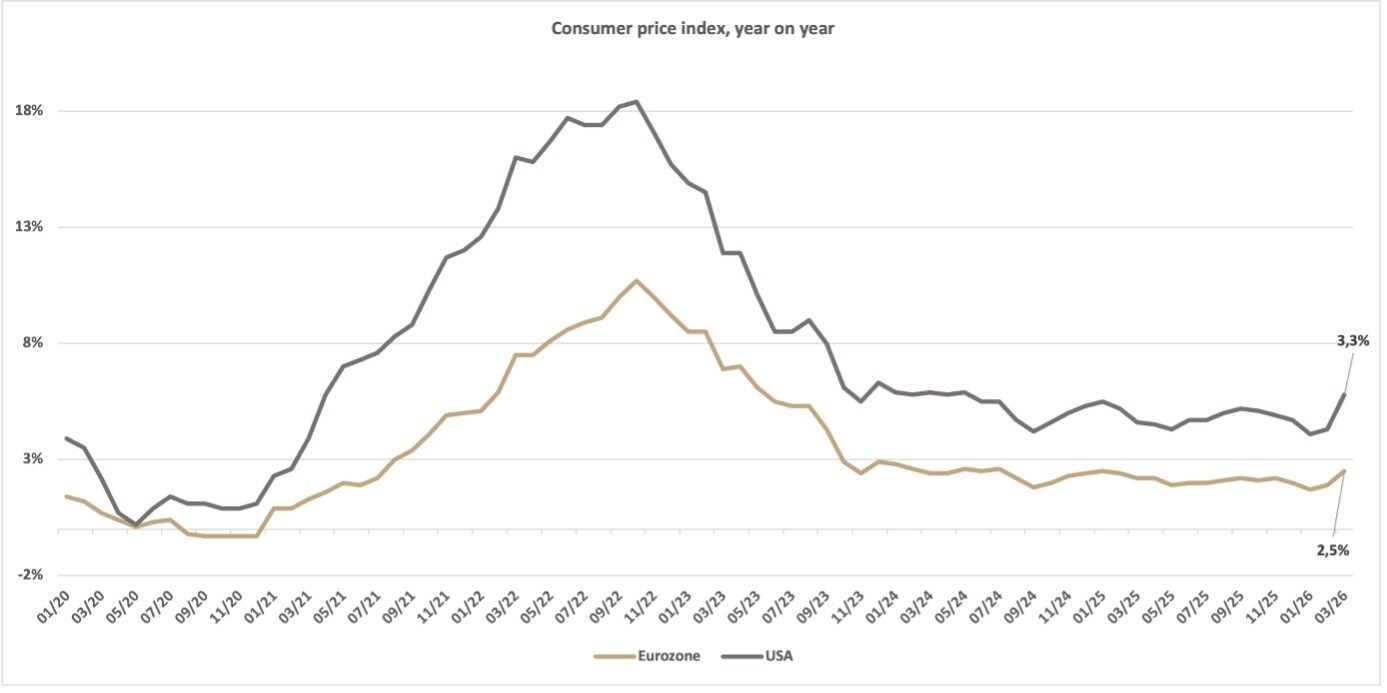
Consumer confidence has also fallen sharply, dropping by 4 points over the month—a significant decline—reflecting fears linked to geopolitical tensions and the resulting rise in inflationary pressures. These pressures are already clearly evident: the consumer price index in the eurozone accelerated sharply in March, rising by 2.5% year-on-year (compared with 1.9% the previous month), driven by energy prices, which rose by almost 5%. Inflation is expected to continue rising and exceed 3% in the coming months.
Monetary policy tightening expected in the eurozone
This combination of a deterioration in growth prospects and rising inflationary pressures in the eurozone is driving markets to anticipate a significant tightening of the European Central Bank’s (ECB) monetary policy by the end of 2026, marking a shift from the status quo that still prevailed at the end of 2025. They are currently forecasting nearly three rate rises by the end of the year, which appears aggressive and would push monetary policy into restrictive territory.
These rate rises, if implemented by the monetary authorities, will nevertheless have little impact on imported inflation. The ECB’s primary aim is to prevent inflation expectations from becoming “unanchored” and to limit second-round effects—a rise in non-energy prices in response to higher energy prices—particularly on wages. In this regard, the central bank’s wage monitoring tool sends a rather reassuring message, forecasting a 2.3% rise in negotiated wages in 2026, a sharp slowdown compared with the previous year. We cannot, however, rule out the possibility that the energy shock will influence upcoming wage negotiations.
A cut in the maximum rate is expected in the US towards the end of 2026
In the United States, the markets now expect no more than a single rate cut by the end of the year, despite economic momentum that appears to have moderated in recent months. For example, based on household spending figures for January and February, private consumption is currently showing sluggish growth (less than 1% on an annualised quarterly basis). Inflation is clearly accelerating (+3.3% in March), further complicating the task facing monetary authorities.
The Chair of the Federal Reserve (Fed) has, however, recently noted that the institution might not overreact as long as long-term inflation expectations remain firmly anchored.
Trends in household spending in the United States. (Source: Bloomberg, Banque de Luxembourg)
Resilient equity markets
Investors are still banking on a relatively swift resolution to the crisis in the Middle East. With the mid-term elections just around the corner, the political cost of this energy crisis could prove significant for the Trump administration. It would therefore be in the administration’s best interests not to drag the conflict out.
The economic cost will depend on the scale and duration of the supply shock caused by the closure of the Strait of Hormuz. Time is running out: there could be a shortage of certain refined products (such as kerosene or diesel).
Note: “We start a war when we want to, and we end it when we can” is a quote attributed to Machiavelli.