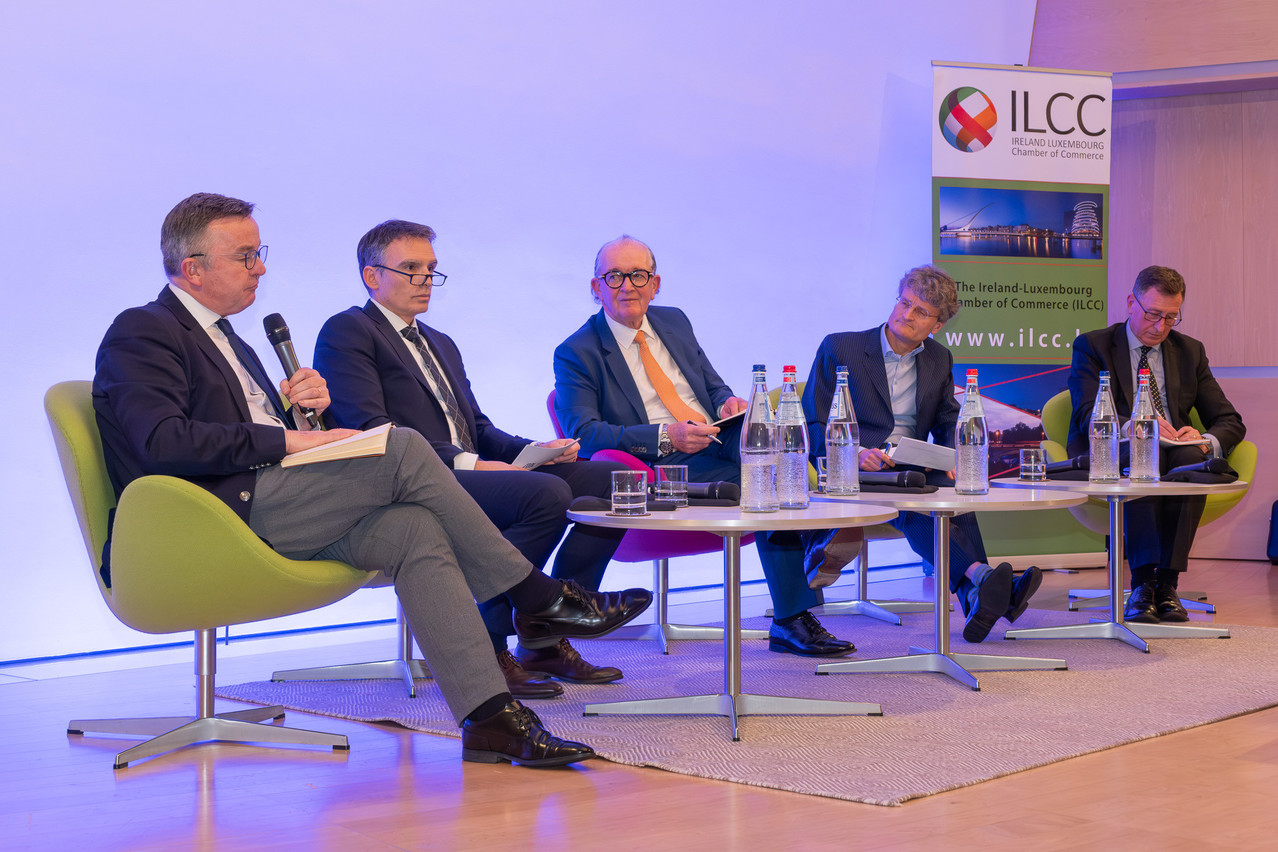
Luxembourg hosted a high-level event on 11 February devoted to the effectiveness of anti-money laundering (AML) and combating the financing of terrorism (CFT) measures and to know-your-customer (KYC) obligations, organised by the Ireland Luxembourg Chamber of Commerce at Banque de Luxembourg. More than 100 professionals from the banking, financial and regulatory sectors participated in the discussions, according to an ILCC summary.
The panel included the director of Business Decisions Limited, Richard Meads, the CEO of Banking and Payments Federation Ireland and former Irish minister, Brian Hayes, the CEO of the Luxembourg Bankers' Association, 
According to the data discussed at the conference, illicit financial flows are estimated to account for more than 2% of global GDP. They are associated with serious offences such as drug trafficking, human trafficking, fraud and terrorism. While the legitimacy of public action against these phenomena was not contested, several speakers felt that the current systems do not necessarily produce the expected results in terms of overall effectiveness.
A central point of the discussions was the current regulatory model, which gives private financial institutions extensive responsibility for information gathering and compliance. Institutions bear significant legal and reputational risks, with fines that can exceed one billion dollars in some cases, as well as global compliance costs estimated at more than 180 billion dollars a year. At the same time, it was pointed out that less than 1% of illicit funds would be recovered globally, fuelling debate about the cost-effectiveness of the system.
The indirect consequences of tighter regulation
Speakers also highlighted several indirect effects of increasing regulatory requirements. These include the "de-banking" of certain customers deemed to be unprofitable or high-risk, the obstacles encountered by entrepreneurs, start-ups and small businesses in accessing financial services, and a reduction in access to regulated services for certain vulnerable groups. Constraints on innovation were also mentioned, in a context where new forms of financial crime are emerging, including fraud exploiting artificial intelligence, extortion via deepfakes or illicit lending networks, the statement added.
At the end of the discussions, a consensus emerged on the need for a critical reassessment of the AML/CFT and KYC arrangements. The participants called for an improvement in the effectiveness of the measures, a reduction in negative externalities and a better alignment between the objectives of the public authorities and the economic incentives of the private sector. They also stressed the importance of formal analysis of potential systemic failures, increased vigilance against emerging criminal threats and more efficient use of compliance resources to maximise the benefit to society.