Sylvain Barrette: My first question is from a 60,000-foot view: why are so many people worried about an AI bubble?
Alexandre Drabowicz: There is massive polarisation regarding AI. On one side, believers think we are at the start of an unprecedented revolution that will last at least a decade, driven by productivity gains resulting in disinflationary effects. We are in that camp. We believe US potential growth could shift from 2% to 3% due to these gains. On the other side, pessimists predict the end of the world. Interestingly, the “bubble” concern is mostly European. In the US, the debate is about how far the impact and investment can go, while in Asia, they see themselves as a real alternative to the US.
Tanguy Kamp: People are afraid because of the massive changes in 2025. Companies like Oracle, Google, and Meta are entering the market with enormous debt issuances. Investors worry whether companies that spend so much free cash flow to service debt can maintain their previous cash flow levels. While private valuations for firms like OpenAI and Anthropic are astronomical, public market valuations still seem justifiable. There is also a “mismatch” concern: firms are taking on 10-to-20-year debt to build data centres filled with chips that might be obsolete in 3 or 4 years.
Don’t you think whether the large US deficits have contributed to higher GDP?
T.K.: US debt is at 120% of GDP. I compare this to post-Napoleonic Britain in 1815, where debt-to-GDP was 200%. The Industrial Revolution followed, generating productivity gains of 1% to 2% per year, which caused the debt ratio to fall steadily until the end of the 19th century. Trump’s team often references the 1870–1900 period—high growth, no central bank, and no inflation—as a positive reference for financial markets. We believe AI is a similar revolution.
The US retail investor is the #1 investor in the tech sector. If it collapses, the impact on US consumption would be colossal
If a bubble burst, would the impact be more damaging than the Global Financial Crisis (GFC)?
T.K.: The GFC was a banking crisis; the “plumbing” of the system was clogged. Today, European and US banks are heavily regulated and do not have the same bad debt problems. If there is a problem today, it is a valuation issue in specific sectors, which I don't believe is systemic.
A.D.: A key difference is that we are currently in a rate-cutting cycle. Most big crises happen when central banks are tightening credit. However, the real risk today is the “wealth effect.” Over the last three years, US wealth creation—largely from tech stocks—reached $20trn. That is two-thirds of US GDP. The US retail investor is the #1 investor in the tech sector. If it collapses, the impact on US consumption would be colossal.
Beyond valuations, leverage is another concern. Margin debt costs reached a record in the US, and the number of leveraged ETFs has grown from 100 in 2012 to 700 today (see chart 1), some with 4x leverage (S&P 500). Could this amplify a market downturn?
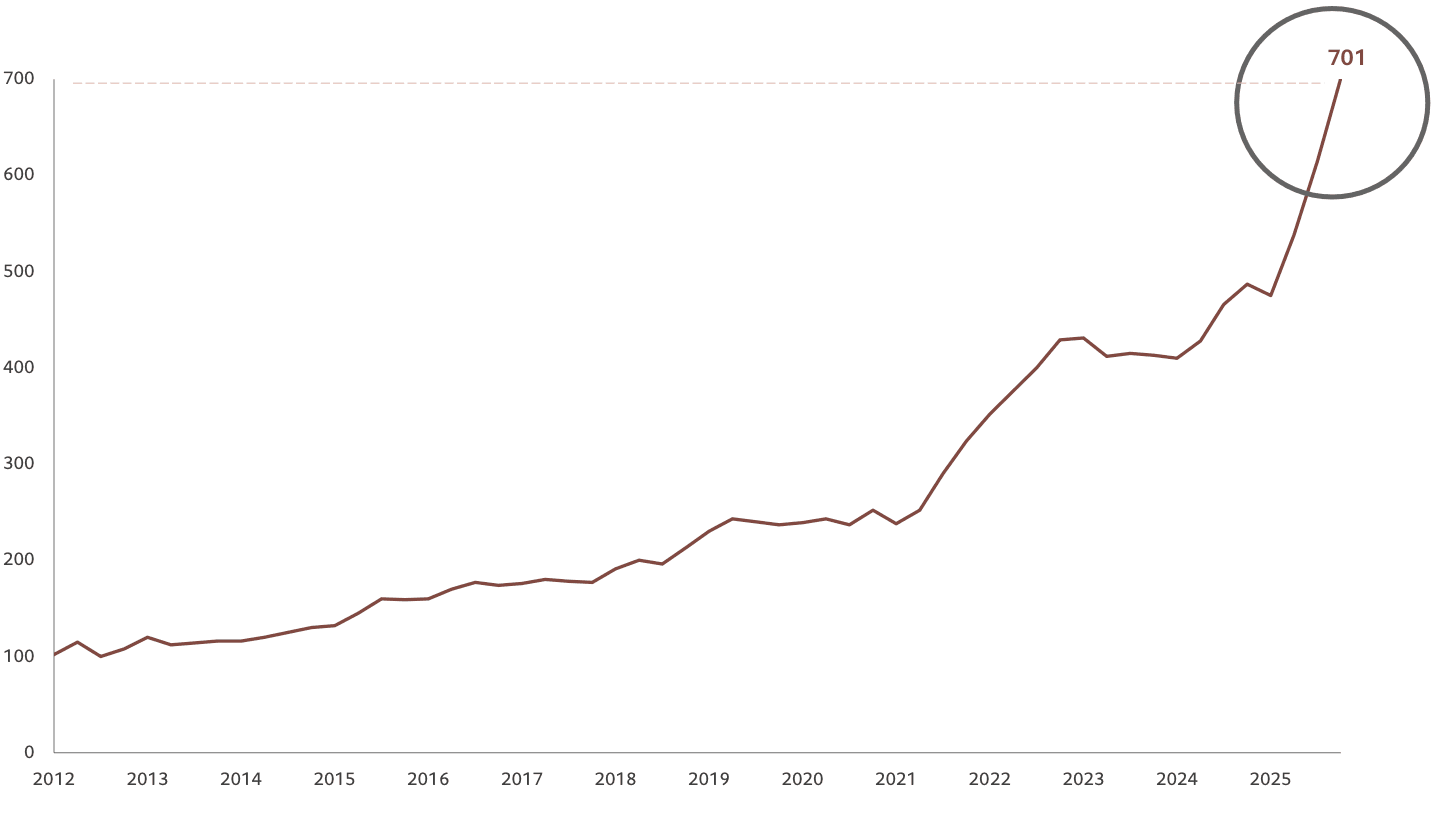
Chart 1: The boom in leveraged ETFs and their growing use by retail investors (number of ETFs) Sources: BofA Global Investment Strategy, EPFR, Pictet Asset Management; 31 October 2025
T.K.: We saw this recently with the correction in gold and silver after investors accumulated these metals while fearing they would miss an opportunity (FOMO).
A.D.: Silver, in particular, became a "retail mascot" on Reddit, similar to GameStop in 2020. When silver prices dropped, those using 3x leverage were “cleaned out” as the instruments lost 60%. These products were largely driven by retail investors. Their institutional counterparts are absent. The retail cohort can be more powerful than institutional investors nowadays.
T.K.: If we see a trend reversal, at some point we’ll have to go back to fundamentals. And what are the fundamentals? We’ll look at the free cash flow they generate from their core business — nothing to see there.
A.D.: Regarding the trigger for a broader reversal, the “buy the dip” strategy has worked so far. Our biggest macro risk is the economy “running hot.” If long-term US rates (the 10-year Treasury) drift away and go beyond 5%, that would be a “danger zone” for stock valuations and multiples.
T.K.: What Buffett always says in response to that question is, 'If you had a crystal ball and could know one economic indicator before everyone else, which one would it be?' The U.S. 10-year.
Energy demand introduces a different constraint. Are we approaching a breaking point regarding AI energy demand? Could there be a clash with retail consumers over electricity prices?
T.K.: Tech giants are now competing with the US public for power. Because utilities are state-controlled with capped returns, the risk is increased regulation. Companies like Microsoft are already trying to bypass the public grid by signing deals for independent power. The Trump administration will likely push to increase gas and oil production because US electricity demand is expected to rise by over 50% by 2035. You cannot meet that demand solely with solar, wind, or new nuclear plants, which take 10 years to build. Fossil fuels will remain at the forefront.
“Circular financing” is akin to one person digging a hole, another filling it, and they both pay each other €5 for the jobs. The only person making money is the one selling the shovel. AI investments are believed to have reached $300bn in 2025, but revenues are only around $60bn. Does the cash have to come from outside the ecosystem for it to be prosperous?
A.D.: Google is a great counterexample. They just announced $400bn in annual revenues for the first time. When they say they will spend $180bn on capex next year, they can self-fund it. They see real demand and profitability, so for them, it is a profitable investment, not just circularity.
T.K.: OpenAI is different. They are burning so much cash that Sam Altman has had to pivot toward putting ads on ChatGPT, despite previously saying he wouldn't. It can’t be a bottomless pit.
Only 5% of OpenAI users pay for a subscription. They hope to reach 8% by 2030, with revenue growing from $13bn to $200bn. As a point of comparison, Netflix generates $45bn in revenue. But the average American already spends $1,080 per year on subscriptions. Isn't there a subscription overload?
T.K.: It looks like a race toward an oligopoly, like Netflix’s dominance in streaming. As markets shrink, pricing power grows, and users stay subscribed. Major AI firms aim to become near-monopolies within 10 years to gain strong pricing power—though it’s unclear who will succeed.
A.D.: The real monetisation will come from the corporate sector. That is where Google makes its money. One person I spoke to pays $50 to $70 per lead via Instagram and YouTube. If OpenAI can tap into corporate revenues, the potential is enormous.
Michael Burry, in the Big Short novel, noted that companies like Meta, Microsoft and Google have extended the depreciation life of their hardware from 3 years to 6 years. Given that chips have a lifespan of 3 years or less, isn't this "understating depreciation" to boost earnings? Could that become an accounting scandal?
T.K.: This mismatch between the asset life and the financing is a real market concern. Financing something over 10 years that is obsolete in 3 years is a major question mark.
While the hardware cycle is fast, we also see massive efficiency gains. Future chips might consume half the electricity while being twice as fast. This might mean we are overestimating future electricity demand.
What about the software sector? Is the valuation justified?
A.D.: While much of the debate focuses on an AI bubble, the narrative may have overlooked the brewing bubble on data centres and software. The latter segment has lost practically 30% of its valuation recently. We saw a “deflating” of a small bubble with Oracle. There may have been indiscriminate selling in software, as everything fell at the same time. For instance, cybersecurity stocks plunged, even though it’s unclear how they would be significantly disrupted by Anthropic’s Claude. It is healthy that the market penalises companies when they spend more than they earn.
T.K.: These stocks were expensive, so expectations were high. When valuations are stretched, even small earnings disappointments—like SAP’s—lead to immediate market punishment.
Despite this, there is still a massive appetite for debt; Google’s recent bond issuance had the largest order book ever seen, and Oracle’s $25bn issuance saw $120bn in demand. Investors aren't afraid of not being repaid; they just want a higher premium for longer maturities.
Does the crypto correction pose a systemic risk?
T.K.: I don’t see a contagion effect. It is an isolated wealth effect issue. Bitcoin doesn't generate anything. While gold has a 5,000-year track record as a currency, Bitcoin only has 15 years.
A.D.: Even at $70,000, some argue that Bitcoin is “$70,000 too expensive.” We haven’t moved into cryptos for our portfolios because of regulation and access issues. Ironically, the more you regulate Bitcoin, the less utility it has as an “alternative.”