“The year 2025 was marked by a growing de-dollarisation, or ‘debasement trade,’ and a geographical rotation that initially benefited European equities,” said Christopher Dembik, senior investment advisor at Pictet Asset Management, during a presentation in Luxembourg on 3 February 2026. A primary concern was the high level of market leverage, which was deemed a more significant risk than geopolitics or central bank balance sheets.
By 2025, hedge funds accounted for approximately 20% of equity market trading volumes, with an average leverage of 3x (see chart 1), though macro hedge funds reached levels as high as 9x.
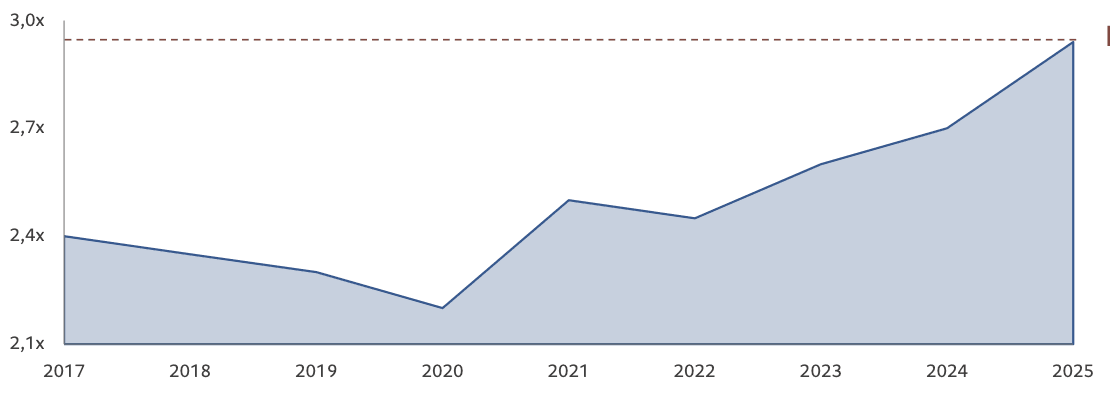
Chart 1: Average leverage of hedge funds since 2017. The indicator reached 2.98x in 2024. Source: JP Morgan, Goldman Sachs, Pictet Asset Management, November 2025. *Based on OFR data as of March 31, 2025. In the case of macro strategies implemented by hedge funds, leverage levels are generally much higher than the average level.
First victims of leverage in 2026
Combined with profit-taking and the anticipated appointment of Kevin Warsh as the new Fed chairman of the US Federal Reserve, leverage contributed to significant market malfunctions, most notably the silver flash crash on 30 January 2026. During this event, silver prices plummeted by 40% within hours. This collapse was exacerbated by leveraged ETFs. They continued to trade while the spot market was paused, leading to a panic-driven liquidation of positions.
Other victims may be closer to home
Such risks are not limited to precious metals. Dembik warned that American households had also significantly increased their use of leveraged ETFs (see chart 2) in the equity markets, creating “a contagion risk that could spread to Europe.” However, he assessed that these instruments were “unlikely to create a trend,” though they could amplify existing ones.
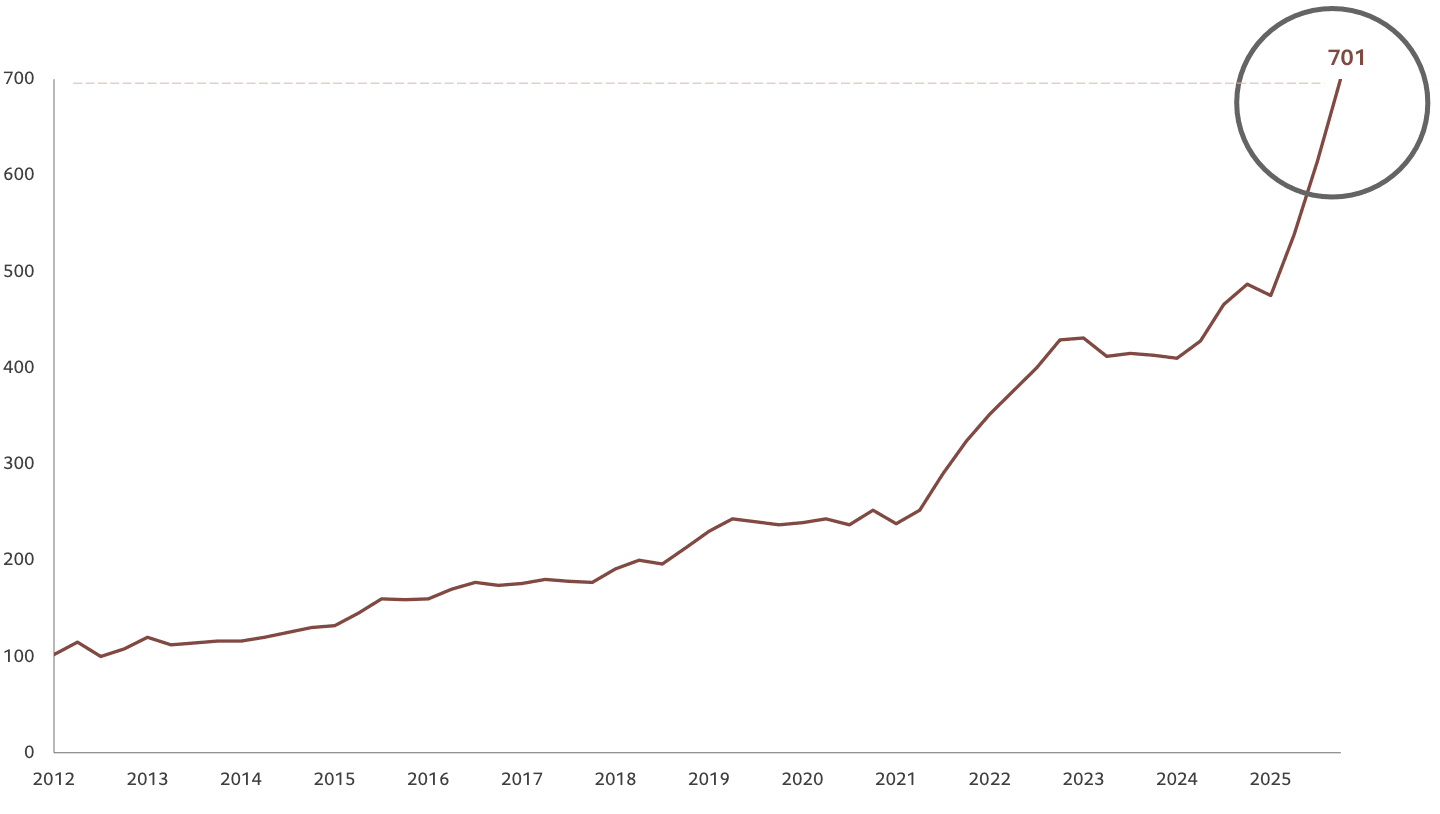
Chart 2: The boom in leveraged ETFs and their growing use by retail investors (number of ETFs) Source: BofA Global Investment Strategy, EPFR , Pictet Asset Management, 31 October 2025
The US continues to economically outperform Europe
While early 2025 forecasts suggested European growth might exceed that of the US, the reality proved different, noted Dembik. Eurozone growth reached approximately 1.2%, whereas the US achieved between 2.4% and 2.5%, both figures close to their respective potential growth rate.
US inflation, currently at 2.7%, also remains manageable, fluctuating between 2.5% and 3.0%. This US exceptionalism endures due to intensive investment in the AI “innovation super-cycle,” boosting productivity. Between 2019 and 2024, he noted that cumulative productivity in the US rose by nearly 10%, compared to just 2.4% in the Eurozone.
Fed’s orthodoxy is maintained
Pictet continues to expect two US Federal Reserve rate cuts of 25 basis points starting in March 2026, totalling 50 basis points for the year. The objective is to support the property market, which has proven more resilient than initially expected.
According to Dembik, Kevin Warsh is widely perceived as a pragmatic candidate to succeed Jerome Powell. The yet-to-be-confirmed new central banker would be unlikely to accelerate the reduction of the Fed’s balance sheet aggressively, given the risk of destabilising markets amid elevated leverage.
“Extreme selectivity” in Europe is paramount
While southern European banks, particularly in Italy, remained attractive with returns on equity (ROE) exceeding 20%, Dembik remarked that they faced political risks, such as potential bans on dividend payments, “a development that could spread to other countries.“
Meanwhile, the “strategic awakening” of European industry remained elusive, as innovative firms often lacked the scale of their American counterparts and were frequently acquired or moving to the US. Consequently, “these innovative industrial sectors that are completely absent.”
Share buybacks or the road to higher valuation
“Around 80% of trading volume is generated by algorithms tracking flows, which are structurally driven by share buybacks and, in turn, equity performance in the US,” stated Dembik, citing a Goldman Sachs study.
Japan has, therefore, emerged as a focal point for investors amid a sharp increase in corporate share buybacks. Dembik pointed to Mitsubishi’s announcement of a Yen1trn (approximately $5.4bn) buyback, which helped drive its share price up by 60% in 2025.
[Pictet targets] companies that are highly profitable, with business models that work even without AI
It is worth noting, however, that despite interest-rate hikes, the Japanese yen remains at 35-year lows against both the dollar and the euro. “We are indeed seeing a long-term weakening trend in the yen,” said Dembik.
Sub-sectors to watch
Finally, Dembik highlighted a supercycle in commodities, particularly gold, silver and copper, driven by continuous central bank demand and an imbalance between limited supply and rising demand from institutional and retail investors for precious metals. “Supply sets the price of oil, while demand sets the price of commodities.”
In the technology sector, Pictet’s focus moved beyond data centres toward AI-driven robotics and distribution platforms like Amazon, which holds around $60bn in available cash. More generally, Dembik stressed that Pictet targets “companies that are highly profitable, with business models that work even without AI.”
The energy transition also remained a key theme, specifically US solar energy with a production cost that Dembik estimated at $35, while crude oil stands currently at $63 (WTI). He stressed that the industry benefits from substantial subsidies and protectionist laws ensuring a monopoly for domestic actors until 2033.