According to Pitchbook, PE exits in 2025 in Europe's financial services industry hit a record high (77 exits totalling €31.3bn; see graph below) as companies were able to finally sell off long-held assets due to improving market circumstances. In terms of pace and value, the industry is expected to have its best year ever.
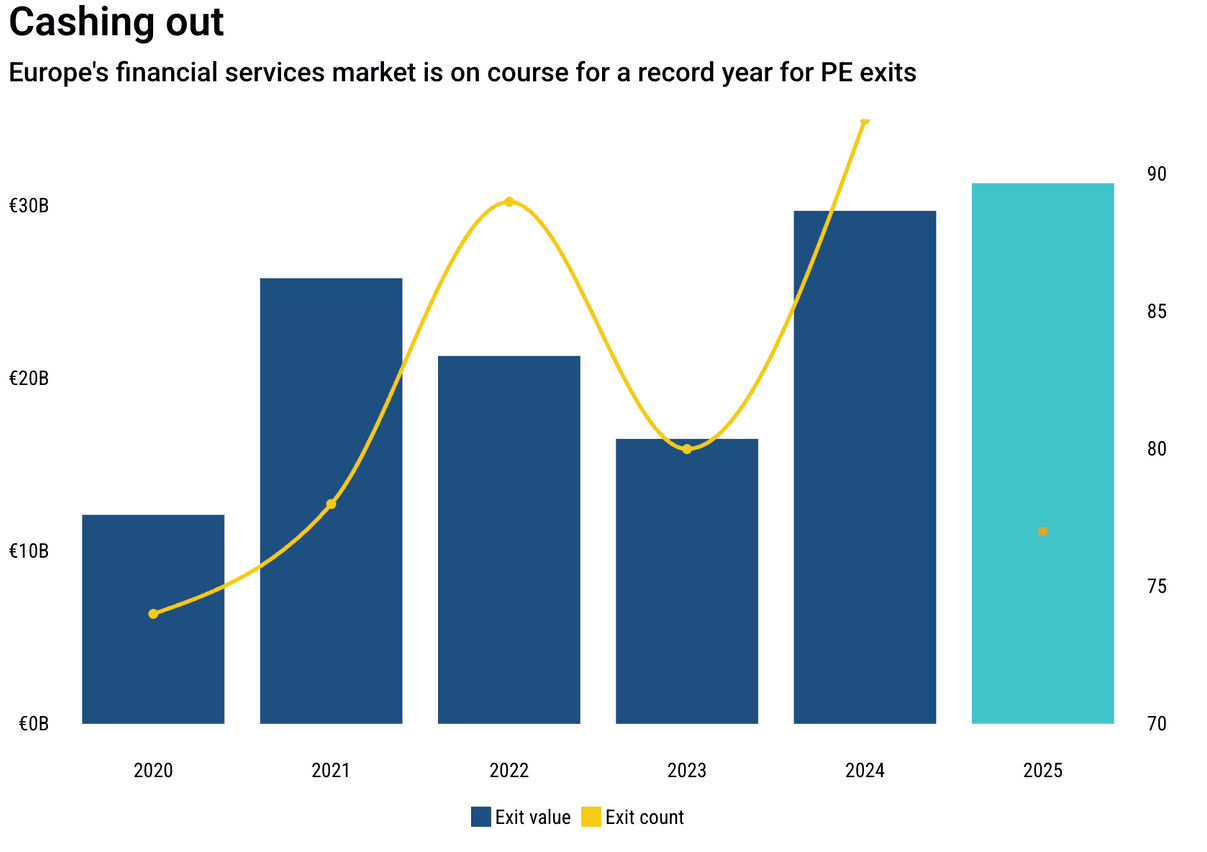
PE exits are gradually showing positive signs. Data as of 23 October 2025 Pitchbook
PE firms have increasingly exited activity to crystallise returns and satisfy limited partners (LPs) liquidity needs. The financial services sector is a prime target, boosted by regulatory tailwinds in both the EU and UK. New EU rules (CRR3/Danish Compromise) reduce the capital banks must hold when acquiring insurers or asset managers, encouraging more deals. The UK is also supporting growth by simplifying reporting and updating the Solvency II regime.
Following up on the report, we asked three questions to Nicolas Moura, senior EMEA private capital analyst at Pitchbook:
Sylvain Barrette: Does it mean that GPs made significant pricing concessions to get the sales done? Can you give some details?
Nicolas Moura: Pricing and concessions depend on the vintage year of the investment. We have found that general partners (GPs) who bought PE assets at the height of the bull market in 2020 and 2021 are finding it difficult to sell those in the current market environment. However, we are still seeing other assets transact at good multiples and GPs exiting their investments from other vintages.
It seems that the large volume is the result of fewer but larger deals in 2025? Which are the deals distorting the results?
This is partially true; we have seen a return of megadeals, which do account for about a third of deal value YTD. However, the return of these megadeals is positive for the market sentiment, as it suggests that market conditions are improving and financing of deals is easing thanks to lower interest rates. Below is a list of the top 20 deals in Europe as of the end of Q3.
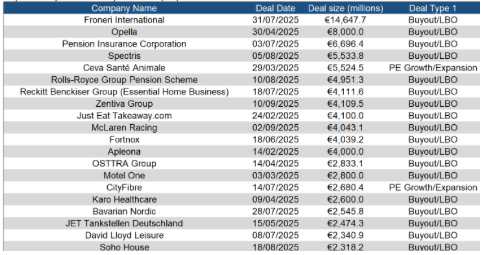
Top 20 Europe PE deals by deal size in 2025 Pitchbook
You reported that new EU rules under CRR3 (known as the Danish Compromise) mean that banks “no longer have to hold as much capital when acquiring insurers or asset managers.” Were there banks taking advantage of the new rule?
[Moura referred to Pitchbook’s Q1 European PE Breakdown report]: “The prime illustration of this loophole happened when BNP Paribas acquired AXA Investment Managers in 2024 through its insurance unit, with the Financial Times noting the deal cost ‘60% less than it would have if BNP had bought AXA IM directly.’”