The AI investment boom has reached a new peak, but its rewards are flowing to an increasingly narrow group of companies, said a Pitchbook AI report published in August 2026. Investors poured $407bn into artificial intelligence businesses during the first half of 2026, overtaking the $264.1bn raised throughout 2025. Behind that record lies a more fragile reality: fewer companies are securing funding, while frontier-model developers absorb unprecedented sums.
More money, fewer deals
AI companies raised $144.4bn in the second quarter, according to Pitchbook, making it the second-strongest quarter since its records began in 2016. The figure was nevertheless well below the exceptional $262.7bn invested during the opening three months of 2026.
Deal numbers also moved in the opposite direction. Investors completed 1,538 transactions in Q2, a fall of 21.6% from the previous quarter. The divergence suggests that the market is not expanding evenly. Capital is being concentrated in fewer, substantially larger rounds.
Frontier labs dominates
Horizontal platforms (see Chart 1), including the developers of foundational AI models, attracted $288.1bn in the first half. That represented 70.8% of all capital invested in the sector.
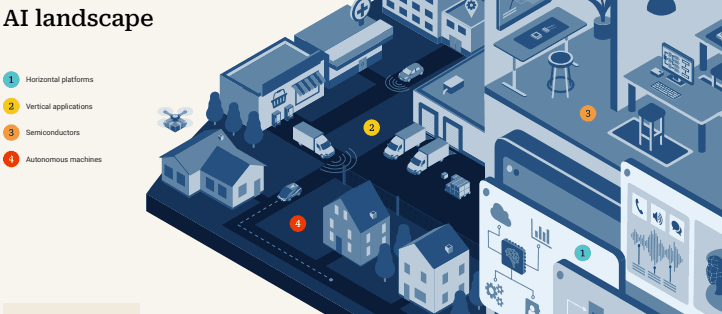
Chart 1: AI taxonomy Source: Pitchbook
Vertical applications accounted for only $52.6bn, or 12.9% of investment, despite generating 62.9% of transactions. These companies typically use existing models to build products for industries such as healthcare, finance and transport. They can often grow without the enormous computing budgets required by frontier laboratories.
The result is a divided market: application developers provide most of the activity, but model builders command most of the money (see Chart 2).
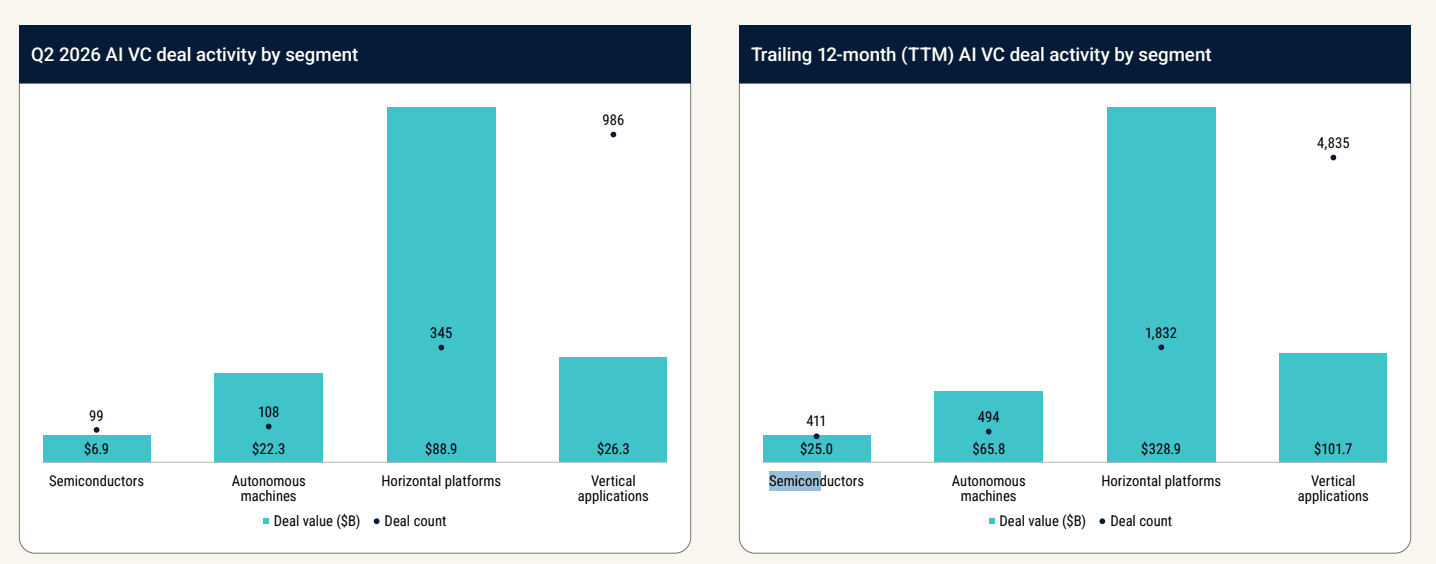
Chart 2: Deal activity by segment Source: Pitchbook • Geography: Global • As of June 30, 2026
Anthropic raises the stakes
Anthropic secured the quarter’s largest round with a $65bn Series H, lifting its post-money valuation to $965bn. The transaction was more than five times the size of the $12bn raised by robotics company Prometheus (see Chart 3).
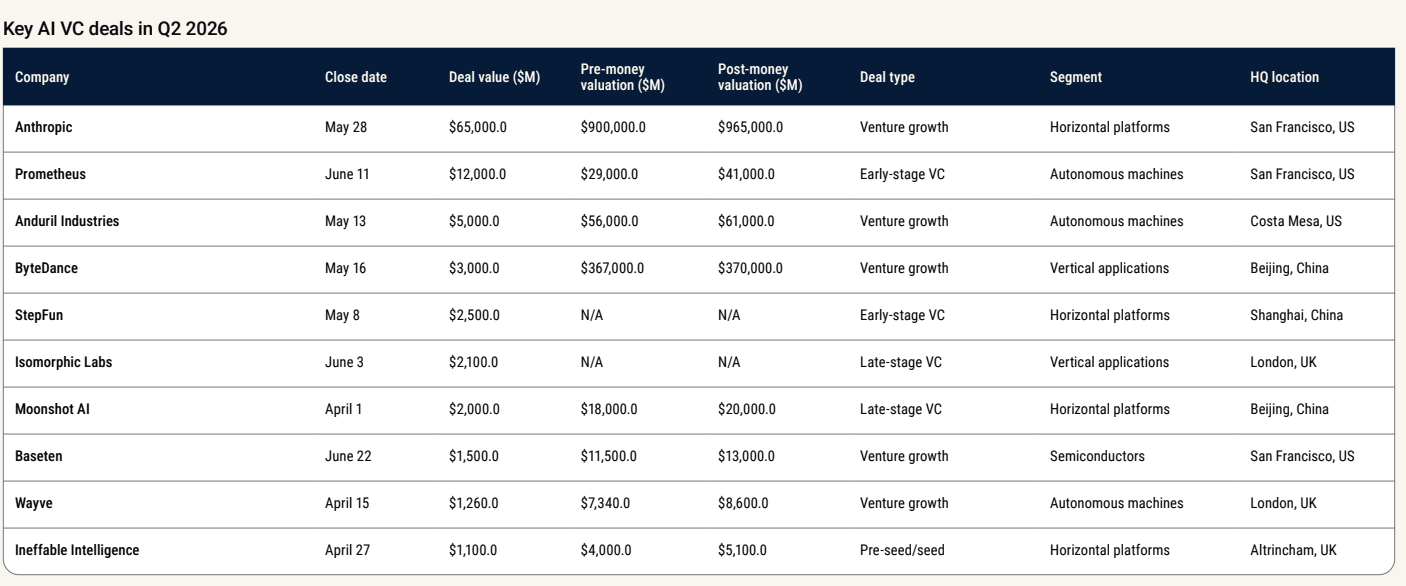
Chart 3: Key AI VC exits in Q2 2026 Source: Pitchbook • Geography: Global • As of June 30, 2026
Defence technology group Anduril Industries followed with a $5bn round, taking its valuation to $61bn. The deals underline investors’ appetite for companies operating in areas considered strategically important, from advanced models and robotics to national security.
Valuations are rising fastest at the top. The median pre-money valuation for venture-growth companies reached $953.8m in the first half, up 204% from 2025. By comparison, pre-seed and seed valuations increased by 17%.
Exits break records
Pitchbook reported that AI exit activity reached $391.1bn across 406 transactions, the highest level recorded in a decade and more than double the $130.7bn registered in 2025.
One transaction transformed the total. SpaceX’s $250bn acquisition of xAI represented 84% of first-half M&A exit value. Without it, M&A value would fall from $296bn to $46.4bn.
Public listings produced $92bn, led in Q2 by chipmaker Cerebras Systems, valued at $34.2bn, and quantum computing company Quantinuum, valued at almost $14bn (see Chart 4). Their debuts suggest that public investors remain receptive to prominent technology businesses, although inflation and tighter credit conditions could weaken the IPO pipeline.
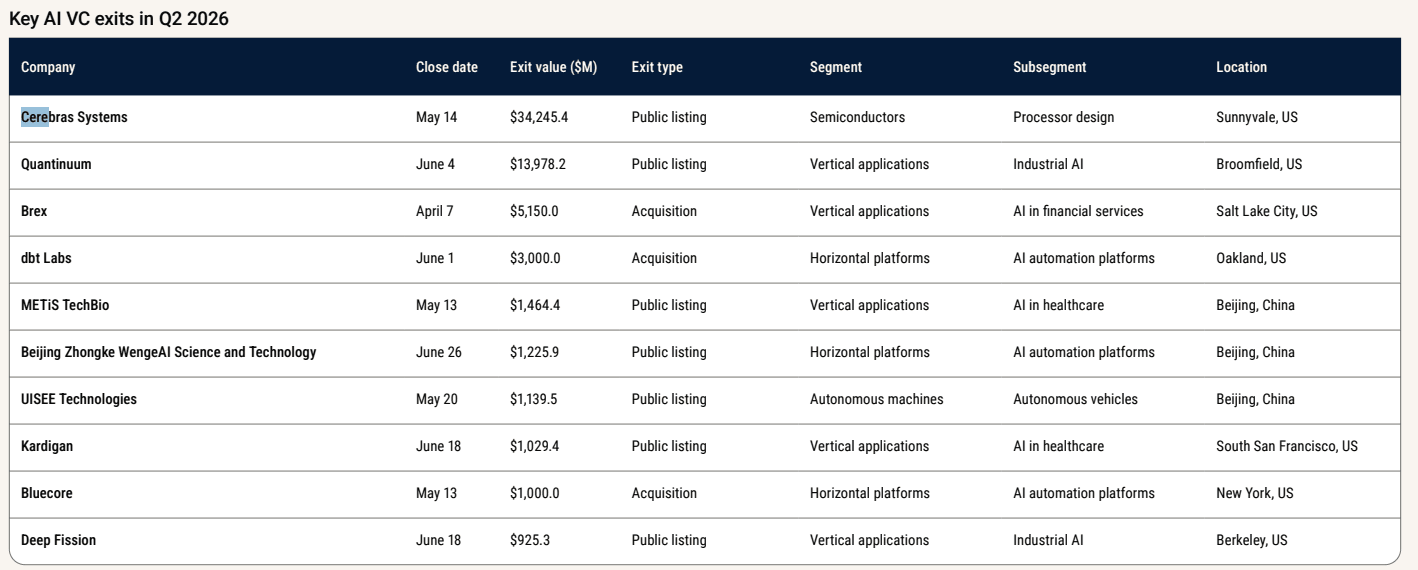
Chart 4: Key AI VC exits in Q2 2026 Source: Pitchbook • Geography: Global • As of June 30, 2026
A boom with boundaries
AI investment is not being constrained by a lack of capital. The challenge is where that capital goes. Investors are making ever larger bets on a small number of perceived champions, while thousands of application-focused companies compete for a much smaller share, noted the report.
That pattern is likely to define the remainder of 2026. The AI boom remains formidable, but it is no longer broad-based. Its defining feature is concentration: of funding, valuations, and faith in a select group of companies expected to control the foundations of the next technological era.