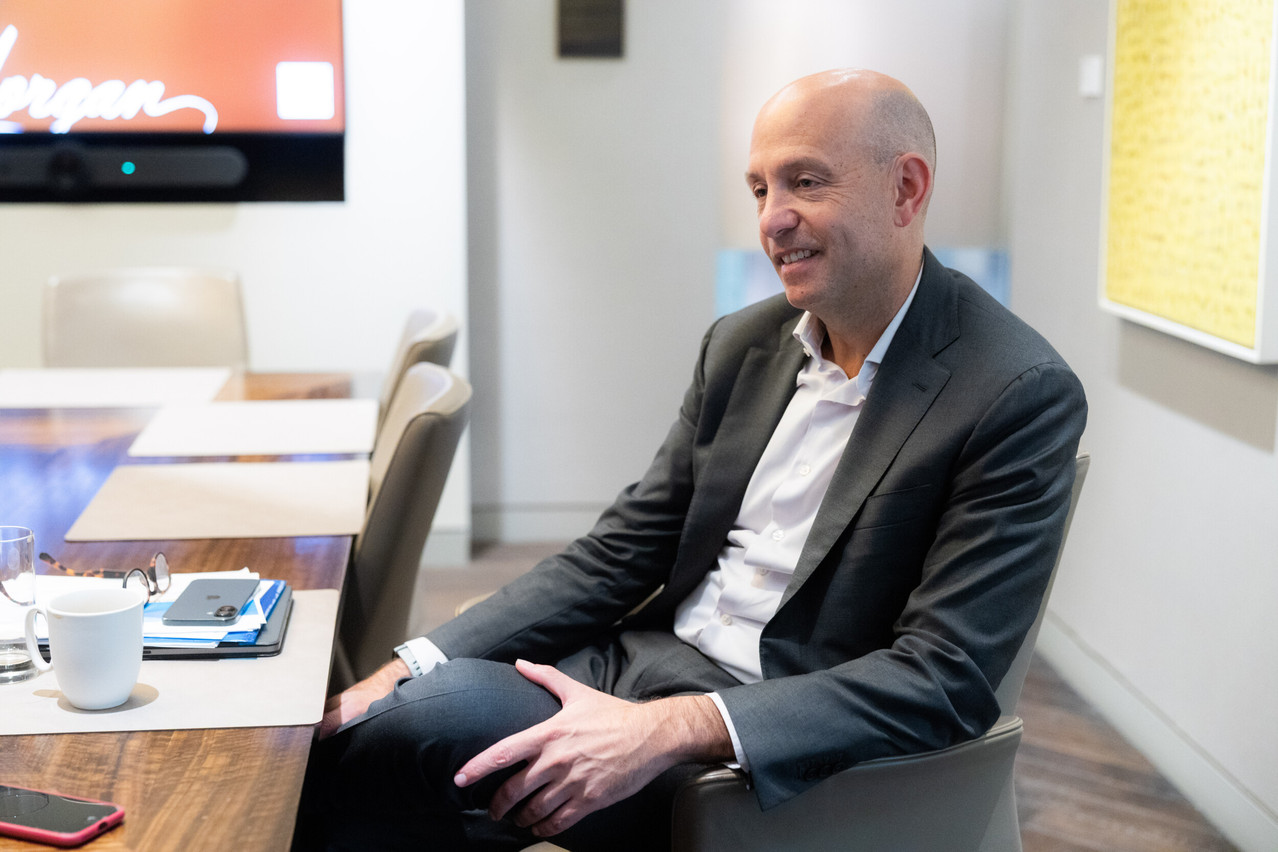
“As you can see from our risk-savvy boss, Jamie Dimon, we're focused on the worst-case scenarios,” said Jed Laskowitz, global head of private markets and customised solutions at J.P. Morgan Asset Management, during an interview on 19 May 2026 at the firm’s European Media Summit in London.
Drawing on three decades of experience across public and private markets, Laskowitz outlined how the investment landscape is evolving. He previously served as a chief investment officer overseeing multi-asset platforms for institutional and wealth clients, often acting as an internal limited partner (LP).
Liquidity pressure, not a credit collapse
While large redemption requests in Business Development Companies (BDCs) raised concerns regarding a potential systemic crisis in private credit, Laskowitz views these stresses as symptomatic of rapid asset class growth followed by temporary jitters, rather than a deeper structural failure. He stressed that the rush to the exit reflects a “liquidity event” rather than a fundamental “credit event,” occurring in “a corner of the direct lending market” rather than across the system.
Laskowitz emphasised that the current economic backdrop remains strong, with a US recession probability estimated at less than 20% over the next 12 months, according to JPM AM estimates. However, he warned that default rates would likely rise more sharply in private credit than in public markets during the next recession. Moreover, he noted that the gap between top and bottom performers in private markets is far wider than in public markets, even over normal periods.
Managing the “illiquidity premium”
Laskowitz highlighted the importance of maintaining discipline in fund structures. He described the industry standard 5% quarterly redemption limit for open-end funds as a vital feature that protects existing investors and ensures the “illiquidity premium” can be effectively harnessed. “But ultimately, it is there to protect the existing investors in the strategy,” he said.
Repeated by several speakers during the conference, Laskowitz criticised the use by the industry of the term “semi-liquid,” arguing that investors must understand they are giving up liquidity in exchange for higher yields, stronger returns and diversification benefits through lower correlation.
JPM AM is a “bottom-up fundamentalist
Beyond liquidity management, Laskowitz also stressed the importance of rigorous valuation practices. JPM AM utilises outside firms for valuations and often rotates these providers to ensure transparency and best practice. He welcomed the industry’s shift toward more frequent valuations to satisfy the requirements of managing capital in vehicles offering increased liquidity.
JPM AM prioritises performing secondaries
The US asset manager has been active in private equity secondaries for nearly 30 years and continues to leverage deep relationships with managers to gain visibility into underlying assets. From a risk perspective, Laskowitz does not chase distressed opportunities in the direct lending business.
Instead, he argued that there is a premium for complexity in performing credits in special situations with good equity cushion and favourable loan-to-value ratios. He underlined that JPM AM is a “bottom-up fundamentalist” with a preference for underlying credits offering strong earnings visibility.
The 2020 and 2021 vintages were particularly challenged within private equity, he noted. Stemming from “exuberant years,” these funds struggle with weak distributed-to-paid-in capital (DPI), a key measure of realised investor returns.
This drove heavy continuation fund activity, whereby private equity managers transferred selected assets from older vehicles into new investment structures to extend holding periods. Laskowitz also noted that the current M&A landscape lacks the necessary activity to unlock these portfolios and provide liquidity for investors on earlier vintages.
Infrastructure emerges as private market favourite
Beyond secondaries, Laskowitz argued that there are also opportunities in the primary market. He suggested that infrastructure has become a standout asset class, with fundraising up by almost 60% last year. Approximately half of the institutional investors surveyed expect to increase their infrastructure allocations over the next few years, drawn by the sector’s yield, low volatility, and diversification benefits.
Furthermore, a significant amount of capital raised in closed-end infrastructure funds between 2005 and 2010 is approaching a period in which exits and capital recycling are expected to accelerate, coinciding with surging energy demand. “There will be a real need for capital,” he said.
The retail investor gap
Despite the launch of products such as European Long-Term Investment Funds (Eltifs) and private equity interval funds, retail adoption remains relatively limited. Morningstar estimates total Eltif assets at roughly €10bn.
Laskowitz attributes this partly to an “education gap” among individual investors, many of whom are still unfamiliar with the mechanics of public markets, let alone private ones.
He also noted that the exceptional performance of public markets over the past decade has reduced the relative appeal of private assets for retail investors. However, in his view, periods of market stress—such as 2022—ultimately provide the clearest test and justification for private market allocations.
Sylvain Barrette in London
Paperjam was invited to attend the J.P. Morgan Asset Management 2026 European Media Summit in London. The latter paid for accommodation and transportation.


