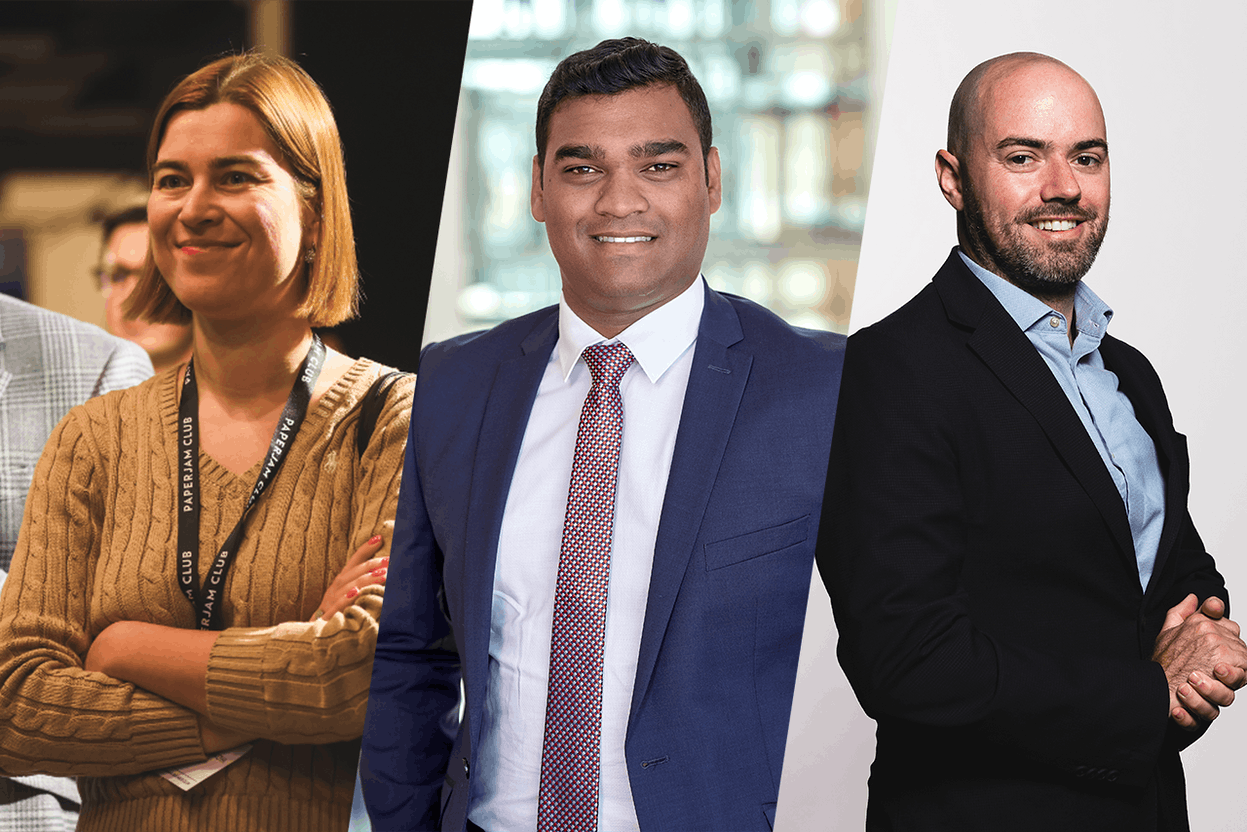
Kenny Panjanaden, ESG & sustainability partner at PWC Luxembourg, thinks that there is “a virtue to focus on one letter” when it comes to ESG. For example, CDP--an NGO formerly known as the Carbon Disclosure Project--focuses on environmental matters and enables rating providers to “specialise, offer tailored solutions, do innovative research” resulting in “accurate assessments aligned with the sustainability objectives of the stakeholders,” he told Delano during an interview.
Svetlana Grishankova, subject matter expert on ESG ratings at PWC Luxembourg, believes that investors with a low level of expertise would be interested by overall scores and then apply threshold to determine the investable universe, e.g., not lower than a D rating. She noted that the most sophisticated investor will rather bypass the MSCI overall rating and instead access MSCI’s database to capture and optimise their internal model to limit certain undesirable risks.
Arthur Carabia, director, ESG policy research at Morningstar Sustainalytics, stated that his firm--as for its competitors--does not want to offer a black box but rather present “maximum granularity... in an extremely detailed report… and in the score.”
Grishankova observed that informed investment decisions are better served through the capture of separate events at the letter level, such as a “huge environmental event” which may be diluted at the overall ESG level.
“Sophisticated investors know exactly where they want to have a positive contribution… E, S or G… and they want to know if accomplishing this objective might make them harm another sustainable objective,” stated Panjanaden.
Non-EU ESG ratings
Grishankova noted that stakeholders struggled with non-EU ratings under the credit rating agencies (CRA) regulation. It will come as no surprise that the “endorsement mechanism [as per the European Council and European Parliament’s provisional agreement] is very complicated indeed… but I think it would be implemented in a relatively similar way [as the CRA regulation].”
The intent of the regulation is to ensure that ESG ratings published outside the EU--even in the same group where the headquarters is generally based outside the EU--are signed off by its regulated EU entity and are accountable for the ESG rating published in the EU. The unstated reason for the implementation of the mechanism was to ensure that the EU regulation would equally apply to the dominant non-EU players.
Besides, the endorsement regime requires the partnered rating agency to be based in a country where there is a regulatory regime equivalent to the EU. In other words, the endorsement of a rating assigned in Russia or China would not be possible as they are “obviously not equivalent,” according to Grishankova.
Small ratings firms
A definition of a small player is “not indicated in the current regulation,” said Panjanaden. Looking at the CRA regulation as a good guesstimate, PWC observed that credit rating agencies raking in revenues beyond €10m are generally required to pay supervisory fees to the European Securities and Markets Authority (Esma).
Elsewhere, CRA regulation which relates to securitisation defined a rating agency with a market share under 10% as ‘small’. The jury is out on the rule that will govern smallness in ESG ratings. It may be reported later in a technical standard published by Esma.
Panjanaden does not think that large players will lobby against the favourable treatment for small players, as he thinks that they do not have oligopoly ambitions. He believes that the goal for the regulator is “to diversify and to grow [the business] and then to [foster] innovation. With smaller entry barriers, the regulator may also want to see “startup companies to enter the market,” thinks Grishankova.
Rating providers will have to disclose, manage and explain the conflict of interest to Esma

Carabia is not so sure. He remembered that investors were pushing hard for a regulation that would avoid market concentration. Despite the various exemptions and the phase-in period for smaller outfits, he thinks that the regulation will add a cost layer for small players that may fall anyway in the arms of large players, annihilating the initial goal.
Even worse, Carabia has heard that mid-sized players are concerned that dual-speed regulation may tempt investors to go for the providers that fully comply with the regulation to protect themselves legally. He thinks that the outcome may serve his firm well after it already acquired several small firms that filled several gaps in their approach. He noted that a code of conduct is sometimes preferred in the UK or Asia, as the authorities are concerned about going too far with a regulation.
Managing conflict of interest
“Strict legal separations were initially envisioned by the authorities,” observed Carabia. Instead, he noted that the provisional agreement now suggests that “rating providers will have to disclose, manage and explain the conflict of interest to Esma.” He expects synergies between their index and ESG rating businesses, as clients for both products are the same. Interestingly, Carabia concluded that there are no conflicts to manage between ESG ratings and DBRS, an inhouse credit rating agency, “given their distinct businesses.”
AI and ESG ratings
Grishankova observed that some ESG rating providers--such as Preqin and Reprisk--are using artificial intelligence in their methodology. The provisional agreement stated that “where applicable, an explanation of any AI methodology used in the data collection or rating process” will be required. She expects more clarity on the topic in due course.
Carabia thinks that the non-involvement of the regulator on the methodology will also help the market to react more rapidly on new non-financial risk related to AI, for instance.
Amendments expected
A double standard may develop for data providers and ESG rating providers using their proprietary data, as the former will not be covered by the regulation. Indeed, “the providers of ESG data have similar or even greater market influence as ESG rating providers and should also be subject to transparency requirements,” stated Grishankova.
MSCI declined to be interviewed for this article.
An alternate version of this article first appeared in the Spring 2024 issue of Delano magazine.