Moody’s Investors Service has downgraded the credit scores of both the European Stability Mechanism and the European Financial Stability Facility from Aaa to Aa1, the rating agency’s second highest level. The decision was driven by Moody’s recent downgrade of France from Aaa to Aa1, the agency said on Friday evening. Moody’s also placed the funds on its “negative” watch list, meaning that the credit agency believes a downgrade is possible in the foreseeable future.
“France is the second largest contributor to the two entities’ financial resources,” Moody’s noted. France holds a 20.4% stake in the ESM, representing €126 billion of the fund’s €620 billion in callable capital, and is responsible for backing 21.8% of the EFSF’s €726 billion in guarantee commitments, the ratings agency said. “Moody’s downgrade of France reflects the rating agency’s view that there has been a marginal diminution in the certainty that the sovereign will fulfil its financial obligations.”
Moody’s downgraded French debt in November, citing the country’s “multiple structural challenges, including its gradual, sustained loss of competitiveness and the long-standing rigidities of its labour, goods and service markets.”
Last week Moody’s said the ESM’s creditworthiness is diminished because: “In the very unlikely event of France being unable to fulfil its obligations to the ESM, there is a reasonable probability that other non-Aaa supporters would not be able to do so either.” The agency also said: “In the very unlikely scenario of the French sovereign bond default, Moody’s does not expect that France would be able to fund its commitments to the EFSF.”
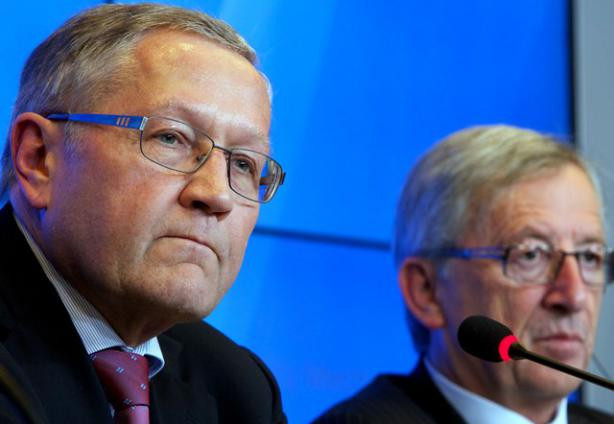
“Moody’s rating decision is difficult to understand. We disagree with the rating agency’s approach which does not sufficiently acknowledge ESM’s exceptionally strong institutional framework, political commitment and capital structure,” Klaus Regling (photo, left), chief of both the ESM and EFSF, said in a statement issued less than an hour after the Moody’s report was issued.
“This rating action does not inhibit ESM or EFSF in any way to act or emit.” Regling pointed out that last week the EFSF sold €7 billion in one year bonds, having received bids for €9 billion worth of the debt.
“The 17 euro area member states are fully committed to ESM and EFSF in political and financial terms and stand firmly behind both institutions,” Jean-Claude Juncker (photo, right), the prime minister of Luxembourg who also serves as chair of both funds’ boards, said in the funds’ joint statement.
The EFSF was created more than two years ago as a temporary bailout fund and is backed by euro area governments. The ESM is the permanent rescue fund, set to take over from the EFSF on January 1, which has been created by euro countries contributing capital.
The ESM and EFSF still hold top notch scores from rival credit agency Fitch. Both Kirchberg-based organisations--which are chartered with supporting the indebted governments of Greece, Ireland, Portugal and Spain--are therefore highly dependent on the credit scores of euro member states for their own ratings.
Still Aaa-rated Germany, for example, has a 27.1% share in the ESM and guarantees 29.1% of EFSF debt, but Moody’s has also placed the country on its negative watch list.
A lower credit score typically leads to higher borrowing costs in the capital markets.