While the European Stability Mechanism successfully launched during Monday’s Eurogroup meeting, progress proved more elusive for two other major issues on the agenda of Europe’s finance ministers.
During the summit, France and Germany won support for a financial transactions tax (FTT), which is meant to dampen risky financial engineering and provide a safety reserve for the financial sector. The two countries were joined by Austria, Belgium, Estonia, Greece, Italy, Portugal, Slovakia, Slovenia and Spain. The Netherlands, Poland and UK have said they will remain outside the system.
Luxembourg’s government has not taken an official position on what is sometimes called a “Tobin Tax”, although given the Grand Duchy’s large fund centre, Luc Frieden, the finance minister, has expressed some scepticism about a FTT in the past.
The European Commission has proposed the rates be set at 0.1% for stocks and bonds and 0.01% for derivatives, but the exactly figures have not yet been fixed. In addition, the 11 countries have yet to decide exactly how to use the funds raised by the levy.
Austria’s finance minister, Maria Fekter, said the FTT could come into effect as soon as 2014.
Banking supervision
Ministers also made little progress at the Eurogroup summit on exactly how to set up a single system of European banking supervision for all 27 EU countries under the auspices of the ECB, a principle that was agreed to earlier this year.
Bloomberg News reported on Tuesday that, according to a leaked draft proposal, non-euro zone countries would be able to opt out of the unified system, and that national parliaments would be able to summon the chief ECB regulator for official hearings.
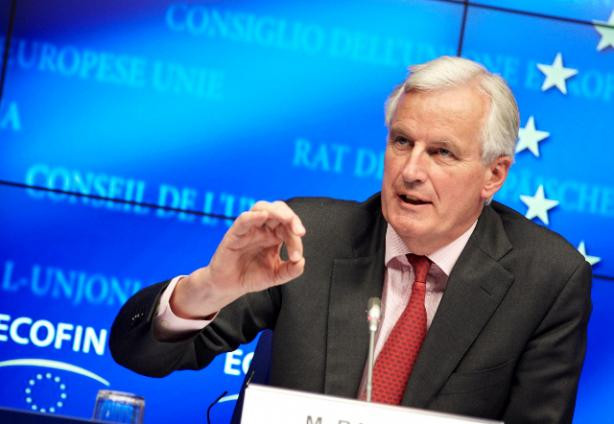
“Acceptable solutions are possible to all member states’ concerns on single supervisor,” Michel Barnier (photo), the European Commissioner responsible for financial services, said in his Twitter feed on Tuesday. He then tweeted: “We need to find a fair system for non #euro countries wanting to join #eu supervisor.”