The debate over Europe’s proposed financial transactions tax remains far from being settled, EU officials and analysts have said.
According to reports last month by the Reuters news agency and financial daily Wall Street Journal, the levy will initially be introduced at a lower rate than originally planned and will apply to fewer types of transactions.
The FTT is currently in the process of being negotiated by 11 European countries, not including the Grand Duchy and the UK, with the aim of inhibiting risky financial maneuverers, and boosting governments facing popular outrage against the financial industry malfeasance and budget austerity.
But ministers from the 11 states disagree about which types of transactions--such as those made by pension funds and the issuance of certain kinds of sovereign debt--could be exempt from the FTT, as well as if proceeds would be kept by national governments or go towards the EU budget managed in Brussels.
Under the original European Commission plan unveiled earlier this year, 0.1% would be levied on each trade in stocks and bonds and 0.01% for derivatives starting January 1, 2014. It would apply to both parties in a transaction, even if only one is located within the 11 country zone.
Yet a “senior EU official with knowledge of the talks” was quoted by the Journal saying that basic decisions still need to be taken”.
Another one of the EU “officials working on the project” was quoted by Reuters as saying, “the whole thing will have to be changed quite a lot” and that the FTT “is not going to survive in its current form”. Sources told the news agency that the tariff rates could be reduced, and its application to different types of financial transactions could be introduced in phases, instead of all at once.
Likely to be “watered-down”
Analysts at political risk consultancy Eurasia Group agreed that “it is highly likely that the tax will be significantly watered-down” and that “a staggered approach is also a likely possibility”.
“There are too many concerns about the currently proposed FTT’s potential impact on the participating economies for the tax not to be watered-down,” the firm’s financial services director Dan Alamariu told Delano on Wednesday.
Despite the European Parliament’s economic and monetary affairs committee voting in late May to strengthen the tax, Alamariu and his colleague Samantha Grenville pointed to objections by European central bankers, both at the European Central Bank in Frankfurt and in France and Germany, as well as member state governments.
“Our view remains that the EU11 FTT is most likely going to have to exempt repo transactions [short-term loans between institutions], sovereign and also possibly corporate bonds--although these may be included later in a staggered approach--in order to get the 11 states to agree to move forward,” Alamariu said.
“Given how the politics are shaping at the country-level and the negotiations around the issue, the final common FTT is likely to resemble either the current French FTT or the UK stamp duty, with a far more limited extraterritorial application and limited mostly to equities and some derivatives--at least at first. At the same time, more institutions, such as pension funds, may gain exemptions from the tax,” he told Delano.
“The German elections in September also make serious decisions on the FTT unlikely before the end of this year. So finalisation will likely take place next year, with implementation possibly stretching to 2015,” Alamariu reckoned.
Reports exaggerated
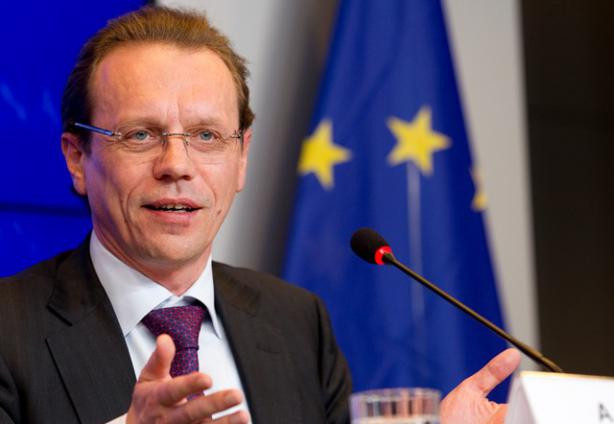
As of this writing, a spokeswoman for European tax commissioner Algirdas Semeta (photo) had not returned Delano’s message seeking comment.
However, Semeta told European news website EUobserver that reports of acrimony surrounding the so-called “Tobin Tax” were overblown. “Talks are taking place in a constructive mood and there are various technical ideas on how to make it better,” he said in a May 31 interview.
The commissioner stressed that: “It is really premature to say what will be the final outcome of the situation because member states are currently in the phase of the first reading.”