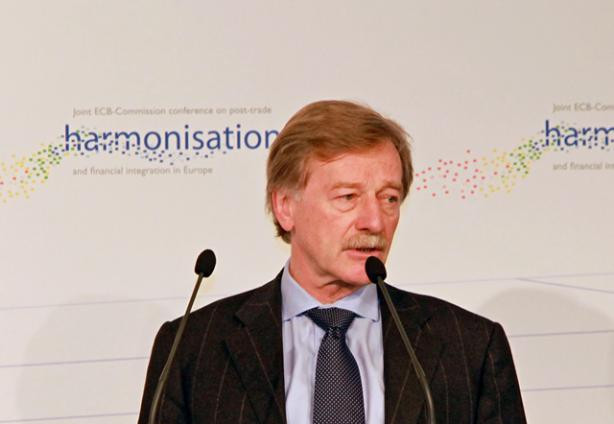
Yves Mersch has critiqued the European Commission’s proposed financial transaction tax, saying it could force banks to depend even more on the European Central Bank. Banks will likely shy away from offering each other short-term loans, which would in turn damage market liquidity and force institutions to turn to Frankfurt more frequently, warned Mersch, a member of the ECB’s executive committee and the former governor of Luxembourg’s central bank.
The FTT is currently in the process of being adapted by 11 European countries, not including the Grand Duchy, with the aim of dampening risky financial engineering and providing a safety reserve for the financial sector and struggling government budgets.
In a speech Monday evening in Luxembourg, Mersch said the FTT was “as an example where government regulation may have adverse consequences on financial markets and monetary policy transmission.” As the ECB is meant to remain politically impartial, he said: “I would not like to enter into the case for or against the FTT” however “it is appropriate for us to take a neutral view on the objectives of this measure.”
After reviewing the draft FTT rules published by the commission on behalf of the 11 member states in February, Mersch said “attention needs to be drawn to possible negative implications for the implementation of monetary policy and financial stability”.
He argued that banks would have “incentives” to replace financing raised in the private capital markets, which are subject to the FTT, with funding from the central bank, which would be exempt. In an unvirtuous cycle, that “may hamper market liquidity and increase banks’” reliance on resorting to ECB funding.
In addition, Mersch feared the “possible distortion will be largest on the shortest maturities” such as in the “repo market”, which are short-term loans between institutions backed by specific assets, as the “FTT does not take into account maturity”.
He was also alarmed by the possibility of “reduced liquidity in secondary fixed income markets, including government bonds, which may hamper smooth monetary policy transmission and worsen market fragmentation at a time when many of these markets remain fragile”, according to a transcript of his speech provided by the ECB.
Mersch’s address was part of the Luxembourg Stock Exchange’s annual “Stock Exchange Day” conference, where he marked the 15th anniversary of the ECB and pressed for implementation of the proposed EU banking union.
Tobin against “Tobin Tax”
Enacting a “Tobin Tax”--named after Nobel Prize winning economist James Tobin--in the EU could raise more than €50 billion annually, according to European Commission estimates. The tax is a small levy on all stock, bond and derivative trades.
Mersch observed that in the 1980s “Tobin proposed a notion of ‘functional efficiency’, i.e., do financial markets and intermediaries provide value to society at large? Do they channel savings to the most productive investments, by pooling risk and allocating it to those best placed to bear it?”
For Mersch, this is the question that must be used to “assess the financial system in the wake of the crisis and its service for the real economy. While he was critical of the considerable resources that tended to be devoted to ‘churning’, to ‘gambling’ and endogenous, self-referential activities in financial market, he was a lifelong critic of the Tobin tax named after him.”