The Grand Duchy currently has S&P’s highest rating. But its “AAA” status may be downgraded by the ratings agency due, to the “deepening political, financial, and monetary problems within the European Economic and Monetary Union,” S&P said in a press statement.
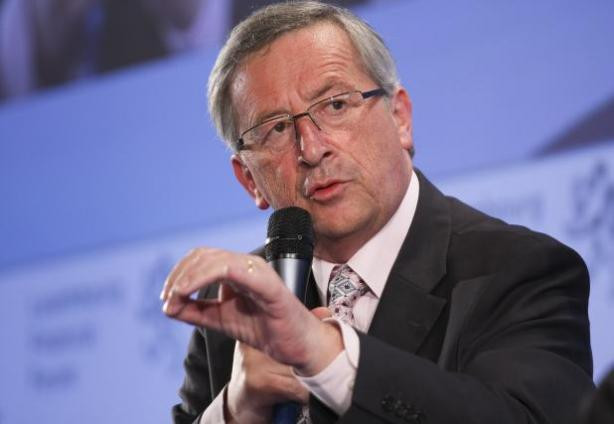
“I think it is grossly excessive and unjust,” the prime minister, Jean-Claude Juncker, said during an interview with German radio station Deutschlandfunk on Tuesday. He said it was “irrational” to consider downgrading a country such as Luxembourg that only has a public debt rate of 20 percent of GDP.
Other euro zone countries have debt rates in excess of 100 percent.
Juncker said the rating agencies no longer deserved the public’s faith, noting the bureaus failed to predict the 2007-2008 sub-prime mortgage crisis in the US, and indeed had rated the troubled financial products highly. “We should not base our future policies based on these ratings agencies,” the prime minister told the radio station.
S&P also placed the other five AAA rated euro zone countries--Austria, Finland, France, Germany and the Netherlands--on its negative watch list on Monday.
On Tuesday, the Kirchberg-based euro zone bailout fund EFSF had its AAA rating placed on negative credit watch by S&P, as the rescue facility is largely backed by the six AAA governments under the rating agency’s microscope.
S&P said it would conclude its reviews of all the countries’ credit scores following the summit of European leaders on December 9.
On November 28, another of the world’s major credit ratings agencies, Moody’s, said that “in the absence of major policy initiatives in the near future which stabilise credit market conditions,” it would “revisit” its ratings on euro zone, and possibly all EU, member states during the first quarter of 2012.