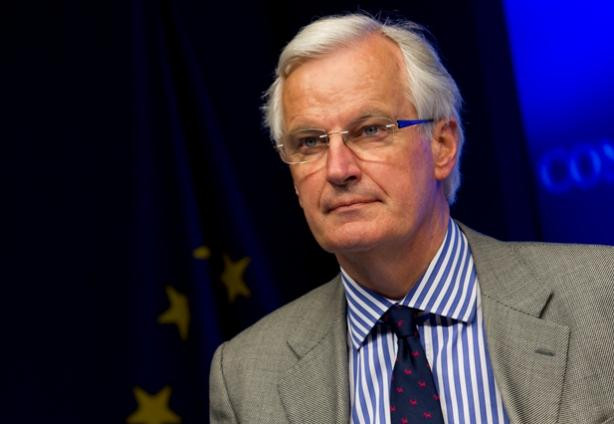
The fund executives wrote to Barnier--the European commissioner responsible for financial regulation (photo)--on July 4, the day Brussels released a draft of the proposed “AIFMD” rules, an investment industry source has told Delano.
AIFMD is meant to regulate “alternative” investments meant for professional investors, such as hedge funds and real estate funds. However, the commission has mooted applying some of the same rules--notably those on liability requirements for custody banks--to retail UCITS funds, which is the backbone of Luxembourg’s fund industry.
The July 4 draft included rules on delegation, which would require fund managers and risk managers to be located in the country where their fund is domiciled. The aim is to crackdown down on “empty shell” or “letterbox” companies which mainly exist for fiscal purposes.
But the fund companies--members of the lobby group Forum of European Asset Managers that include AXA, Fidelity, ING, J.P. Morgan, Schroeders, State Street and UBS--argued that the rules as written would stifle the single market in funds, Delano’s source explained.
He noted that for many funds, general oversight functions are conducted at the company’s office--for example in Luxembourg--while portfolio and risk management is handled locally. A Grand Duchy-domiciled fund may have European equity or bond managers based in Frankfurt or in London. “This practice is the single market working at its best,” the letter said.
Equally a Luxembourg firm’s Asian focused funds are likely to have managers in Asia and its US focused funds have managers in the US.
Such “delegated” executives take “crucial decisions” that ensure that funds operate in line with their advertised strategy and meet their objectives, the industry leaders said. If these managers had to relocate back to their “home” market, it would increase risk and decrease returns for investors, because managers would be less able to keep tabs on local markets, the letter said.
The fund managers added that such a result is clearly “not intended by regulators” which is why they wanted to point out the rules on delegation would “weaken the objectives of the AIFMD.”
In addition, they expressed concern that “the precedence for asset management delegation could be transposed into UCITS directives at some point in the future” which would “compromise the gold standard of the UCITS brand” as asset managers would lack “access to full range of services in EU. When delegation is carried out well, investors benefit,” the letter concluded.
The commission is expected to submit its final version of the proposal to the council of European finance ministers in September, which must accept or reject the draft as written.
A spokesman for Barnier did not immediately return Delano’s message requesting comment.