The European Commission has disputed the conclusions and significance of a confidential memo written by legal advisors to EU leaders on the so-called “Tobin Tax”, saying the document only addresses a limited part of the proposal and not its fundamental principles.
The European Council’s legal service wrote in an internal opinion for finance ministers leaked this week that the proposed European financial transaction tax “is discriminatory”, exceeds member states’ jurisdictions, and is contrary to EU law.
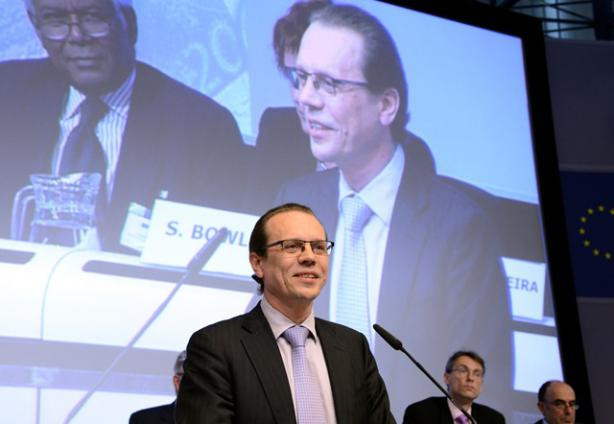
“We strongly disagree with the council [legal service’s] opinion on the FTT”, a spokeswoman for Algirdas Šemeta, EU tax commissioner (photo), told Delano on Wednesday.
In the wake of the financial crisis, 11 EU countries are introducing the FTT under Europe’s “enhanced cooperation” mechanism that allows nine or more member states, via the commission, to introduce common rules when an agreement cannot be reached for the entire union.
The tax will nonetheless apply to all parties in a transaction--even those located outside the 11 nations--if at least one party is based in the FTT zone, under the bill’s “residence principal”. The provision was crafted to prevent financial institutions from bypassing the levy by issuing securities and routing deals through other countries.
The council’s legal service said this was jurisdictional over-reach.
Commission already examined issues
However Šemeta’s spokeswoman said: “the commission’s legal service carried out a very thorough legal analysis before the commission presented this proposal, and we stand firm that the proposed FTT is legally sound and fully in line with the EU treaties and international tax law. The commission legal service will analyse in further detail the [council legal service] opinion, and will come back to these issues in the council. It is important that the negotiators have the full picture to allow proper discussions.”
She added that: “this opinion is one of many which have been fed into the discussions around this proposal; it certainly doesn’t imply any necessary slow-down in the work being done to progress the FTT.”
“It is also important to note that this opinion only questions one part of the residence principle, not the tax as a whole or the procedure of enhanced cooperation,” the commission spokeswoman stressed to Delano. “The question of issuance versus residence principle is one that has been discussed at length, and will no doubt be one of the more lively points of discussion when the 11 member states proceed with the political negotiations on this file.”
“As Commissioner Šemeta has repeatedly said for some time now, ultimately it is for the 11 member states in question to find common accord on what they want to implement,” she concluded.