The proposed European financial transactions tax is likely to be postponed and scaled back, a new report has said. The plan will be moderated due to “growing disagreements among the EU11, push-back from the financial services industry and other EU member-states, as well as from key economies such as the US”, according to political risk research and consulting firm Eurasia Group.
The FTT is currently in the process of being negotiated by 11 European countries, not including the Grand Duchy, with the aim of dampening risky financial engineering and providing a safety reserve for the financial sector and struggling government budgets.
The planned levy--0.1% for each trade in stocks and bonds and 0.01% for derivatives--is intended to go into effect on January 1. It would apply to both parties in a transaction, even if only one is located within the 11 country zone.
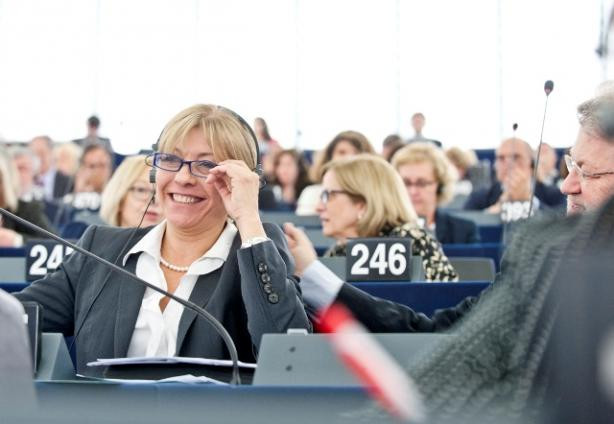
Greek socialist MEP Anni Podimata (photo) has said that the FTT “will bring a fairer distribution of the weight of the crisis” but “will not lead to relocation outside the EU because the cost of this is higher than paying the tax”.
The European Parliament has a committee vote scheduled for May 28 and a plenary vote set for July 2, which may force changes to the draft bill.
“Afterwards, the European Commission hopes the 11 states will adopt the FTT directive before October 1, 2013, to allow for the FTT’s implementation by” the beginning of the year, New York-based analysts Dan Alamariu and Samantha Grenville said in the report, which was issued May 7. “However, this looks implausible given the September 2013 German elections and increasing disagreements among the 11 states. Forging an agreement on a diluted tax will likely delay the currently targeted implementation date of January 2014 by at least six months.”
Continued disagreement
Specifically, the 11 participating countries have failed to agree on precisely which types of transactions will be covered by the levy, the report noted. Italy is set against including sovereign debt, as it relies heavily on government bonds and already is forced to pay high yields. France does not want the levy to apply to corporate bonds, and--supported by Spain--on transactions made by pension funds and within the same financial group, although Belgium opposes the latter two exemptions.
All 11 are opposed to the European Commission’s plan to include the “repo market”--short-term loans between institutions backed by specific assets, which help maintain market liquidity--a position supported by Yves Mersch, member of the European Central Bank’s executive council and former governor of Luxembourg’s central bank.
Extraterritorial reach
“Within the EU, the UK (backed by Luxembourg) has already launched a preliminary legal challenge at the European Court of Justice, claiming the FTT as proposed would be unfair to EU states that choose not to participate, given its broad extraterritorial reach,” Alamariu and Grenville wrote.
In addition, “US treasury secretary Jack Lew recently reiterated that the US remains strongly opposed to the proposal.”
“At the same time, there is a small (though growing) chance that the FTT proposal will die a quiet death,” the analysts stated. This could happen if less than nine member states agree to the final version of the law.
German politics
Germany may oppose the FTT after national elections in September, if chancellor Angela Merkel renews a government coalition that includes the Free Democratic Party, “who have voiced strong opposition to the tax”, according to the Eurasia Group report.
In that case, the 11 supporters could simply introduce national FTTs, which is already the case in France and Italy.
Nevertheless the analysts concluded that “a watered-down joint FTT remains more likely than not, given existing political momentum to tax financial transactions to appease populist anti-bank sentiment, and longer-standing continental EU concerns over the impact of ‘speculation’ on financial stability.”