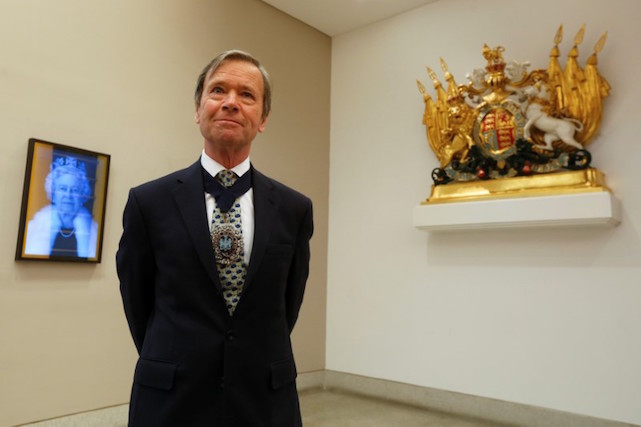
The City of London’s Lord Mayor, Jeffrey Mountevans, will tell regulators at a dinner on Wednesday evening that after Britain’s vote in June to leave the EU, “realistic, collaborative” regulation is needed to keep the sector on an even keel.
“Regulation that will continue to protect our competitiveness and provide liberal market influence across the EU, even after Brexit,” Mountevans said in remarks released to the media in advance of the annual Mansion House dinner for bankers and regulators.
The City is crying out for a consistent and forward-looking Brexit strategy that has a “bold, bright, buccaneering vision of the future”, Mountevans will say.

A sign for Bank Street and high rise offices are seen in the Canary Wharf financial district in London, 21 October 2010. Photo: REUTERS/Luke Macgregor
Some will see this as harking back to a discredited past.
This week the City marks 30 years since the day of the “Big Bang” deregulation of London’s financial markets that helped to propel London to the top of the league table of global financial centres.
The financial crisis of 2007-09 then forced taxpayers to bail out undercapitalised and poorly supervised lenders, tarnishing the “light touch” regulatory approach and ushering in a welter of tougher rules.
But since the Brexit vote, Paris, Frankfurt, Luxembourg and Dublin have vied to win a slice of the City’s financial pie should banks and other companies move operations to other countries to maintain full access to EU markets.
Backers of Brexit have also voiced hopes for an end to EU rules such as caps on banker bonuses.

Andrew Bailey, chief executive of the UK’s Financial Conduct Authority, in a portrait published on the regulator’s website
But Andrew Bailey, chief executive of the Financial Conduct Authority (FCA), who is also due to speak at the Mansion House dinner, has scotched talk of a post-Brexit bonfire of the regulations.
At a launch of the FCA’s public consultation on a new “mission” statement on Wednesday, Bailey said he would not support making competitiveness an objective.
“The thing that we can contribute to competitiveness is sound regulation,” Bailey told reporters. “It’s not appropriate, in my view, to have a competitiveness objective.”
(Editing by Greg Mahlich and David Goodman)