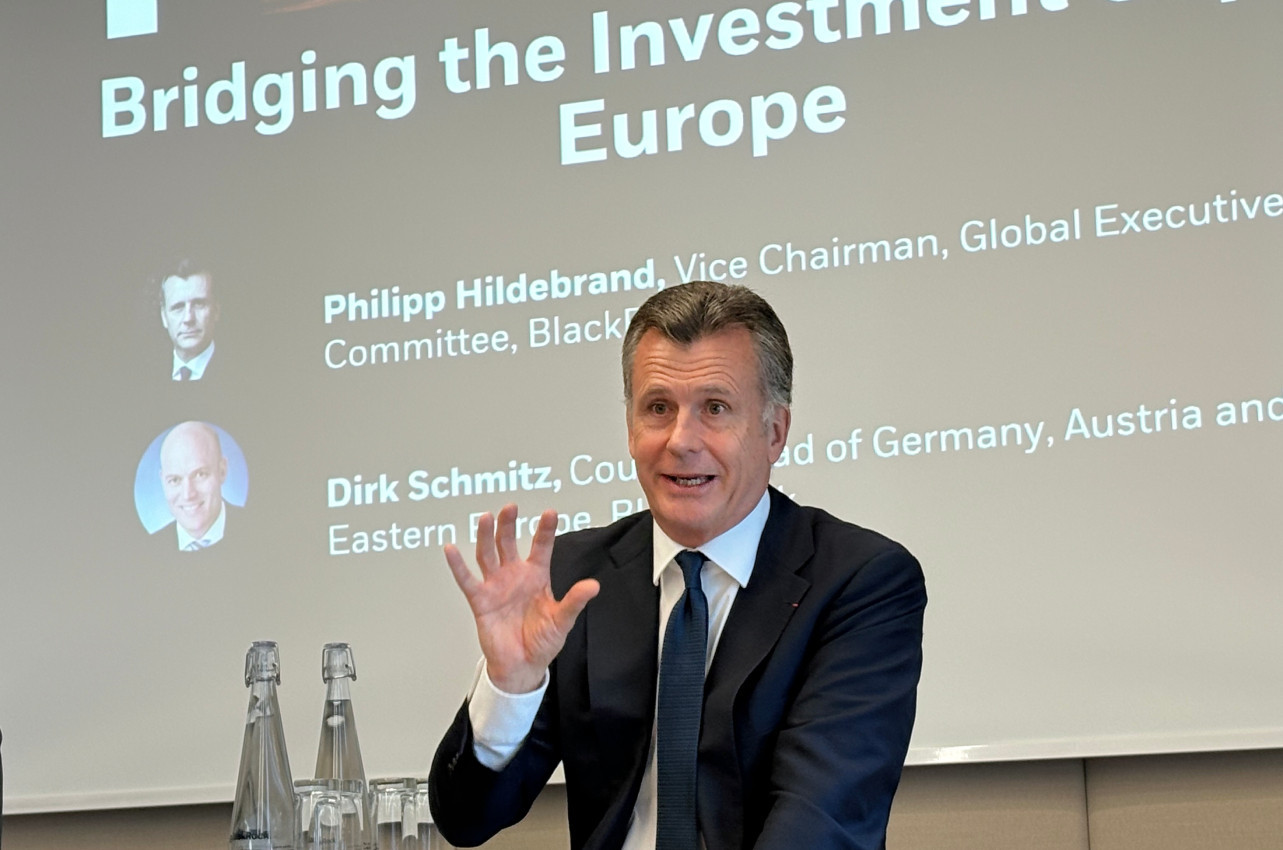
"Frankfurt is at the heart of Europe," Philipp Hildebrand said from the outset, a position that Luxembourg would gladly dispute but which, on this day, was obvious from the 41st floor, with bay window overlooking the sun-drenched skyline. Alongside the country head for Germany, Austria and Eastern Europe, Dirk Schmitz, BlackRock's global vice-president set out the diagnosis and the figures: more than 7,000 employees in Europe, a presence in 25 countries visited "for the most part in the last 18 months", and "€1.8trn" already invested on the continent. Above all, a considerable reservoir: "We are sitting on €10trn of bank deposits in Europe. It's not a problem of savings; it's a problem of deployment to the capital markets."
Hildebrand put the spotlight on the European economy. Hildebrand placed the debate in a geopolitical context of "muddled transition", where the "global insurer" has withdrawn: to remain competitive, Europe must link private capital, innovation, productivity and future growth. The heart of the message lies in the shift in financing channels: "The great innovation of the last fifteen years - from tech to AI - has been financed by the capital markets, not by bank credit. If Europe wants to participate in the AI-related capex boom, it needs to mobilise private savings." He puts this wave of investment in AI at between $1trn and $2.5trn a year worldwide and warns: if these flows are concentrated in the United States or the Middle East, "Europe will fall further behind".
Only 15% of the global economy can be accessed via listed companies; 85% can only be accessed via private market transactions.
Dirk Schmitz hit the nail on the head with a ratio: "Only 15% of the global economy is accessible via listed companies; 85% is only through private market transactions." Yet the needs - energy networks for AI (data centres, production, connections), "hard" infrastructures, start-ups and innovation capital - exceed the public budget. Hence the coordinated plea to finalise the Union of capital markets, review the incentives for long-term savings and, ultimately, create a safe and liquid European asset: "In the absence of a European 'treasury', every flight to safety still goes through the dollar."
The tone became more political on defence. Hildebrand spoke of a "public good par excellence": not just "more tanks or planes", but above all new capabilities - drone walls, anti-missile shields, electronic warfare, AI - requiring pooled funding, coordinated manufacturing and unified deployment on a European scale. In his view, the defence dossier is "the ideal laboratory" for testing pooled funding and, in turn, accelerating the emergence of a European risk-free asset.
"Frankfurt is at the heart of Europe", said Philipp Hildebrand from the outset, a position that Luxembourg would gladly dispute but which, on this day, was obvious from the 41st floor, with bay window overlooking the sun-drenched skyline. (Photo: Paperjam)
The second act turned the room towards data. "We are at a pivotal moment", said Melissa Ferraz, Global Head of Aladdin Alternatives: the global private markets are "projected to be worth $32trn by 2030", including €5trn expected in Europe, "one of the most dynamic growth areas". For her, "data has become alpha": long confined to the back- and middle-office, it is "coming to the fore" to untangle the growing complexity of portfolios (open/evergreen funds, semi-liquids, co-investments), steer liquidity and risk, and support operational efficiency.
The head of general partners at Preqin (another strategic purchase by BlackRock), Leon Sinclair, rolled out some fresh statistics: More than €55bn raised in infrastructure in Europe in the first half of the year, "already beyond 2024"; €167bn raised by pan-European private equity in 2024; in the UK, €60nn already raised at mid-year, "on track for the five-year average". In terms of sentiment, he talks of a "12-point jump" in six months in the probability of major global investors allocating to Europe, while "for the United States", the favourability of the same allocators has fallen "from around 89% to just under 50%". European allocators are "66% to judge Europe as the best opportunity in risk-adjusted returns today".
Capital deployment at half mast
But the reality on the ground tempers the euphoria: "Deployment to businesses and projects in the first half of the year is around 10% below last year's level", warned Sinclair warned. The main reason: the market's "last mile" - capital recycling, slowing IPR, valuation gaps between buyers and sellers - is holding back sales and new entries. Added to this is the US premium. Many European assets remain at a discount to their US equivalents, complicating arbitrage.
Faced with this, the two speakers described the current architecture at BlackRock: Preqin, now "a part of BlackRock", feeds a unified and interoperable platform (Aladdin/eFront/Preqin) to offer a "whole portfolio" view - from listed to unlisted, around 200,000 funds tracked - with forecasting models, fund-raising schedules, and liquidity tools integrating markets now capable of exchanging ~300 pre-IPO names with liquidity. The secondary LP? "Composite mid-teens growth", which makes it possible to continuously monitor exposures. On AI, the line is pragmatic: intensive use of efficiency and signaling (VC scouting, disposal windows, ESG risks), but humans in the loop, and caution with regard to hallucinations; no major open use cases without safeguards.
Third act: infrastructure with Gonzalo García (Global Infrastructure Partners). One year after the integration, "$189bn of assets under management", 19 years of history, 680 professionals, hubs in New York, London, Singapore, "more than 950 investors" and "300 active investments in 100 countries". The GIP V fund, with "just over $25bn in equity", remains the flagship, with a "pure" definition of infrastructure: critical assets that are difficult to replicate, high barriers to entry and stable cash flows. All this in just four sectors: energy, transport, digital, water & waste. In Europe, GIP claims "around $50bn of equity deployed in 33 countries".
A new fund will be launched, housing the stake with ENI
The GIP "signature" is based on two operational building blocks. Firstly, long-term partnerships - "60 partnerships" to date - including a recent joint venture with ENI in carbon capture and storage: "We prefer to build replicable platforms rather than collect isolated assets". Secondly, a Business Improvement Team of more than 40 operational experts, ex-CEOs and managers, inserted into companies to create value. At Gatwick, "the most efficient single-runway airport in the world", with "more than 280 movements per year" - a formula which, if surprising, illustrates the obsession with operational optimisation. On the ESG side, the approach is intended to be "data-driven and commercial": 81% of holdings have decarbonisation targets, 67% net-zero scopes 1-2 objectives, 78% "on track" in the latest reporting.
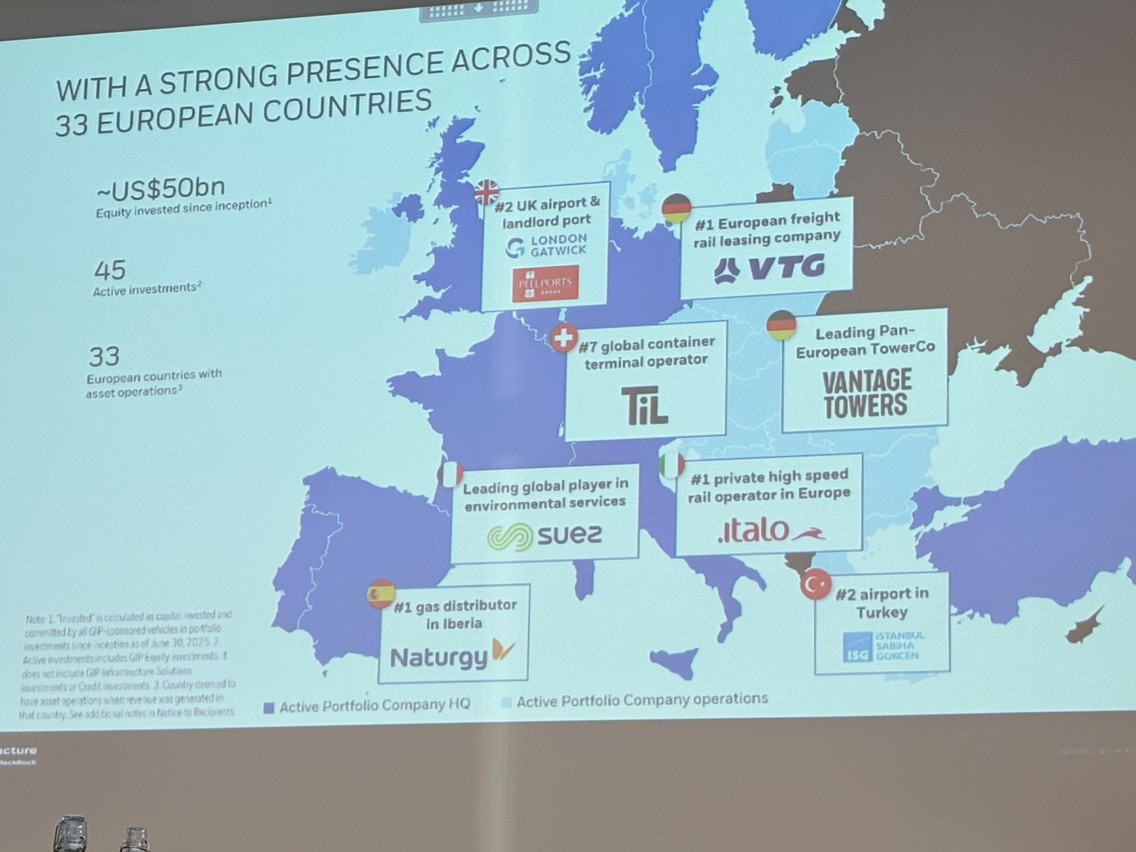
Some of the holdings of Global Infrastructure Partners, now a BlackRock entity. (Photo: Paperjam)
For the opportunity ahead, García has got out the calculator. The cumulative investment gap in infrastructure by 2040 is close to $15trn. A case in point: Germany "needs 20GW of gas-fired power stations" to compensate for the phase-out of nuclear power and the coal trajectory (2038), despite a renewable share of around half of the mix; "without this firm dispatchable capacity, peak demand will not be met". Added to this are digital networks for AI, post-Covid industrial re-chaining and the renovation of ageing assets. GIP is preparing a new "transition" strategy focusing on electrification, decarbonisation partnerships, clean fuels and the circular economy. On transport, he points out that the hard part is not the car but aviation and shipping: SAF will be needed for aviation, methanol/ammonia for shipping - and "someone has to build these industrial units". A new fund has "not yet been formally launched", but an initial seed investment has been made to accelerate the building of the pipeline.
As the sequences unfolded, a quantified story became clear. The reservoir exists (€10trn in deposits), but so do the needs (AI, defence, networks, transition) and the flows are being redirected towards Europe (infra-regional collection, PE, feeling of entitlement). Frictions persist (valuation, recycling, IPR), but the toolbox is being put in place: data platforms (Preqin/Aladdin/eFront), interoperability, predictive analytics, deeper secondaries, semi-liquid vehicles and industrial teams capable of operating assets. "We have the resources, the technology and the needs", concluded Hildebrand. "What we need now is a European architecture that lets capital circulate where it creates value." From the bay window of the Opern Turm, the ambition seemed all the clearer because the figures were there.