Luxembourg banks are facing a marked increase in the cost of regulation. The fourth joint study by the ABBL and EY shows that compliance investments rose sharply in 2024, against a backdrop where operational resilience, digitalisation and anti-money laundering requirements continue to intensify.
For so-called significant institutions, regulatory investment costs have now reached €8.1 million, with a further €20.7 million in recurring costs. By comparison, credit institutions have investment costs of €2.9 million and €4.1 million respectively, while branches of European and non-European institutions have investment costs of around €2.8 million and recurring costs of €3.4 million. But in relation to their size, the burden is proportionately heavier for smaller structures, highlighting a structural disadvantage in their ability to absorb regulatory constraints.
The impact is also measured in terms of headcount. Large banks report an average of 127 full-time equivalents dedicated to regulatory functions, compared with 30 for medium-sized institutions and seven for branches. However, as a proportion of total staff numbers, it is the smaller entities that devote the largest proportion of their human resources to compliance, up to 21%, compared with 12% for the larger institutions. Labour costs further accentuate the effect: the average annual cost of a compliance position in Luxembourg is significantly higher than both the European average and the average national labour cost.
A complex balance to strike
No surprise, the fight against money laundering and tax evasion remains the top regulatory priority, followed by market conduct rules with Mifid 2. New texts are also gaining in importance, such as the Dora regulation on digital operational resilience and the regulation on instant payments, which reflect the shift towards the challenges of cyber-resilience and digitalisation.
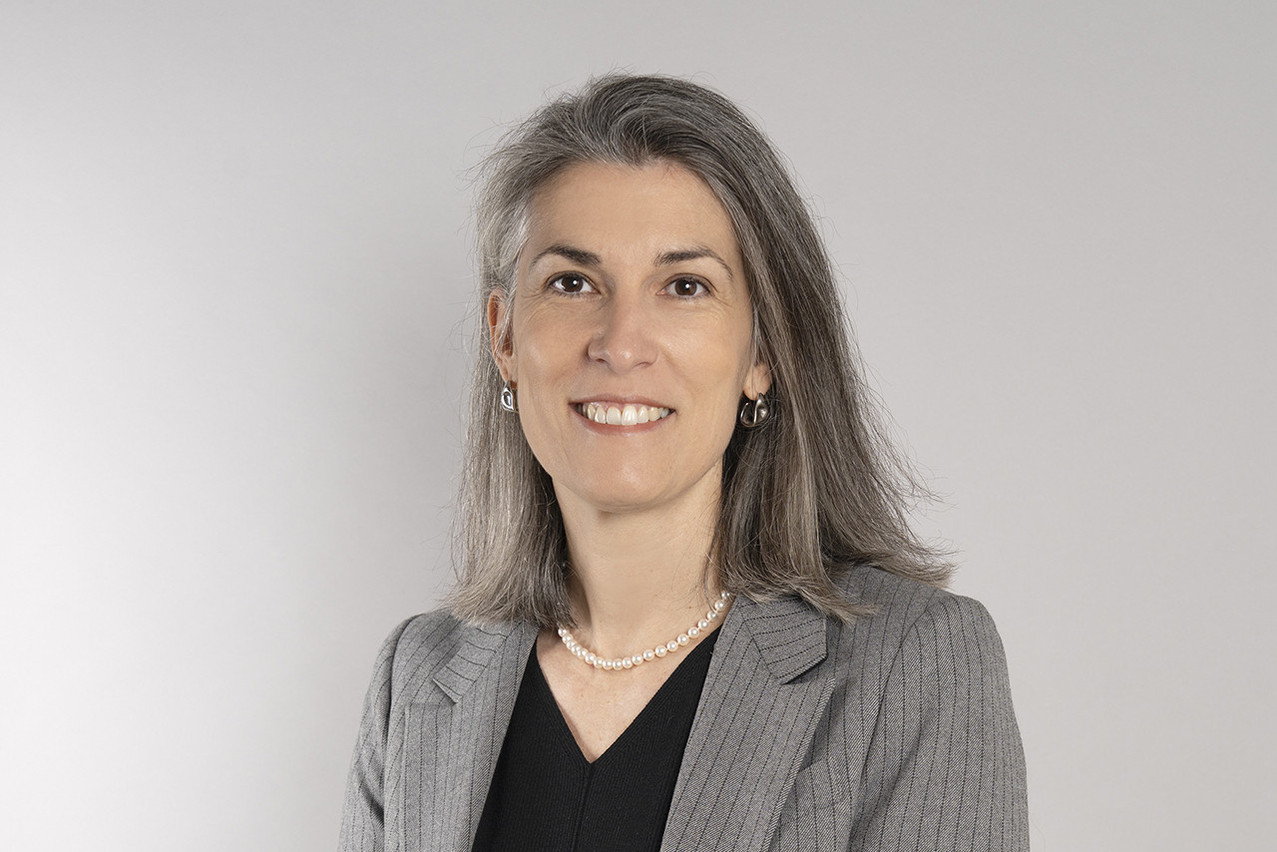
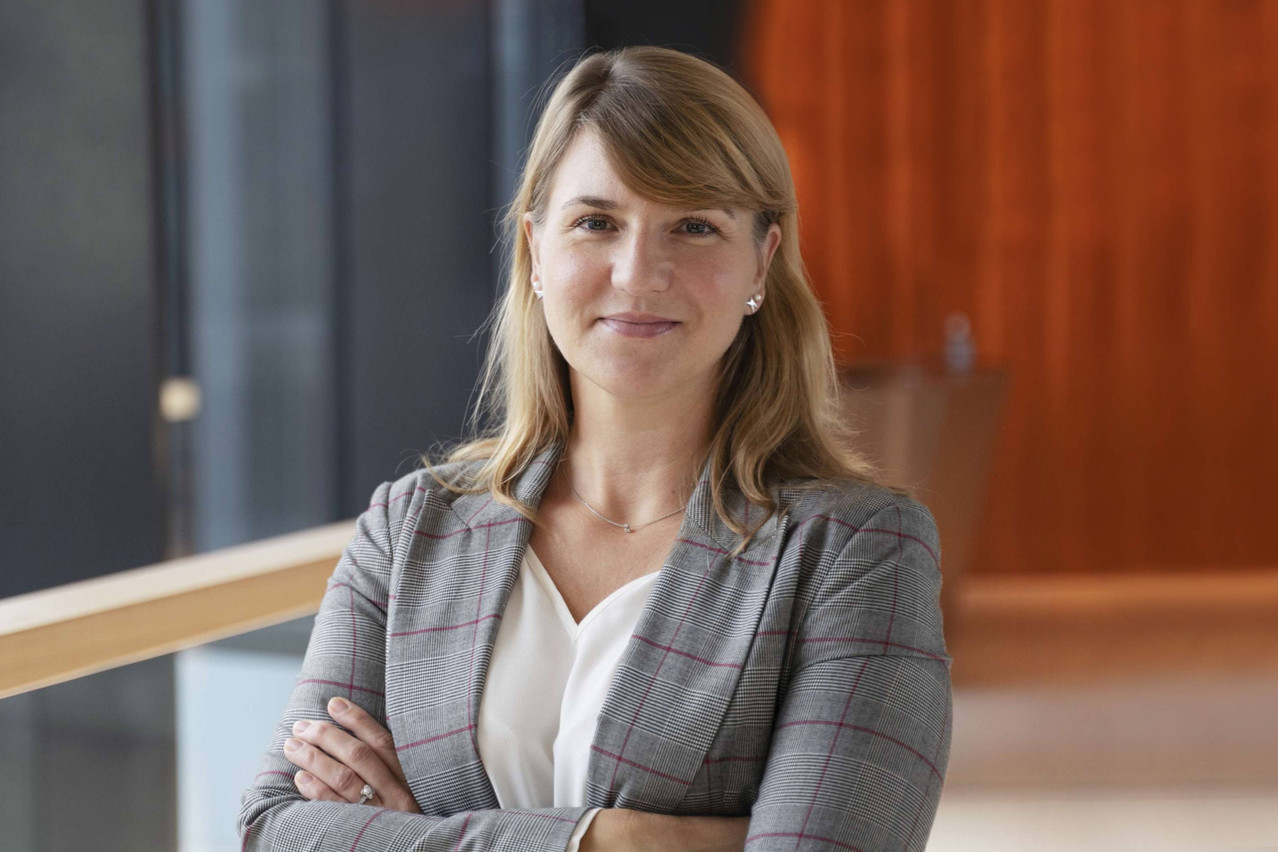
“On the one hand, we welcome regulation that strengthens the robustness and stability of the financial sector or brings clear benefits to customers. On the other, it can divert time and resources from key strategic projects,” Sandrine Roux, secretary general of the ABBL, sums up. (Photo: Olivier Minaire)
For 
The issue is all the more strategic given that Europe needs to mobilise between 750 and 800 billion euros a year to finance its digital and sustainable transition, according to an estimate recalled by the study. Yet almost 80% of the financing of European businesses is still provided by banks, giving the sector a central role in the success of this transformation.
For the ABBL, the equation is becoming increasingly complex. Its secretary general, Sandrine Roux, sums up the dilemma: “Finding the right balance in the cost of regulation is a complex equation to solve. On the one hand, we welcome regulation that strengthens the robustness and stability of the financial sector or brings clear benefits to customers. On the other, it can divert time and resources from key strategic projects.” She argues for greater proportionality and a “clear, consistent and fair” framework to preserve the ability of banks, particularly smaller ones, to support the economy.
The study, conducted among 22 banks representing around 20% of market assets and almost 40% of banking employment in Luxembourg, thus confirms that regulatory compliance remains one of the sector’s main cost drivers. A factor that will have a lasting impact on the strategic choices made by institutions, between prudential requirements, competitiveness and financing the economy.