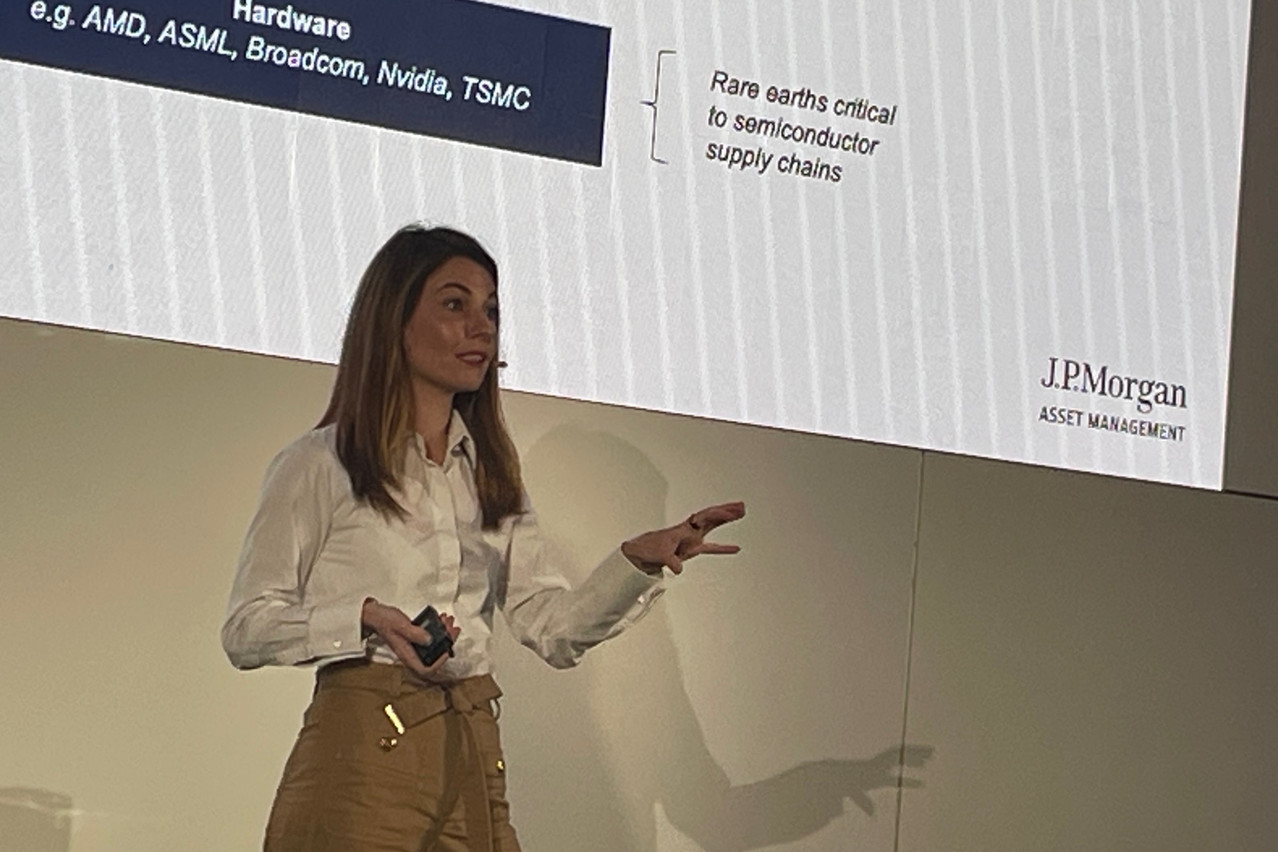
During her “Outlook 2026” presentation in Luxembourg on 9 December 2025, Lilia Peytavin, executive director and global market strategist of J.P. Morgan Asset Management, explained that the current macroeconomic environment has been “exceptionally supportive” of financial assets, with global equities rising 20%, twice their historical average. The performance occurred “despite acute geopolitical tensions and record high trade tariffs.”
“This [financial assets] performance is largely attributed to very strong support from both fiscal policies globally and accommodating monetary policies, which is unusual outside of recessions,” she said.
Ongoing fiscal support
Expectations are for continued substantial fiscal spending, including Germany joining the fiscal “party” with plans for €52bn in defence spending and expecting a 4% deficit, marking a paradigm shift for Europe.
In Asia, Japan has approved an €115bn stimulus plan for 2026. In the US, consumers are anticipated to receive $470bn in credit rebates early next year, likely boosting growth. “In the US, when you get money, you spend it,” observed Peytavin.
This supportive backdrop has pushed valuations higher across almost every asset class. Global equities are expensive, particularly the US, and credit spreads are very narrow, the tightest they have been since the early 2000s (see chart 1). “Everything is expensive, especially in the US.”
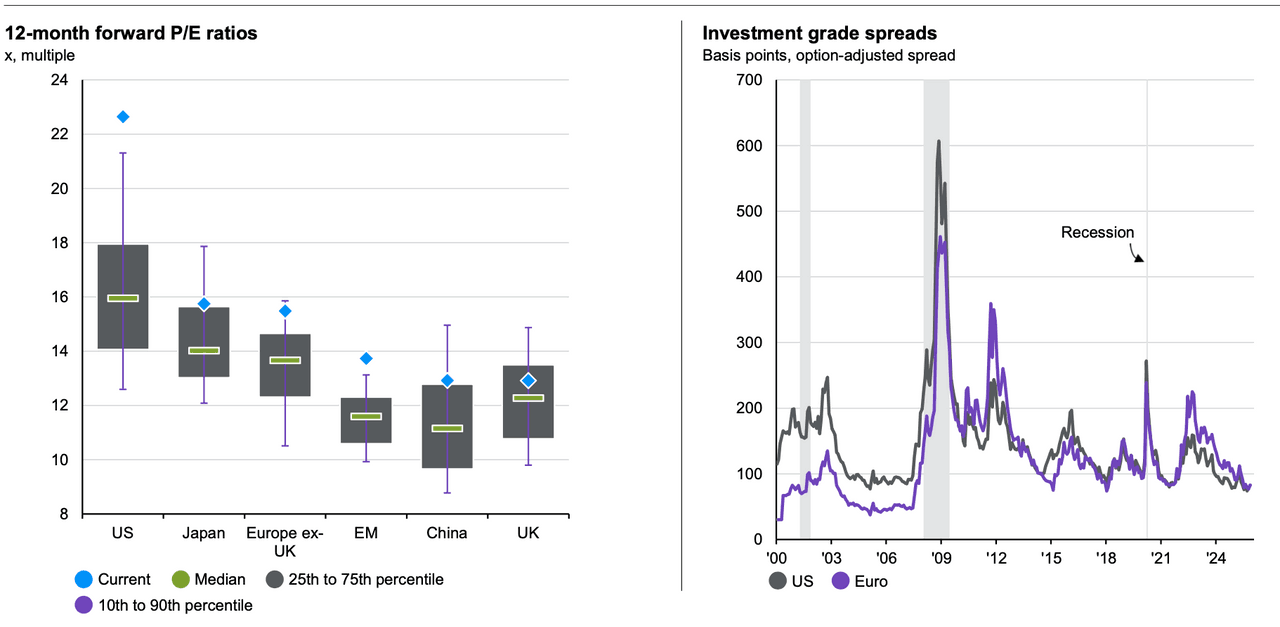
Chart 1: Positive macro backdrop largely priced-in in equities and credit markets J.P. Morgan Asset Management
Yet JPM AM prefers equities over credit, noting that while valuations are rising late cycle, the upside in credit is severely limited because spreads cannot narrow indefinitely. However, she warned that the substantial stimulus expected carries the risk of either inflation accelerating (overheating, reminiscent of the 1970s) or the formation of an asset bubble (like the 1990s).
Tech: handle with care
Peytavin acknowledged market concerns related to the concentration in the technology sector surrounding Artificial Intelligence (AI). She noted that techs account for about 40% of a typical global equity index portfolio (MSCI World). “An AI correction may lead to a recession, as 50% of US growth comes from the sector.”
On the bubble debate, she argued that we are at “a critical point around a breakthrough in terms of technological innovation.” The commercialisation size of this innovation remains highly uncertain. To make her case, she pointed to several key figures:
1. Only 5% of ChatGPT users pay for a subscription. OpenAI thinks that it can grow it to 8% by the end of 2030.
2. OpenAI’s revenues growing from ~$13bn today to $200bn by 2030, according to Peytavin, implies extremely aggressive annual growth expectations (CAGR of 54%).
3. Netflix and Spotify, leaders in their sector, make $50bn and $15bn per year, respectively.
Although comparisons are drawn to the 1990s internet bubble—where massive infrastructure investment led to cost collapse and disappointing returns—Peytavin considers the current environment to be less concerning.
Indeed, Peytavin takes comfort from valuations for AI companies that are approximately half of what low-profitability companies were in 1999. She noted that hardware companies (Nvidia, TSMC) exhibit extremely high growth and margins and robust balance sheets. “They are starting to use debt. But that's frankly tiny.” The highest risk is situated among companies facing end demand in the private markets, such as OpenAI or Anthropic.
The known unknown
Apple did not burn cash during the technological infrastructure capex spending boom in the late 1990s. Yet it reaped the benefits of others’ investments when it came out with smartphones and apps in the late 2000s.
Similarly, she stressed that it is unclear whether the winner(s) of tomorrow will come from AI architects (OpenAI, Mistral), hyperscalers (Alphabet, Meta, Microsoft) or the hardware sector (AMD, Nvidia). It (they) may also come from a brand-new sector.
Alternative options to US concentration
“Diversifying your portfolios played out well across regions, even though the AI rally has continued in 2025,” said Peytavin (see chart 2). She added, “Diversification does not only make your portfolio resilient in case of correction; it can also enhance your returns.”
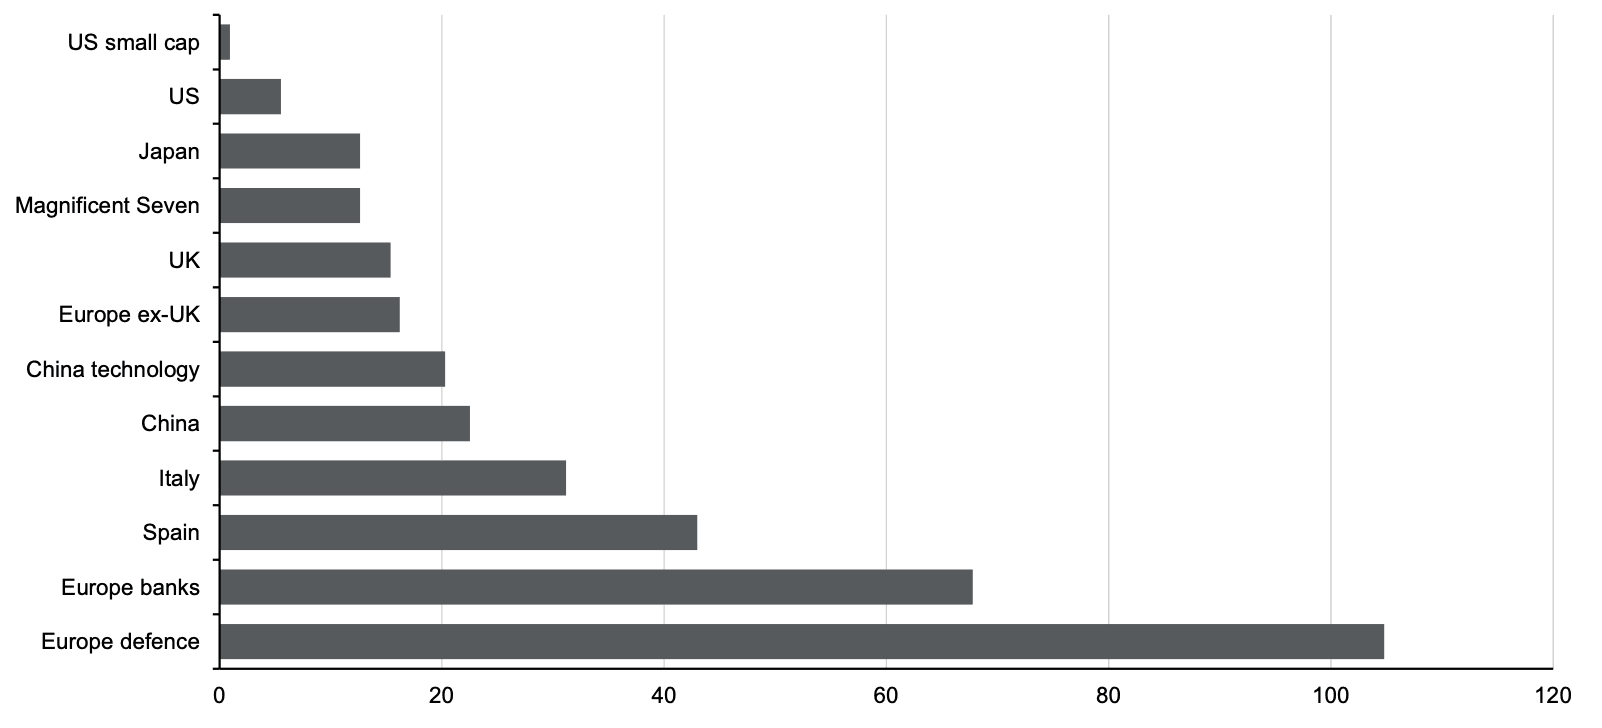
Chart 2: Total returns year to date (% total return in euros). Data as of 31 October 2025. J.P. Morgan Asset Management
1. China: In local currency, the market has had the best performance year-to-date (up 30%) and exhibits a strong innovative culture (e.g., Deepseek). She stressed that Chinese researchers are four times more cited than their US/European counterparts in AI research, and Chinese companies show higher daily adoption rates of AI (93% in China vs. 67% in the US).
2. Europe: It is the only major region where multiples remain attractive, with their valuations standing below their early 2022 levels. She expects earnings to improve as past headwinds, such as the strength of the euro and drops in commodity prices, subside.
3. Private markets: Peytavin argued that the industry is also critical for accessing AI exposure (e.g., OpenAI), having grown fivefold over the past decade to about $13trn. Companies are staying private longer (the median IPO age is now 14 years vs. 5 years in the early 1990s), making private markets key for capturing growth that historically occurred in public small caps.
“If you want more exposure to the AI ecosystem, you have really no option but to go into the private market,” claimed Peytavin. She remarked that valuations in private markets are high but are generally in line with public markets.
Pure downside protective assets
In a recession scenario, long-dated bonds and defensive equity sectors have historically provided protection. In the event of a gentle rise in inflation, assets like gold, real estate and inflation-linked bonds can help. However, to protect against a severe inflation shock as in 2022, private assets such as timber, infrastructure, and transport are necessary (see chart 3).

Chart 3: Selected public and private market returns in 2022(%Total return in USD) J.P. Morgan Asset Management