
Markets have proven impressively resilient against a volatile first six months of this year. But their steadfastness shouldn’t be surprising. Investors have become well-versed in seeing through the noise and recognising upside.
Now is not a time to shy away from risk, only to ensure it’s balanced in a well-diversified portfolio that will cushion the inevitable shocks when they come.
Investors are starting to look through the short-term noise and focus instead on the resilient fundamentals that should continue to support asset performance through the rest of this year. At the same time, the artificial intelligence (AI) capital expenditure cycle – the rise in companies’ long-term investments in artificial intelligence – remains a powerful upward driver for markets globally.
What began as a technological shift is increasingly shaping the broader economic cycle, providing a sustained tailwind for earnings and market performance. What matters here is less the theme itself than its reach: AI investment is no longer confined to the tech sector but is extending into infrastructure, energy, and industrial supply chains. This broadening effect across the market presents enticing entry points while attention is focused on a small number of high-valued tech names.
Big tech is going bigger on AI
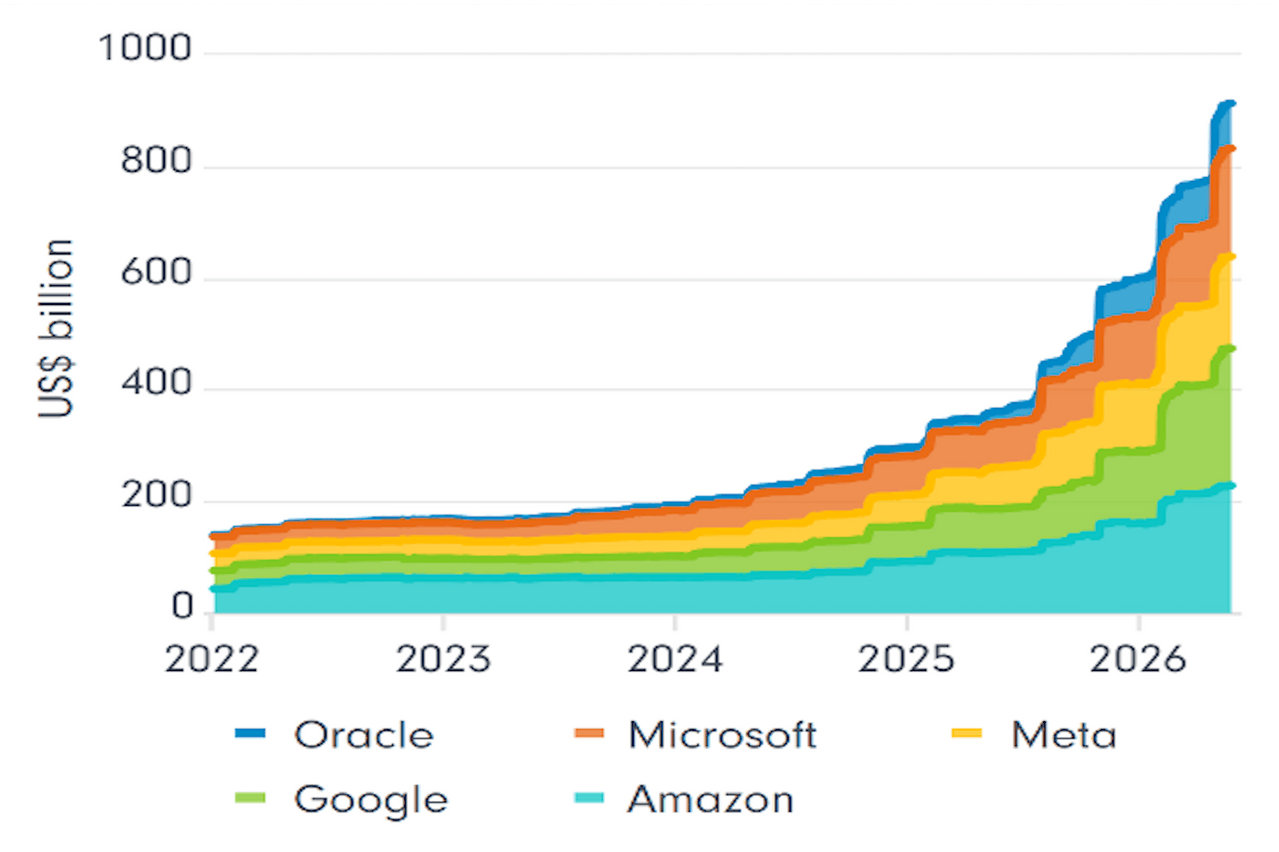
Chart shows the market’s expectation (based on Bloomberg analyst consensus) of how much companies will invest (capex), averaged across the next two years into a single forward-looking figure. Source: Fidelity International, Bloomberg, May 2026.
If artificial intelligence is supporting the upside, geopolitics and energy are shaping the risks. The notion of isolated shocks no longer holds; what matters now is how they interact and how quickly they feed through to inflation, policy, and growth.
Energy sits at the center of this dynamic. Supply disruptions linked to tensions in the Middle East have shown how rapidly constraints can push prices higher, reinforcing inflation and tightening financial conditions. Rather than fading, these pressures are becoming embedded, creating a more persistent drag on parts of the global economy.
The consequences are uneven. Economies more exposed to energy imports – particularly across Europe and parts of Asia – face a more challenging outlook, while others appear better placed to absorb these shocks. This divergence is becoming a defining feature of the current cycle.
It also complicates one of the core principles of investing: diversification. Relationships between asset classes are becoming less stable, with traditional hedges behaving differently depending on the nature of the shock.
Equities still offer a more compelling balance of return and resilience than other asset classes, particularly when credit spreads leave little margin for error. In fixed income, valuations appear increasingly sensitive to any deterioration in macro conditions, making selectivity essential.
Within equities, regional differences are becoming more pronounced. Japanese equities remain attractive, with earnings strong and a favourable policy backdrop. Emerging markets remain a high conviction allocation for us, benefitting from broader tailwinds such as the AI cycle, a softer dollar, and structurally improving policy credibility. But a discerning approach is required: less broad exposure, more about identifying where fundamentals and global trends intersect.
Traditional safe havens will not play the same role as they used to. And diversification should prove to be more important (but harder to achieve).
Safe-haven assets perform differently across market sell-off regimes
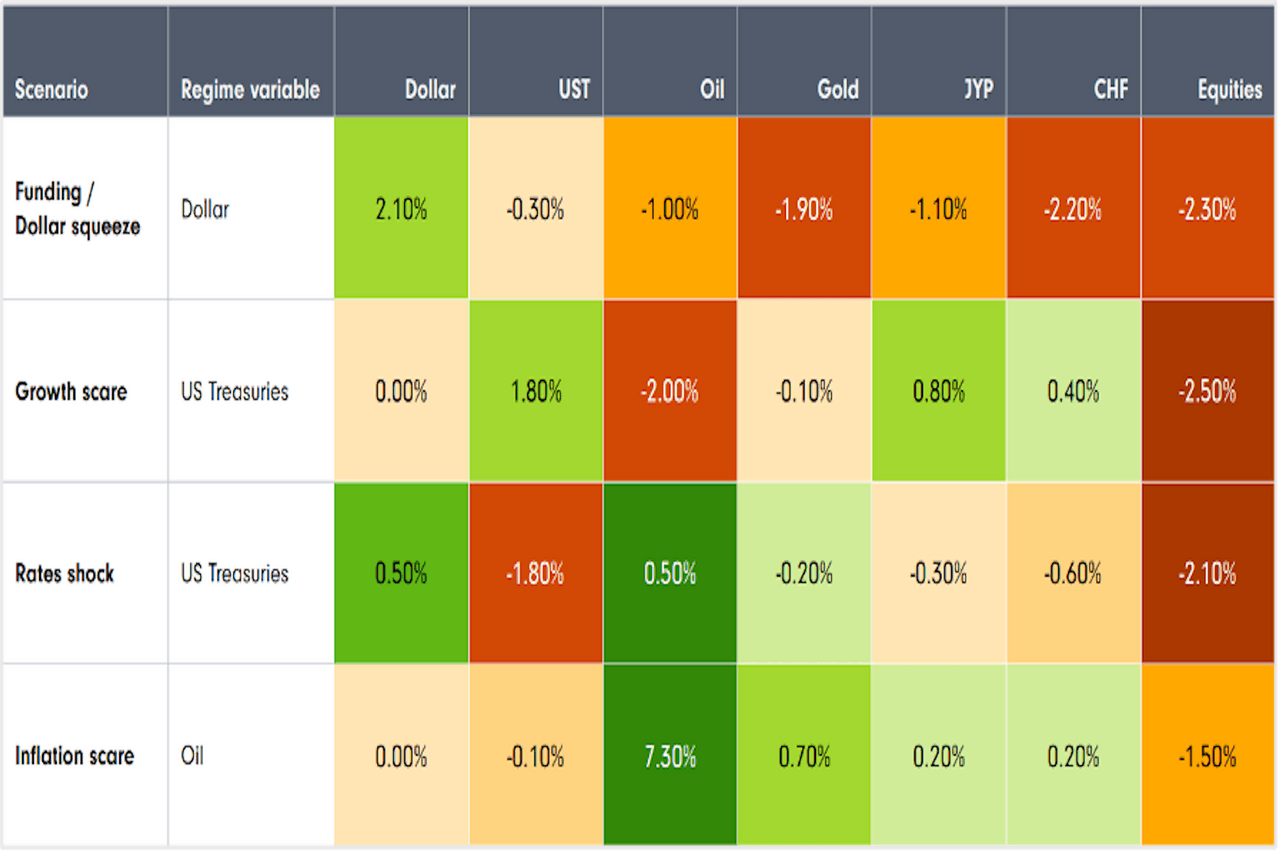
Based on weekly returns from January 1977 – April 2026. Dollar: DXY Index. UST: returns implied from the 10y US Treasury index. Oil: Generic 1st Crude WTI, backfilled with Bloomberg Commodity index prior to 1990. Gold: XAU Curncy. JPY: JPYUSD Curncy. CHF: CHFUSD Curncy. Equities: MSCI World Index, backfilled with S&P 500 Index prior to 1999. This chart shows how different assets behave during various types of market sell-offs, highlighting that “safe havens” are not universal but depend on the underlying shock – whether driven by growth, inflation, rates, or liquidity. Source: Fidelity International, Bloomberg, April 2026.
Past performance is not an indication of future results
In practical terms, this means there is no longer a single, reliable protection against risk. Assets such as government bonds may still provide support in growth-driven sell-offs but can struggle to offset losses in inflation-driven scenarios. Commodities and currencies can play that role, but their behaviour depends heavily on the underlying driver of stress.
The implication is a more flexible approach to portfolio construction, where diversification is no longer about fixed relationships but about understanding the source of risk. This is also reflected in relative opportunities across asset classes. While sovereign bonds can offer selective value where market expectations appear misaligned with fundamentals, credit remains less attractive given tight spreads and limited compensation for uncertainty.
Put simply, the challenge for investors has changed. In a market shaped by multiple, overlapping forces, resilience is less about broad positioning and more about selectivity – identifying where support is strongest, and where vulnerabilities are most likely to emerge.
Important Information
Reference to specific securities should not be construed as a recommendation to buy or sell these securities and is included for the purposes of illustration only. All investments carry risk and may result in the loss of capital.
Fidelity International refers to the group of companies which form the global investment management organisation that provides information on products and services in designated jurisdictions outside of United States of America. Unless otherwise stated all views expressed are those of Fidelity International. Views expressed may no longer be current. Fidelity, Fidelity International, the Fidelity International logo and F symbol are registered trademarks of FIL Limited.
Download the full Mid-Year Outlook 2026 from Fidelity International here