It's hard to know in advance the future of US-China relations over the coming year. Or to predict precisely the trajectory of commodities in the event of an escalation of conflicts in the Middle East. That said, volatility brings with it risks, but also opportunities for returns. The outlook for global earnings growth remains solid, and our overall view on equities to 2025 is positive. However, with valuations high, savvy investors will be looking for hedges in the event of a cyclical downturn. In this context, our approach is to stick to fundamentals, while remaining vigilant and disciplined on valuations.
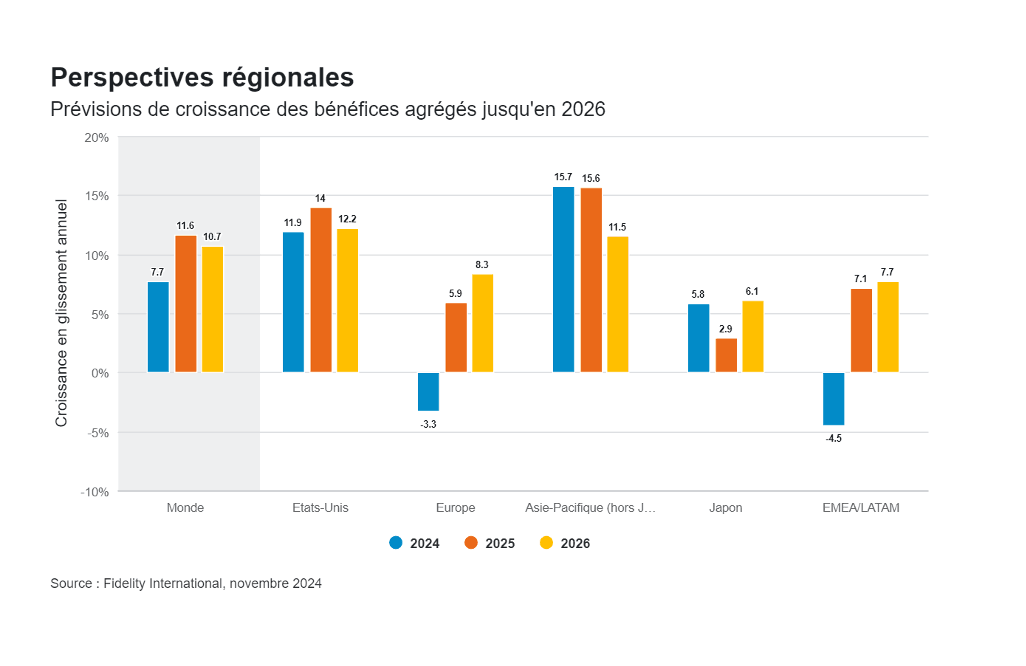
Equity outlook 2025: towards new leadership? (Chart: Fidelity International)
"America first"
Before the presidential election in Nov, we estimated that US corporate profits would increase by more than 14% in 2025. Donald Trump's victory has only boosted optimism among investors, who are anticipating a favourable year for business, growth and innovation. Some of the reflation induced by renewed Sino-American trade frictions will support earnings and allay fears of rising corporate valuations.
More generally, soft landing or reflation scenarios bode well for cyclical earnings. While regulatory relief should favour financial companies and "Value" sectors.
Despite this, investors are going to have to be more discerning. While the valuation of major technology companies is being debated, our attention is now turning to the companies that will be the first to benefit from AI. Less than a third of companies have so far embraced it, but more than 70% are planning to do so, suggesting that its impact on the economy will broaden. At the same time, while tax cuts as well as lower financing costs will benefit small and mid caps, a spike in inflation forcing the Fed to change its monetary course would negate these benefits.
Contrasting developed markets
In addition, the outlook for Japan in 2025 should remain favourable. The country remains on the path to reflation, with strong growth in wages and capital spending and steadily rising returns for shareholders. One caveat, however: the strength of the yen, combined with rising interest rates, could hurt earnings in a second phase, particularly in the consumer discretionary sector.
The situation in Europe is unlikely to improve. Recent profit warnings in sectors such as manufacturing and automotive underline the fact that doubts about the recovery in Chinese demand could continue to weigh on these stocks. In addition, the rise in US tariffs could cost Germany and the eurozone up to half a percentage point of GDP. That said, continued monetary easing should benefit European cyclicals. But the cheapest and most defensive bet at present is a 'yield' approach. Indeed, the dividend yield combined with share buybacks in some market areas is as high as 8%.
Asian potential
In China, policymakers are intent on preserving economic growth. While they recognise the need to stabilise property prices, they are not prepared to jeopardise the hard-won progress in debt reduction. So a gradual recovery in Chinese equities is the most likely scenario. With this in mind, we prefer sectors that are already among the government's political priorities: technology, high-end industry, consumer goods and healthcare. While, in general, this can be a volatile market, many undervalued companies have seen their share prices rebound to fair value following the country's political pivot.
More broadly, the Asean region is set to benefit greatly from the secular trend towards supply chain diversification and the rising share of foreign direct investment from around the world. Indonesia, in particular, has good growth and earnings momentum - although the predominance of banks makes the market vulnerable to interest rate cuts. Beyond that, India remains an asset for long-term investors. The country's prospects remain strong, underlined by favourable demographics and investment in infrastructure and manufacturing.
Go to our website to discover our outlook on the various asset classes: Outlook 2025
Risk information
This promotional document is intended exclusively for investment professionals and must not be distributed to retail investors.
The value of investments and the income derived from them may go down as well as up and the customer may not get back the full amount initially invested.
Investors should note that the opinions stated may no longer be current and may have already been acted upon.
Investments abroad may be affected by changes in currency exchange rates.
Investments in emerging markets may be more volatile than those in other more developed markets.
Important information
This document may not be reproduced or distributed without prior authorisation. Fidelity only provides information on its products and does not make investment recommendations based on specific circumstances. This document does not constitute an offer to subscribe or personal advice. Fidelity International refers to the group of companies that form the global investment management structure that provides product and service information in designated jurisdictions outside North America. This information is not intended for, and may not be used by, residents of the United States and is directed only at persons who are domiciled in a country or territory where the distribution of the sub-funds mentioned is authorised, or where such authorisation is not required. Unless otherwise stated, all information provided is that of Fidelity International, and all views expressed are those of Fidelity International. Fidelity, Fidelity International, the Fidelity International logo and the F symbol are registered trademarks of FIL Limited. Investment professionals include both analysts and associates. The trademark, copyright and other intellectual property rights are and shall remain the exclusive property of their respective owners. Published by FIL (Luxembourg) S.A., authorised and supervised by the CSSF (Commission de Surveillance du Secteur Financier). 24LU1201