Emerging market equities regained investors' attention in 2025, signing their first year of outperformance against developed markets - including the US - since 2017. This turnaround can be explained by the questioning of US "exceptionalism", rate cuts by the Federal Reserve, improved sentiment towards technology markets and sustained demand for artificial intelligence (AI). In 2026, the environment remains favourable.
Attractive valuations remain relevant
Despite a strong 2025, emerging equities continue to trade at a significant discount - close to 40% on a historical basis. This reflects the headwinds of recent years: a slowdown in China, rising global interest rates and a strong dollar, which weighed on valuations until the end of 2024. As the chart shows, the discount persists, suggesting potential for further upside.
Emerging markets trade at a ≈40% discount to the rest of the world
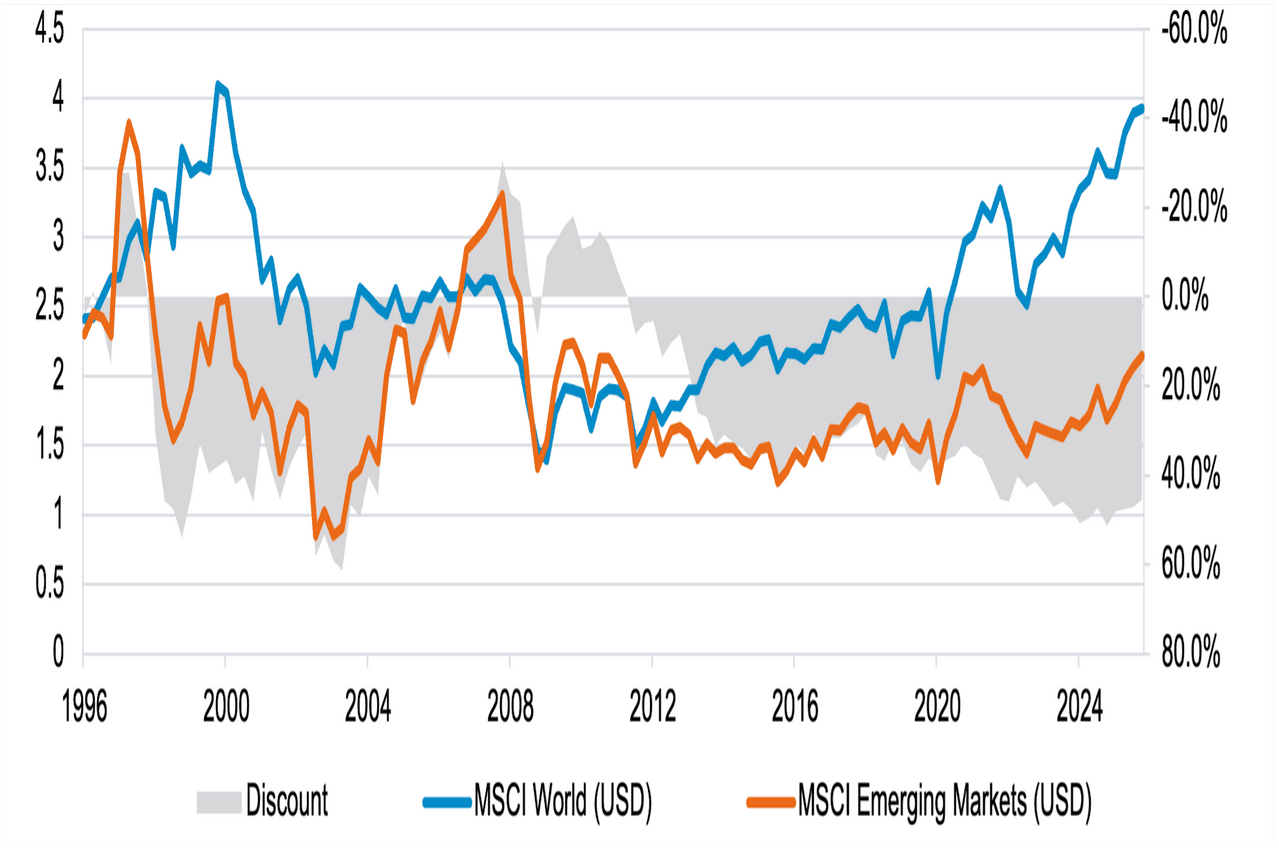
Bloomberg, 31 December 2025 (Photo: Fidelity International)
Improving macroeconomic conditions are also providing support
Many emerging countries entered 2026 with healthier public finances than developed economies. During the Covid-19 period, developed markets increased their fiscal spending, while a majority of emerging governments adopted more prudent management, preserving greater fiscal room for manoeuvre. The reported public debt spreads clearly illustrate this difference. With more room to deploy targeted measures, these economies are better positioned to mitigate potential risks to growth.
The fiscal framework appears stronger in emerging markets than in developed markets
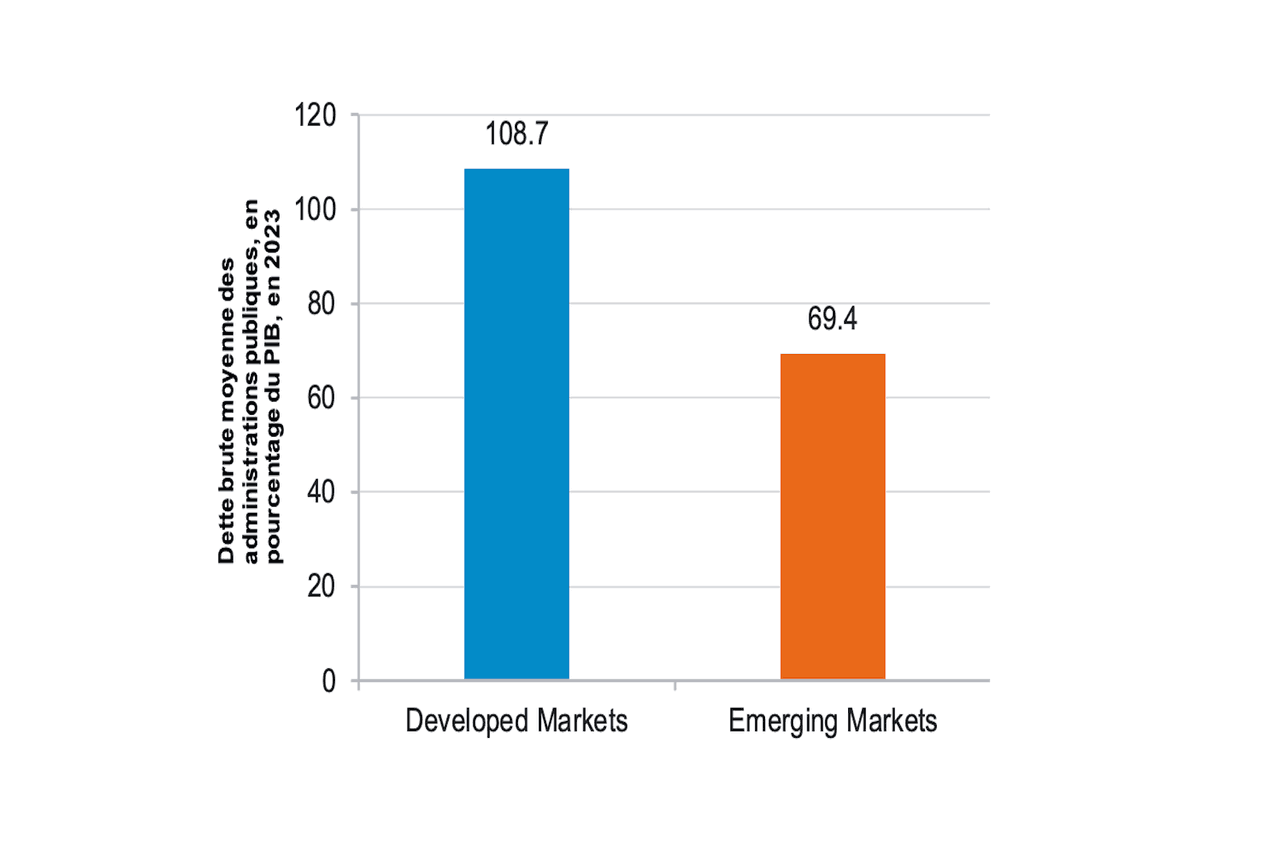
LSEG Datastream, IMF Fiscal Monitor, October 2024 (Photo: LHS: Fidelity International)
Exchange rate dynamics also play a key role
The weakening of the dollar in 2025 has reduced debt servicing costs for emerging borrowers and improved their purchasing power. Although emerging market performance no longer depends solely on a weak greenback, a stable or falling dollar remains supportive. In addition, many emerging countries have increased the sophistication of their financial markets and reduced the proportion of dollar-denominated debt, thereby gaining resilience.
Monetary policy adds another asset
Many emerging market central banks have raised rates from 2021-2022 to contain inflation which translates into high real rates, particularly in Brazil and parts of Europe, the Middle East and Africa. This leaves open the possibility of lower rates if global conditions ease further, creating a favourable backdrop for valuations.
Earnings growth prospects reinforce the potential of the asset class
Consensus expectations are for earnings growth of over 18% in 2026, a marked advantage over developed markets. Technological economies such as Taiwan and Korea, and commodity-rich regions such as South Africa, are contributing strongly to this dynamic. Investments in electrification, digital infrastructure and the reorganisation of value chains are also underpinning this growth, broadening and diversifying the earnings base.
Better earnings growth forecasts compared to developed markets
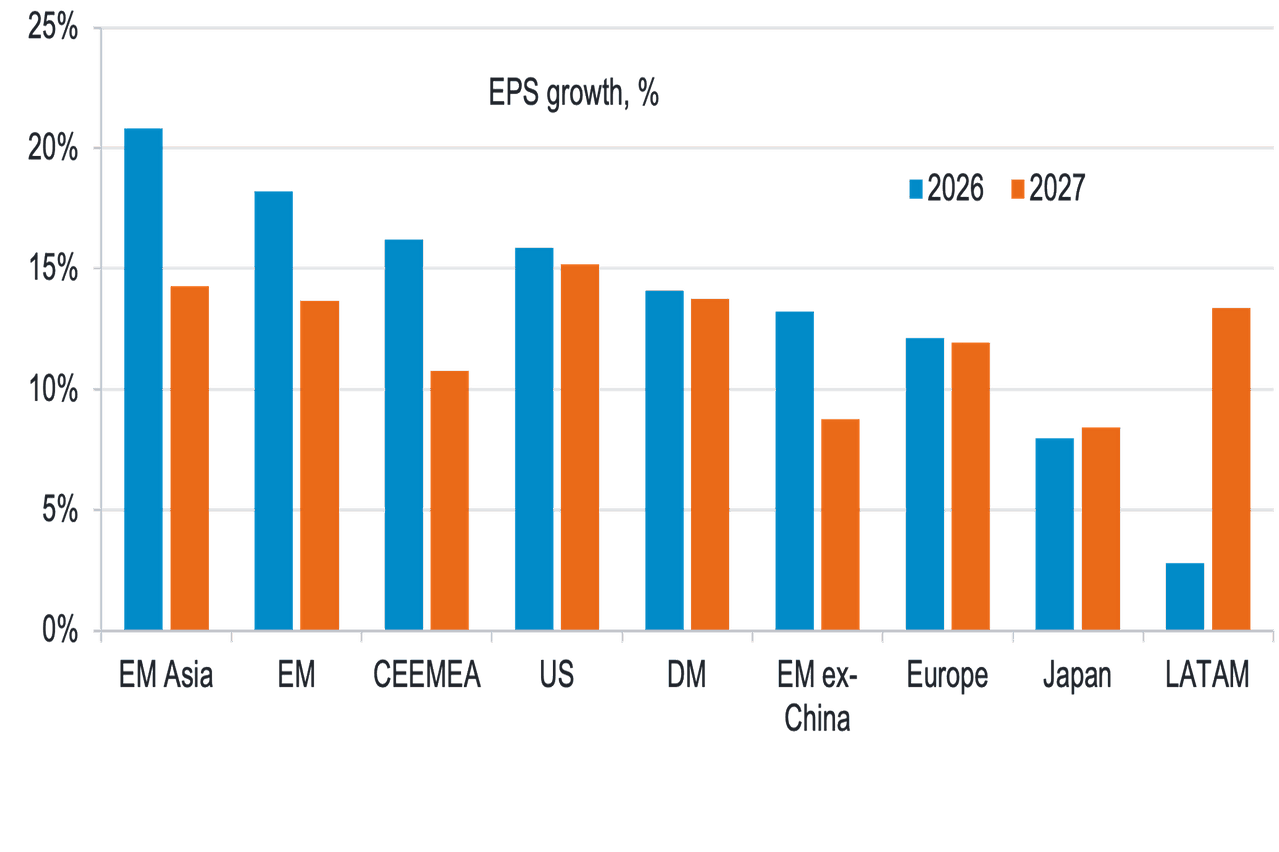
IBES estimates, as at 8 January 2025 (Photo: JB Morgan)
Technological leadership within the AI supply chain is a key driver
While the US dominates the debate around AI adoption, much of the hardware infrastructure is produced in emerging countries. Taiwan, and to a lesser extent Korea, play a central role in the manufacture of advanced semiconductors and data centre components. Several local companies are posting higher sales growth than their US counterparts, with more attractive valuations - as is the Taiwanese company Accton.
Commodity markets are also providing support
Copper and gold are benefiting from sustained demand against a backdrop of constrained supply. Demand for copper is being driven by the growing popularity of electric vehicles, electrification and the rapid expansion of data centres. Limits on new projects and the decline in ore quality are reinforcing a favourable price environment. Gold, for its part, is benefiting from the gradual diversification of central banks away from US government bonds. These trends are strengthening commodity-exporting countries within emerging markets.
China remains a complex case, but is showing several positive signals
Despite moderate household confidence, innovation in high value-added industrial segments - batteries, robotics and components for semi-conductors - supported by expanding R&D and a large pool of science and technology graduates is underpinning this trend. These segments represent pockets of resilience in a large and heterogeneous market.
Selectivity remains essential
Emerging markets show marked disparities in terms of valuations, governance and performance. Markets such as South Africa, Brazil and Mexico appear undervalued, while others such as India and Taiwan have higher multiples. This dispersion creates fertile ground for active managers and underlines the importance of stock selection based on fundamental analysis. Combined with economic, structural and valuation drivers, these factors suggest that emerging equities are well positioned to offer new opportunities in 2026.
Read the full article (in English)
Risk information:
- Opinions stated may no longer be current.
- Certain information presented is forward-looking and may be changed without notice.
- Past performance is not indicative of future performance. Investment results cannot be predicted or projected.
- Any investment involves risks, including a risk of capital loss.
- Investments in emerging markets generally have a higher level of volatility and risk than those in developed markets.
- The securities mentioned in this document do not constitute buy or sell recommendations. They are provided for illustrative purposes only.
Important information:
This document may not be reproduced or distributed without prior permission. Fidelity only provides information about its products and does not make investment recommendations based on specific circumstances. This document does not constitute an offer to subscribe or personal advice. Fidelity International refers to the group of companies that form the global investment management structure that provides product and service information in designated jurisdictions outside North America. This information is not intended for, and may not be used by, residents of the United States and is directed only at persons who are domiciled in a country or territory where the distribution of the sub-funds mentioned is authorised, or where such authorisation is not required. Unless otherwise stated, all information provided is that of Fidelity International and all views expressed are those of Fidelity International. Fidelity, Fidelity International, the Fidelity International logo and the F symbol are registered trademarks of FIL Limited. The trademark, copyright and other intellectual property rights are and shall remain the exclusive property of their respective owners. GEMS2666 - 26LU0204